Massachusetts Child Support and Life Insurance
How Massachusetts parents can use life insurance to secure child support obligations and protect children’s financial future.
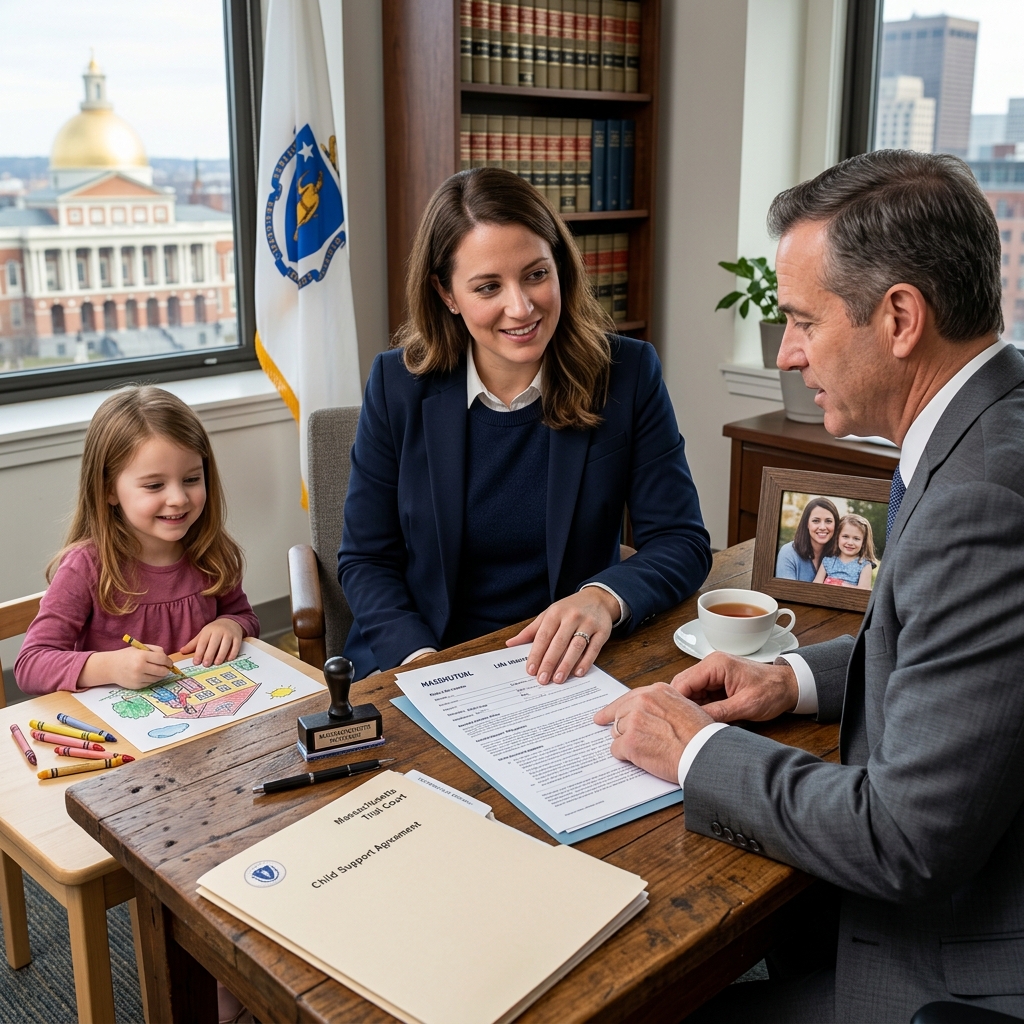
Parents in Massachusetts have a legal duty to support their children, and that duty usually continues even when parents separate or divorce. Child support orders are designed to cover daily living expenses, health care, and sometimes education costs. A crucial but often overlooked issue is what happens to child support if the paying parent dies. One of the most common tools to address this risk is life insurance tied to the support obligation.
This article explains how child support works in Massachusetts, why courts and lawyers often insist on life insurance as “security” for support, and the different ways parents can structure policies and beneficiaries to protect their children financially.
Overview of Child Support in Massachusetts
Child support in Massachusetts is a court-ordered payment from one parent to the other to help cover the costs of raising a child. It applies whether parents were married, in a partnership, or never lived together, as long as one parent is primarily responsible for the child’s day-to-day care.
Who Can Seek Child Support
- A parent who has primary physical custody of the child.
- A parent who shares custody but needs financial support based on income differences.
- A parent in a divorce, legal separation, custody, or paternity case, or in a separate child support action.
Parents can ask for support as part of a broader family-law proceeding (such as divorce or custody) or in a stand-alone child support case. In many situations, the Massachusetts Department of Revenue’s Child Support Enforcement Division helps parents apply for and enforce orders.
Duration of Child Support Obligations
In most cases, a parent must pay child support until the child reaches age 18. However, Massachusetts law allows payments to continue beyond 18 in specific circumstances, especially when the young adult still depends on the parent:
- Up to age 21 if the young adult lives with a parent and is primarily dependent on that parent.
- Up to age 23 if the young adult is primarily dependent on a parent while enrolled in an undergraduate program.
This extended timeframe is important when calculating how much life insurance may be needed to secure support, because the policy must cover the entire remaining period of the obligation.
How Courts Calculate Child Support
Judges use statewide Massachusetts Child Support Guidelines to determine how much support should be paid. These guidelines consider several factors, including:
- Each parent’s income.
- The number of children covered by the order.
- Child care costs and health insurance premiums.
- Parenting time arrangements (how much time the child spends with each parent).
As of the latest update, the guidelines take into account many types of income, including wages, bonuses, certain benefits, and even income from life insurance or endowment contracts. This broad definition ensures that child support reflects the parent’s true financial resources.
| Factor | Typical Impact |
|---|---|
| Parental income | Higher income generally leads to higher support obligations. |
| Number of children | Guidelines adjust upward for additional children. |
| Child care costs | Reasonable child care expenses are recognized and can increase the order. |
| Health insurance | One or both parents may be required to provide coverage if available at reasonable cost. |
| Special circumstances | Courts can deviate from guidelines to serve the child’s best interests. |
Why Life Insurance is Used to Secure Child Support
Child support orders assume that the paying parent will be alive and able to earn money during the support period. If that parent dies unexpectedly, future payments might stop, leaving the child and the other parent without the financial support the court intended. To avoid this risk, Massachusetts courts commonly require or encourage the use of life insurance as security for child support obligations.
Concept of “Security” for Support Obligations
In family law, “security” means a financial arrangement designed to guarantee that an obligation—such as child support or alimony—will be paid even if the payor dies or becomes unable to pay. Massachusetts law explicitly allows courts to require reasonable security for certain support obligations, including alimony, and similar principles are often applied in child support cases.
Life insurance is attractive as security because:
- It creates a lump sum of money on the insured parent’s death.
- Premiums can be relatively predictable and affordable compared with other security arrangements.
- Courts and lawyers can tailor policy amounts and beneficiary designations to match the support obligation.
Typical Court Orders Involving Life Insurance
In many divorce or child support judgments, the court may include language requiring the paying parent to:
- Maintain a life insurance policy with a minimum death benefit that approximates the remaining child support obligation.
- Keep specific individuals or entities as beneficiaries (for example, the other parent, the child, or a trustee).
- Provide annual proof that the policy remains in effect and that the required beneficiaries have not been changed without court approval.
These provisions help ensure that the policy does not lapse and that the funds will go to the intended recipient if the insured parent dies while support is still owed.
Choosing the Right Amount of Life Insurance
Determining an appropriate life insurance amount is both a legal and financial planning question. The goal is to create a death benefit large enough to replace the expected child support payments if the paying parent dies before the obligation ends.
Key Factors in Setting the Death Benefit
When lawyers and judges discuss how much life insurance a parent should carry, they often consider:
- Total remaining support based on weekly or monthly payments and the years left until emancipation (the end of the support period).
- Age and health of the paying parent, which affects insurability and premium costs.
- Existing policies already in place during the marriage or relationship.
- Children’s ages and whether support may extend beyond 18 due to education or continued dependency.
- Other financial obligations, such as college costs or health insurance premiums, that could be included in a settlement.
In some negotiations, parties may choose an amount slightly lower than the full projected obligation to reflect practical considerations, such as affordability or other assets available to the children. However, courts generally require that security be “reasonable” relative to the support obligation and the parent’s ability to obtain insurance.
Adjusting Coverage Over Time
It is common for separation agreements to allow the required insurance amount to decrease as children grow older and fewer years of support remain. For example:
- When the youngest child reaches a certain age, the minimum required death benefit may be reduced.
- Once all children are emancipated and the child support obligation ends, the legal requirement to maintain life insurance for child support purposes usually ends as well.
Parents can structure these changes in the agreement so the policy remains aligned with the real financial risk over time.
Selecting Beneficiaries for Child Support-Related Policies
One of the most sensitive decisions is who should receive the insurance proceeds if the paying parent dies. The choice of beneficiary affects both legal control and practical management of the funds intended for the child.
Possible Beneficiary Options
- The other parent who receives child support.
- The child or children directly.
- A trust established for the children’s benefit.
- A custodian under a minor-transfer statute.
Each option has advantages and drawbacks, and the best choice often depends on the level of cooperation between parents, the children’s ages, and the family’s financial complexity.
Naming the Other Parent as Beneficiary
Many parents and courts prefer to name the parent who receives child support as beneficiary. This approach ensures that the surviving parent has immediate access to funds needed for housing, food, medical care, and education. It also avoids the need for court-appointed guardians to manage the money for minor children.
However, this arrangement relies on the surviving parent to manage the funds responsibly for the children’s benefit. In situations involving serious mistrust or concerns about spending, parents may explore alternatives such as trusts or custodial accounts.
Naming Children as Beneficiaries
Listing minor children directly as beneficiaries can seem straightforward, but it raises practical issues. Children under the age of majority cannot receive large sums directly. In Massachusetts, a child reaches legal adulthood at age 18, and insurance proceeds for younger children would require oversight by a guardian or custodian appointed by a court.
If children are named directly, families may need to account for:
- Appointment of a guardian to manage funds until the child turns 18.
- Potential delays and legal costs in the probate process.
- Limited flexibility if multiple children have different needs.
Using Trusts or Custodial Arrangements
To balance control and child-focused spending, parents often consider:
- Trusts drafted by an estate planning or family law attorney.
- Custodial designations under state laws that govern transfers to minors (such as uniform transfers statutes).
With a trust, the policy pays into a fund managed by a trustee who must follow written instructions about how money is used for the children’s benefit. Custodial arrangements similarly put an adult in charge of funds but with simpler formalities. These strategies can offer greater assurance that insurance proceeds will support the children over time rather than being spent quickly or diverted to other purposes.
Alternatives When Life Insurance Is Not Available
Not every parent can purchase life insurance. Health issues, age, or financial limitations may make traditional coverage impractical. When life insurance is unavailable or inadequate, families and courts sometimes look to other assets to secure child support and alimony obligations.
Using Retirement or Investment Accounts
One alternative is to designate the support recipient—or a trust for the children—as a beneficiary on retirement accounts, such as employer-sponsored plans or individual retirement accounts. Similar beneficiary arrangements may be possible with other financial assets:
- Investment accounts with “transfer on death” instructions.
- Payable-on-death bank accounts.
- Other non-probate assets that pass directly to named beneficiaries.
These assets can be integrated into a comprehensive support and estate plan so that, if the paying parent dies, funds are available to offset the loss of future support payments.
Balancing Security with Practical Constraints
Courts generally seek a reasonable balance between protecting children and recognizing real-world limits. If a parent is truly uninsurable or cannot afford premiums, judges may consider alternative forms of security or adjust expectations. Documentation of attempts to obtain coverage and evidence of financial constraints can be important in these situations.
Interaction Between Child Support, Alimony, and Insurance
Many divorces involve both child support and alimony. Massachusetts appellate decisions and newer guidelines describe structured methods to evaluate how these two forms of support interact when calculating obligations. Because life insurance can secure both types of payments, the total coverage amount and beneficiary structure often require coordinated planning.
For example, Massachusetts law allows courts to order reasonable security for alimony, taking into account factors such as the payor’s age, insurability, and the duration of the alimony order. When child support and alimony are both in play, a single life insurance policy may be designed to address both obligations, or separate policies may be used to simplify beneficiary designations.
Practical Tips for Parents Negotiating Life Insurance
Parents negotiating a separation agreement or parenting plan in Massachusetts can take several practical steps to ensure that life insurance provisions are clear, fair, and workable over time.
- Calculate realistic coverage: Estimate the total value of future child support and, if applicable, alimony, then discuss an insurance amount that closely matches that exposure.
- Plan for decreasing needs: Include terms that allow coverage to decrease as children reach adulthood or as obligations are satisfied.
- Define beneficiaries carefully: Decide whether the other parent, a trust, or a custodian is best positioned to manage funds for the children.
- Require documentation: Build in a requirement that the insured parent provide annual proof of active coverage and beneficiary designations.
- Coordinate with estate planning: Align insurance provisions with wills, trusts, and other estate planning documents to avoid conflicts.
Frequently Asked Questions (FAQs)
Does Massachusetts law always require life insurance for child support?
No. Massachusetts courts may require life insurance as reasonable security for support, but it is not mandatory in every case. The decision depends on factors such as the size of the obligation, the parent’s insurability, and the overall financial circumstances.
What happens if the paying parent dies without life insurance?
If a paying parent dies without life insurance or other security, remaining child support may become difficult or impossible to collect. The surviving parent might seek funds from the deceased parent’s estate, but the outcome depends on available assets and the estate’s debts. Life insurance helps prevent this uncertainty by providing a dedicated source of funds.
Can the required insurance amount change after the divorce?
Yes. Separation agreements and court orders can allow the required death benefit to decrease over time, especially as children grow older and fewer years of support remain. Parents may also ask the court to modify orders if circumstances change significantly.
Do Massachusetts child support guidelines consider life insurance as income?
The Massachusetts Child Support Guidelines recognize income from life insurance or endowment contracts as part of the definition of income, which can affect support calculations when such income is actually received. However, simply owning a policy with a death benefit is not, by itself, treated as income for guideline purposes.
Who helps enforce child support orders in Massachusetts?
The Massachusetts Child Support Enforcement Division, part of the Department of Revenue, assists with enforcing child support orders, collecting payments, and reviewing orders for potential modification. Life insurance provisions are typically enforced through the court that issued the original judgment.
References
- Securing Child Support Obligations Through Life Insurance — DivorceNet. 2023-05-01. https://www.divorcenet.com/states/massachusetts/child_support_and_life_insurance
- Life Insurance as Security for Child Support or Alimony Payments — Worcester County National Law LLP. 2020-06-15. https://wcnllp.com/life-insurance-as-security-for-child-support-or-alimony-payments/
- Massachusetts Child Support — WomensLaw.org. 2023-02-10. https://www.womenslaw.org/laws/ma/child-support
- Massachusetts Child Support Guidelines — FindLaw. 2022-09-01. https://www.findlaw.com/state/massachusetts-law/massachusetts-child-support-guidelines.html
- 2025 Child Support Guidelines Section I: Income Definition — Massachusetts Trial Court. 2024-12-01. https://www.mass.gov/info-details/2025-child-support-guidelines-section-i-income-definition
- Client Alert: Massachusetts Announces New Child Support Guidelines Effective December 1, 2025 — Casner & Edwards. 2024-07-01. https://www.casneredwards.com/news/massachusetts-announces-new-child-support-guidelines-effective-december-1-2025/
- Learn About Receiving Child Support — Mass.gov. 2023-11-15. https://www.mass.gov/info-details/learn-about-receiving-child-support
Similar Articles

Read full bio of medha deb