Understanding Worker Classification for Small Businesses
Learn how to correctly classify employees and independent contractors to avoid penalties and protect your business.
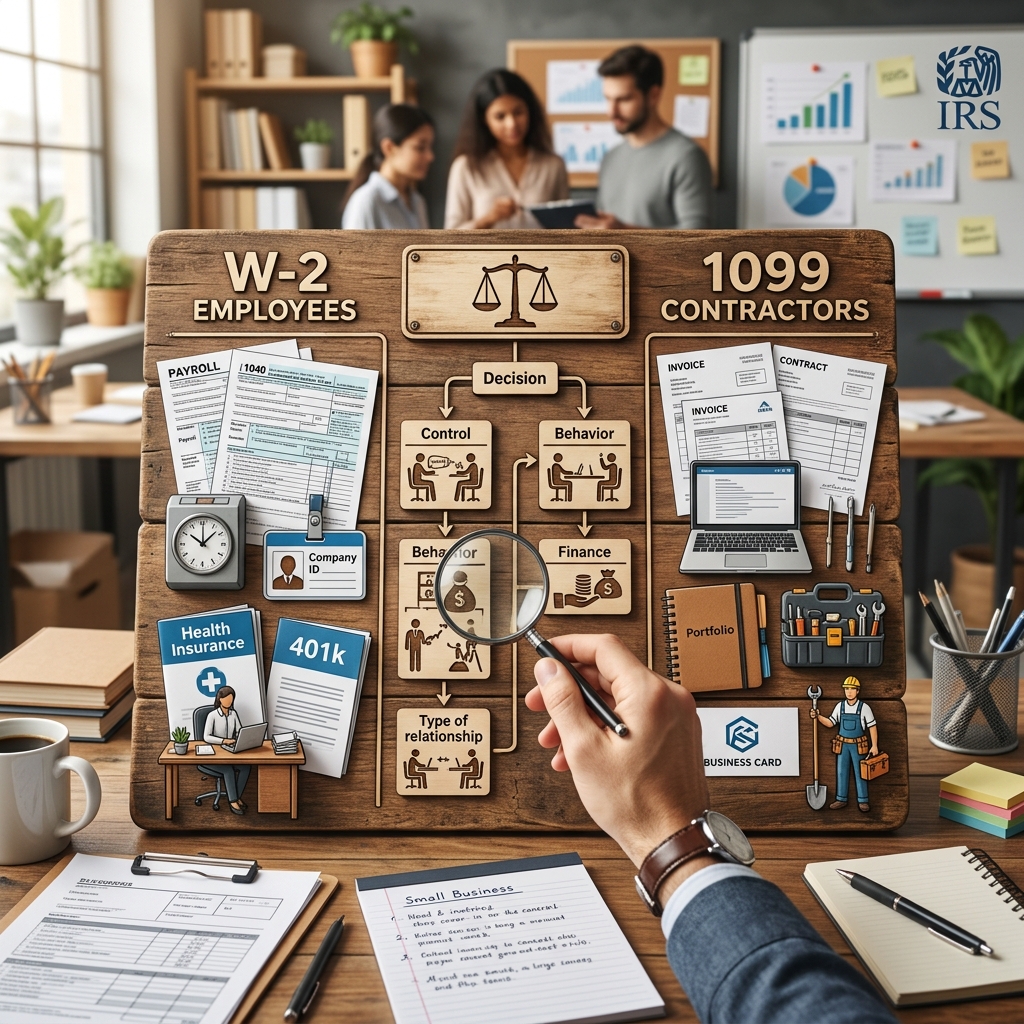
Correctly identifying whether a worker is an employee or an independent contractor is a core legal responsibility for every small business. Misclassification can lead to unpaid wages, tax liabilities, penalties, and legal disputes, so it is essential to understand the rules and apply them consistently.
This guide explains the main classification frameworks used in the United States, highlights common risk areas, and offers practical steps you can take to reduce compliance problems in your business.
Why Worker Classification Matters
Worker classification affects nearly every aspect of the employment relationship, from tax reporting to benefits eligibility and labor protections. When a worker is treated as an independent contractor but legally qualifies as an employee, that worker may be denied important rights, and the business may face significant liability.
Key Impacts of Classification Decisions
- Tax obligations: Employers must withhold and pay certain employment taxes for employees, but not for independent contractors.
- Wage and hour protections: Employees are covered by minimum wage and overtime provisions under the Fair Labor Standards Act (FLSA), while independent contractors generally are not.
- Benefits and insurance: Employees may be eligible for employer-sponsored benefits, workers’ compensation, and unemployment insurance; contractors typically are responsible for their own coverage.
- Recordkeeping and reporting: Employees usually receive Form W-2, whereas independent contractors are often reported on Form 1099-NEC or similar forms.[10]
Misclassification is more than a technical mistake. According to the U.S. Department of Labor, treating employees as independent contractors can deprive workers of minimum wage, overtime pay, and other protections, while also giving noncompliant businesses an unfair competitive advantage.
Overview of Major Worker Classification Tests
No single universal test applies in every context. Different agencies and laws use distinct—but overlapping—criteria to decide whether someone is an employee or an independent contractor. The three most common frameworks are:
- The IRS common law rules
- The FLSA economic reality test
- The ABC test, used in some states and specific statutes
Comparison of Common Tests
| Test | Primary Use | Core Focus |
|---|---|---|
| IRS Common Law Rules | Federal employment tax and reporting | Behavioral control, financial control, and nature of the relationship |
| FLSA Economic Reality Test | Minimum wage and overtime under FLSA | Economic dependence and six factors of work relationship |
| ABC Test | State wage and labor laws (in some jurisdictions) | Three strict conditions related to control, type of work, and independent business |
The IRS Common Law Rules: Control and Relationship
The Internal Revenue Service uses a three-category framework to determine whether a worker is an employee for federal tax purposes. All evidence of the degree of control and independence should be considered together.
Behavioral Control
Behavioral control asks whether the business has the right to direct what the worker does and how they do it. The more detailed the instructions and supervision, the more likely the worker is an employee.
- Instructions on when, where, and how to work
- Training and performance procedures supplied by the business
- Requirements to follow a specific sequence or method of tasks
If a worker must follow company instructions closely and cannot determine their own work methods, that points toward employee status.
Financial Control
Financial control examines who controls the business aspects of the work, including how the worker is paid and whether they can realize a profit or loss.
- Method of payment: periodic wages vs. payment by project or deliverable
- Reimbursement of expenses and provision of tools or equipment
- Opportunity for profit or loss linked to managerial skill and business decisions
Workers who invest in their own tools and bear the risk of loss—while also having a chance to increase profits through their own decisions—are more likely to be independent contractors than employees.
Nature of the Relationship
The relationship of the parties focuses on whether the arrangement appears permanent, whether the worker receives employee-type benefits, and whether the work performed is central to the business.
- Written contracts and how they describe the relationship
- Provision of benefits such as retirement plans, insurance, or paid leave
- Ongoing or indefinite arrangements vs. project-specific engagements
- Whether the work is a key part of the company’s regular activities
A worker who is integrated into daily operations, performs core business functions, and maintains a long-term relationship with the company is more likely to be legally considered an employee.
The FLSA Economic Reality Test
For wage and hour purposes, the U.S. Department of Labor applies an economic reality analysis under the FLSA. A 2024 rule emphasizes six key factors to determine whether a worker is economically dependent on the employer or in business for themself.
Six Economic Reality Factors
- Opportunity for profit or loss based on managerial skill, such as negotiating pay, choosing jobs, or managing time and expenses.
- Investments by both the worker and the business, including equipment, facilities, and training.
- Degree of permanence in the working relationship, with indefinite arrangements suggesting employee status.
- Nature and degree of control exercised by the employer over schedules, performance, and work methods.
- Integral part of the business: whether the work performed is central to the employer’s main services or products.
- Skill and initiative: whether specialized skills are used in an independent, entrepreneurial way or under close direction.
None of these factors alone decides the outcome. Instead, the overall economic reality of the relationship indicates whether the worker is an employee who is economically dependent on the business or an independent contractor in business on their own.
The ABC Test: A Stricter Standard
Some states and specific laws apply the ABC test, which is often more demanding for businesses wishing to classify workers as independent contractors. Under this test, a worker is considered an employee unless the business demonstrates three elements.
- A: Freedom from control – The worker is free from the hiring entity’s control and direction in performing the work, both under contract and in practice.
- B: Work outside usual course of business – The work performed is outside the usual course of the company’s business.
- C: Independent trade or business – The worker is customarily engaged in an independently established trade, occupation, or business of the same nature.
Failing any one of these prongs may result in the worker being treated as an employee for purposes of the law applying the ABC test. This can significantly influence how small businesses structure relationships with freelancers and subcontractors.
Practical Steps for Small Businesses
Even with clear definitions, applying these tests in real-world situations can be challenging. The following steps can help business owners build compliant processes and reduce misclassification risk.
1. Analyze Roles Before Hiring
- Identify whether the work is a core part of your business or an ancillary service.
- Decide how much control you need over scheduling, methods, and performance.
- Consider whether the worker is likely to market similar services to other clients independently.
When you realize that a role requires ongoing oversight, integration into the team, and continuous availability, an employee classification often better reflects the legal reality.
2. Draft Clear Agreements
Written contracts are important for both employees and independent contractors, but they do not override how the relationship functions in practice.
- For employees, specify duties, hours, compensation, and eligibility for benefits.
- For contractors, clarify project scope, payment terms, responsibility for taxes, and autonomy over work methods.
- Avoid language that suggests control inconsistent with independent contractor status, especially if work is central to the business.
3. Document Your Classification Reasoning
The IRS recommends documenting the factors considered in making classification decisions.
- Summarize behavioral, financial, and relationship factors for each role.
- Retain copies of contracts, invoices, and communication that show the level of control and independence.
- Update documentation when responsibilities or work patterns change.
If uncertainty remains, businesses may submit Form SS-8 to the IRS to request an official determination of worker status for federal tax purposes.
4. Review Relationships Regularly
Roles evolve, and a relationship that started as a genuinely independent contracting arrangement can gradually become more like employment.
- Schedule periodic reviews of contractor and employee roles.
- Assess whether contractors remain free to choose clients and control their work methods.
- Reclassify workers promptly if the economic reality or degree of control has changed.
Common Red Flags of Misclassification
Some patterns frequently signal that a worker labeled as a contractor may legally be an employee.
- The worker has a permanent, full-time schedule and works only for your business.
- You set detailed instructions about where, when, and how tasks must be done.
- The worker uses company tools and facilities and does not invest in their own business infrastructure.
- The services performed are central to your main products or services.
- The worker receives benefits comparable to employees and expects long-term employment-like security.
When several of these indicators are present, it is prudent to reevaluate classification and seek legal or tax advice.
FAQs About Worker Classification
Does issuing a 1099 automatically make someone an independent contractor?
No. Providing a Form 1099-NEC instead of a W-2 does not itself determine legal status. A worker may still qualify as an employee under labor and tax laws even if they receive a 1099.[10]
Can a worker be an employee for one law and a contractor for another?
Yes. Because different tests apply to different statutes and agencies, a worker might be treated as an employee for wage and hour purposes but as an independent contractor under certain tax or state laws, depending on how the tests are applied.
Is a written contract enough to avoid misclassification problems?
Written contracts help clarify expectations, but the actual working relationship carries more weight. If the reality of the arrangement shows employee-level control and dependence, a contract labeling the worker as a contractor will not prevent reclassification.
How often should small businesses review worker classifications?
There is no fixed legal schedule, but reviewing classifications annually or whenever responsibilities substantially change is a good practice. Regular reviews help ensure roles still meet applicable legal criteria.
What should I do if I am unsure how to classify a worker?
Consider consulting an employment law professional or tax advisor. For federal tax questions, you may request an IRS determination using Form SS-8, which evaluates control and independence factors to decide status.
References
- Misclassification of Employees as Independent Contractors Under the Fair Labor Standards Act — U.S. Department of Labor, Wage and Hour Division. 2024-01-10. https://www.dol.gov/agencies/whd/flsa/misclassification
- Independent Contractor (Self-Employed) or Employee? — Internal Revenue Service. 2023-03-02. https://www.irs.gov/businesses/small-businesses-self-employed/independent-contractor-self-employed-or-employee
- Worker Classification 101: Employee or Independent Contractor — Internal Revenue Service. 2022-11-09. https://www.irs.gov/newsroom/worker-classification-101-employee-or-independent-contractor
- Recent Developments in U.S. Worker Classification Rules — A&O Shearman. 2024-03-01. https://www.aoshearman.com/en/insights/recent-developments-in-us-worker-classification-rules
- Employee Classification: A Guide for HR and Business Owners — Lattice. 2023-07-18. https://lattice.com/articles/employee-classification-a-guide-for-hr-and-business-owners
- Employee or Contractor? What Small Businesses Need to Know — Rhode Island Small Business Development Center, University of Rhode Island. 2022-05-05. https://web.uri.edu/risbdc/employee-or-contractor-what-small-businesses-need-to-know/
- Independent Contractors — New York State Department of Labor. 2021-09-01. https://dol.ny.gov/independent-contractors
Similar Articles








Read full bio of Sneha Tete