
Dodd-Frank Act Explained: A Clear Guide For Investors In 2025
A clear guide to the Dodd-Frank Wall Street Reform and Consumer Protection Act and how it reshaped U.S. financial regulation.
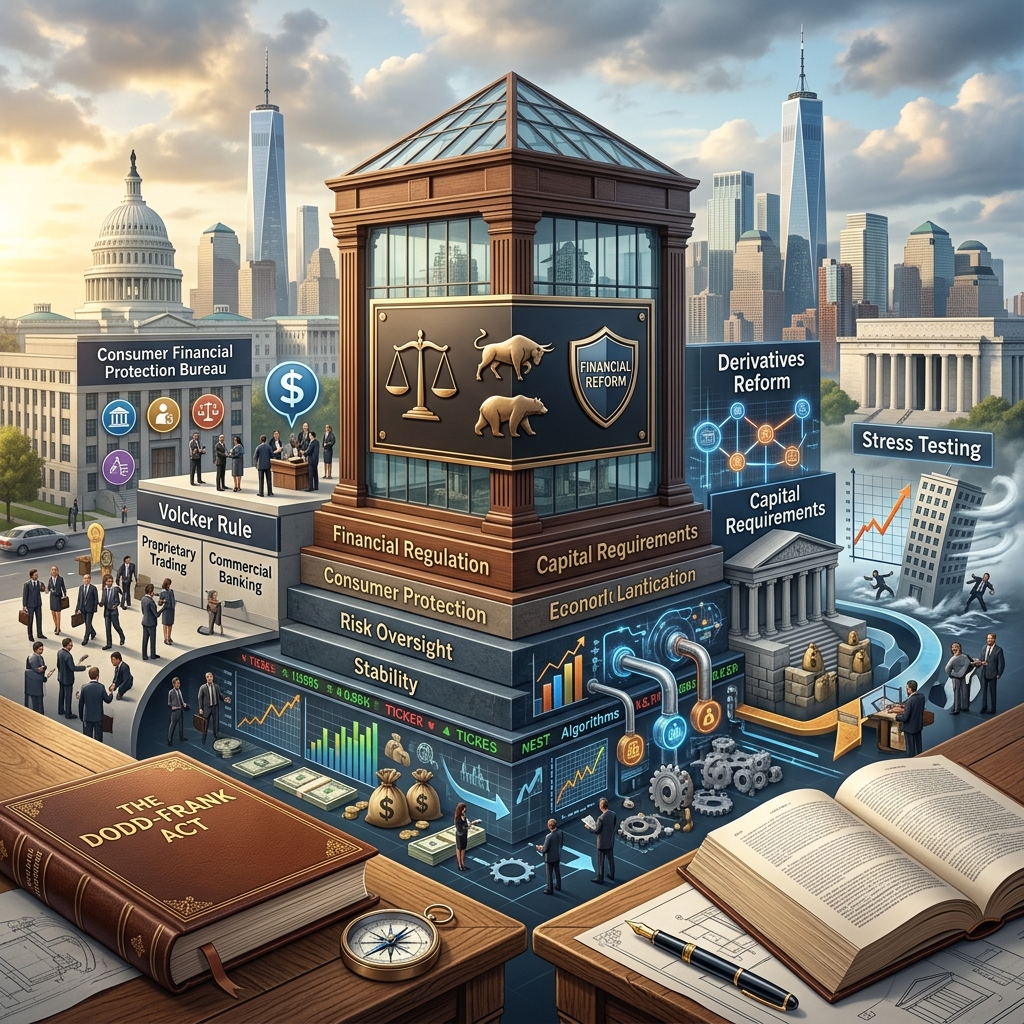
The Dodd-Frank Wall Street Reform and Consumer Protection Act is one of the most far‑reaching financial laws in U.S. history, passed in 2010 in direct response to the 2007–2009 financial crisis. Its goal was to reduce the chances of another systemic meltdown, end taxpayer‑funded bailouts, and strengthen protections for ordinary consumers in the financial marketplace.
This guide explains, in clear language, why the law was enacted, how it changed the rules for banks and financial firms, what new watchdog agencies it created, and what it means for investors, borrowers, and taxpayers today.
Why Dodd-Frank Was Enacted
To understand Dodd-Frank, it helps to look at the crisis that came before it. In 2008, the collapse of large financial institutions, fueled by risky mortgage lending and complex securities, triggered a global recession and forced massive government bailouts. Lawmakers concluded that existing rules did not adequately control risk or protect the public.
Congress enacted Dodd-Frank with a broad mission: to promote financial stability, improve transparency, end “too big to fail,” protect taxpayers from future bailouts, and protect consumers from abusive financial practices. The law attempted to address every major weak spot revealed by the crisis—from bank capital levels to derivatives trading to mortgage lending standards.
- Systemic risk control: Reduce the danger that the failure of one key firm could destabilize the entire financial system.
- Ending bailouts: Create mechanisms so that shareholders and creditors, not taxpayers, bear losses when large firms fail.
- Consumer protection: Establish an independent agency focused solely on fairness and transparency in consumer financial products.
- Market oversight: Bring previously lightly regulated activities, such as over‑the‑counter derivatives, under stricter supervision.
Core Themes of the Dodd-Frank Act
Although the statute spans hundreds of sections, its reforms cluster around a few core themes.
1. Watching the Whole Financial System
Before the crisis, regulators tended to supervise individual firms or markets without a coordinated view of overall systemic risk. Dodd-Frank responded by creating a high‑level council of regulators, the Financial Stability Oversight Council (FSOC), charge with spotting and responding to emerging threats to financial stability.
- FSOC membership includes leaders of the Federal Reserve, Treasury, and other key financial agencies.
- FSOC powers include designating large non‑bank institutions as systemically important, which subjects them to tougher supervision.
- System‑wide perspective aims to prevent blind spots where risky activities migrate outside traditional banking.
2. Making Big Institutions More Resilient
Dodd-Frank imposes enhanced prudential standards on large, complex financial firms considered critical to system stability. These standards go beyond normal bank rules and are designed to ensure big institutions can survive severe economic shocks.
- Stricter capital and liquidity requirements: Large bank holding companies must hold more loss‑absorbing capital and maintain stronger liquidity buffers.
- Leverage limits: Caps on borrowing relative to capital reduce the chance that a downturn turns into insolvency.
- Stress tests: Firms exceeding certain asset thresholds undergo annual stress tests run by the Federal Reserve to assess how they would fare in severe recession scenarios.
- Living wills: Systemically important institutions must prepare resolution plans describing how they could be wound down safely if they fail.
3. Resolving Failing Giants Without Bailouts
One central aim of Dodd-Frank is to avoid a choice between chaos and taxpayer bailouts when a large financial firm is on the brink of failure. The law created an Orderly Liquidation Authority (OLA) that allows the federal government to take over and wind down a failing firm in a controlled manner.
Under this framework, losses are borne by shareholders and creditors, and a special assessment can be imposed on the industry rather than on taxpayers. The idea is to preserve market discipline while preventing domino effects that could destabilize the financial system.
4. The Volcker Rule and Risky Trading
Another widely discussed part of Dodd-Frank is the Volcker Rule, named after former Federal Reserve Chair Paul Volcker. It restricts banks from engaging in proprietary trading—using their own capital to trade securities for profit, rather than to serve customers.
- The rule aims to separate high‑risk trading activity from core banking functions that rely on insured deposits.
- Banks can still conduct market‑making and hedging to manage customer needs and risk, but face limits on speculative positions.
- Compliance involves detailed internal controls and metrics to demonstrate that activities fit within permitted categories.
5. Reforming Derivatives Markets
Complex derivative contracts played a major role in spreading and amplifying risk during the crisis. Dodd-Frank overhauled these markets by requiring more transactions to be conducted through regulated clearinghouses and traded on organized platforms.
Key elements include:
- Central clearing: Many over‑the‑counter derivatives must now be cleared through central counterparties (CCPs), which manage default risk and impose margin requirements.
- Trade reporting: Enhanced reporting obligations make prices and exposures more transparent to regulators and market participants.
- Regulatory oversight: Derivatives dealers and major participants fall under stricter registration and conduct standards.
New Agencies and Oversight Bodies
Dodd-Frank did more than change rules; it reshaped the institutional landscape by creating new agencies and reallocating powers among existing regulators.
| Entity | Main Role Under Dodd-Frank |
|---|---|
| Financial Stability Oversight Council (FSOC) | Coordinates among regulators to identify and respond to systemic risks across the financial system. |
| Consumer Financial Protection Bureau (CFPB) | Acts as an independent watchdog for consumer financial products such as mortgages, credit cards, and student loans. |
| Orderly Liquidation Authority (OLA) | Provides a structured process to resolve failing systemically important institutions without taxpayer bailouts. |
Consumer Financial Protection Bureau (CFPB)
Perhaps the most visible creation of Dodd-Frank for everyday people is the CFPB, an independent bureau dedicated to consumer financial protection. The CFPB consolidates authorities previously scattered across several agencies and focuses on making financial products fair, transparent, and competitive.
Its responsibilities include:
- Rulemaking for consumer financial laws covering mortgages, credit cards, auto loans, payday loans, and more.
- Supervision of large banks and non‑bank financial firms, such as mortgage servicers and certain lenders, for compliance with consumer protection rules.
- Enforcement actions against companies that engage in deceptive, unfair, or abusive practices.
- Consumer education through tools, guides, and complaint handling to help people navigate financial decisions.
How Dodd-Frank Changes Everyday Financial Products
While much of Dodd-Frank concerns large institutions and markets, it also directly affects common consumer products.
Mortgages and Home Loans
The law tightened mortgage lending standards to reduce predatory practices and unsafe loans. Rules require clearer disclosure of terms, verification of borrowers’ ability to repay, and restrictions on certain fee structures.
- Lenders must assess a borrower’s income, assets, and obligations before approving a mortgage.
- Complex or poorly explained loan features, such as teaser rates that spike later, face closer scrutiny.
- Borrowers gain stronger protections against certain types of foreclosure if standards were not followed.
Credit Cards and Consumer Loans
Dodd-Frank supports clearer disclosures, restrictions on surprise fees, and more consistent treatment of consumers across financial products. The CFPB plays a central role in monitoring these markets and acting on consumer complaints.
Impact on Investors and Financial Markets
Investors are affected by Dodd-Frank through changes in market structure, corporate governance, and information availability.
- Enhanced disclosures: Certain provisions increase transparency around complex products and corporate practices.
- Risk management: Clearing and margin rules for derivatives reduce counterparty risk but may increase transaction costs.
- Shareholder rights: The act bolstered some shareholder oversight tools, such as input into executive compensation policies.
Criticisms and Ongoing Evolution
While Dodd-Frank was heralded by its supporters as a safeguard against future crises, it has faced criticism from multiple directions.
- Some argue the law is too complex, with hundreds of rulemakings that impose heavy compliance burdens, especially on smaller banks.
- Others contend it did not go far enough to reduce the size and interconnectedness of major institutions.
- Debates continue over whether certain rules, such as the Volcker Rule, may limit useful market activity alongside speculative behavior.
In 2018, Congress and the executive branch rolled back some provisions, especially those affecting midsize banks, on the grounds that the original thresholds and requirements were overly strict for such institutions. However, the core framework for systemic risk oversight, consumer protection, and resolution planning remains in place.
Quick Reference: Major Components of Dodd-Frank
- Title I: Establishes FSOC and enhanced prudential standards for large institutions.
- Title II: Creates the Orderly Liquidation Authority for resolving failing firms.
- Title VII: Overhauls derivatives markets with clearing and reporting requirements.
- Title X: Establishes the Consumer Financial Protection Bureau.
FAQs About the Dodd-Frank Act
What is the main purpose of the Dodd-Frank Act?
The primary purpose is to promote financial stability by enhancing accountability and transparency, ending “too big to fail,” protecting taxpayers from bailouts, and safeguarding consumers from abusive financial practices.
Who does Dodd-Frank apply to?
Dodd-Frank applies to a wide range of financial actors, including large bank holding companies, certain non‑bank financial firms deemed systemically important, derivatives dealers and major participants, mortgage lenders and servicers, and many consumer‑facing financial institutions.
How did Dodd-Frank change oversight of big banks?
Big banks now face stronger capital, liquidity, and leverage requirements, annual stress tests, and resolution planning obligations. They are also subject to potential restrictions on activities like proprietary trading and involvement in certain funds.
What is the role of the CFPB under Dodd-Frank?
The CFPB sets and enforces rules for consumer financial products, supervises large institutions for compliance, brings enforcement actions against unfair or deceptive practices, and provides education and tools to help consumers make informed choices.
Has Dodd-Frank been changed since it was enacted?
Yes. Subsequent legislation and regulatory actions have modified parts of the act, particularly thresholds and requirements for small and midsize banks. However, the fundamental architecture—systemic risk oversight, resolution authority, and consumer protection—remains central to U.S. financial regulation.
References
- An Overview of the Dodd-Frank Act and its Evolution — Georgetown University FinPolicy. 2025-07-01. https://finpolicy.georgetown.edu/wp-content/uploads/2025/07/Dodd-Frank.docx.pdf
- What Is the Dodd-Frank Act? — Council on Foreign Relations. 2023-03-28. https://www.cfr.org/backgrounders/what-dodd-frank-act
- Wall Street Reform: The Dodd-Frank Act — The White House (Obama Archives). 2016-01-15. https://obamawhitehouse.archives.gov/economy/middle-class/dodd-frank-wall-street-reform
- Fifteen Years of Dodd-Frank: A Legacy of Missed Targets and Unfulfilled Promises — Cato Institute. 2025-07-21. https://www.cato.org/blog/dodd-franks-15th-anniversary-not-much-celebrate
- The Dodd-Frank Wall Street Reform and Consumer Protection Act — Congressional Research Service. 2010-07-28. https://www.congress.gov/crs-product/R41350
Similar Articles








Read full bio of Sneha Tete




