
Understanding the Automatic Stay in Bankruptcy
How the automatic stay freezes most collection actions and gives debtors crucial breathing room during bankruptcy.
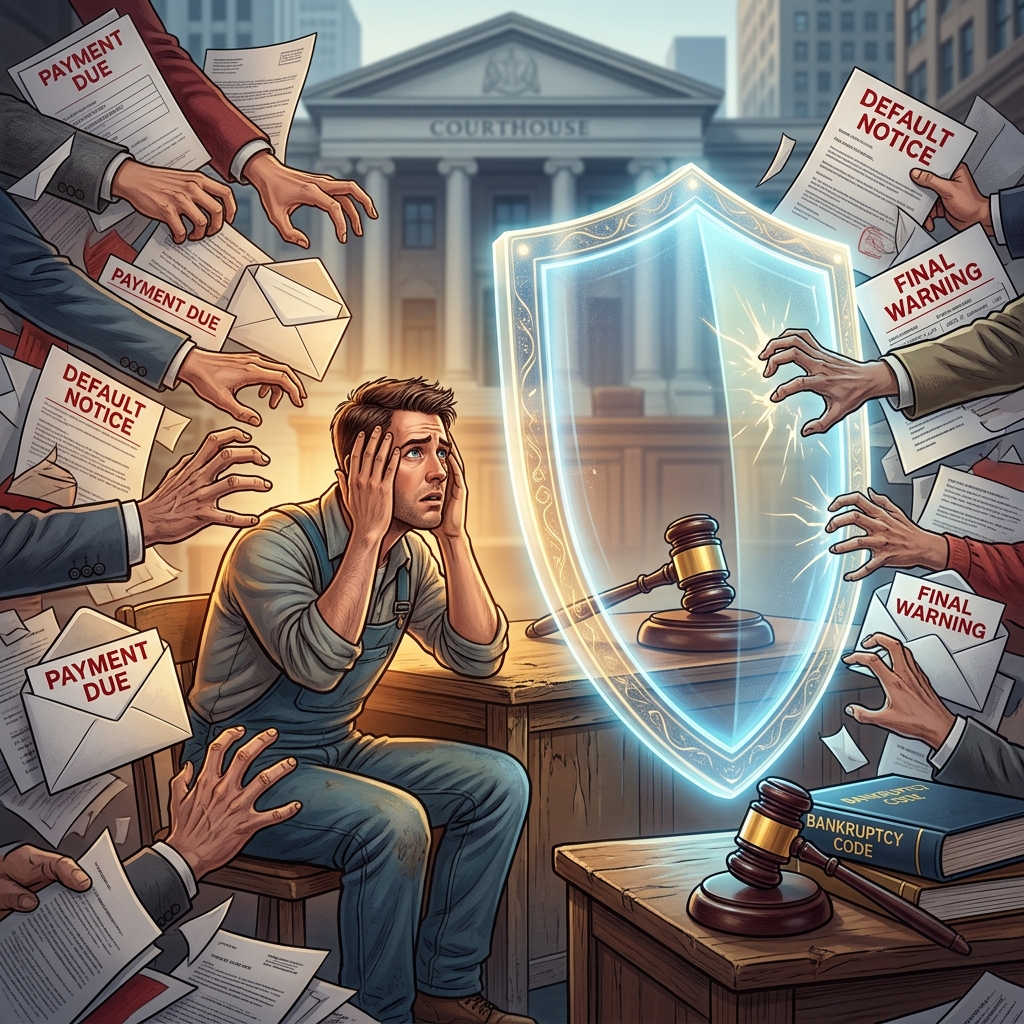
When an individual or business files for bankruptcy in the United States, one of the most powerful protections they receive is the automatic stay. This legal mechanism instantly pauses most collection efforts and court actions, giving the debtor time and space to reorganize finances or liquidate assets under court supervision.
The automatic stay is created by federal law, primarily in 11 U.S.C. § 362, and applies in nearly every chapter of bankruptcy, including Chapter 7, 11, 13, and 9 cases. Understanding how it works, what it covers, and where it does not apply is crucial for both debtors and creditors.
What Is the Automatic Stay?
At its core, the automatic stay is a court-ordered injunction that arises the moment a bankruptcy petition is filed. It operates without any additional motions or hearings: once the petition is accepted, the stay is in place.
In practical terms, the automatic stay:
- Temporarily stops most efforts to collect pre-bankruptcy debts.
- Prevents creditors from starting or continuing lawsuits based on pre-petition obligations.
- Restricts foreclosure, repossession, and lien enforcement activities against the debtor and the debtor’s property.
- Provides a “breathing spell” so the debtor can work within the bankruptcy process without constant collection pressure.
Courts and lawmakers view the stay as a fundamental debtor protection, essential to the goal of a fresh start and the fair treatment of all creditors.
Why the Automatic Stay Exists
The automatic stay serves both debtor and creditor interests by centralizing and controlling the collection process. Instead of a “race to the courthouse” where aggressive creditors grab assets first, the stay pauses everything so the bankruptcy court can supervise an orderly distribution.
Policy goals behind the automatic stay include:
- Protecting the debtor from immediate financial and legal crises, such as garnishments, foreclosures, and repossessions.
- Ensuring equal treatment of creditors by preventing some from obtaining advantages through fast legal action.
- Preserving the bankruptcy estate so assets are available for distribution according to bankruptcy priorities, not state collection rules.
- Facilitating reorganization by stabilizing the situation and allowing the debtor to propose repayment or restructuring plans.
Legal dictionaries often describe the stay as a bar to all judicial and non-judicial collection efforts, subject to specific statutory exceptions.
When the Automatic Stay Begins and Ends
The timing of the automatic stay is straightforward at the start but more nuanced as the case proceeds.
Start of the Stay
The stay begins immediately upon the filing of the bankruptcy petition with the court. There is no need for the debtor to notify each creditor or seek an extra court order for the stay to be effective.
Importantly:
- The stay applies even to creditors who have not yet received official notice of the filing.
- Actions taken after the filing date that violate the stay may be void or subject to reversal by the court.
End of the Stay
In a typical case, the stay lasts until one of the following events occurs:
- The bankruptcy case is closed.
- The case is dismissed by the court.
- A discharge of debts is granted or denied.
In addition, creditors can ask the court to lift or modify the stay before these events (discussed further below).
What the Automatic Stay Typically Stops
The automatic stay is broad. It applies to virtually all entities—not only the parties directly involved in the bankruptcy—and protects both the debtor and the debtor’s property.sup>
Common types of actions that are paused include:
- New lawsuits based on pre-bankruptcy debts.
- Continuation of existing collection lawsuits, including trials and judgments.
- Enforcement of judgments, such as levies, garnishments, and attachments.
- Foreclosure proceedings on the debtor’s home or other real estate.
- Repossession of vehicles or other secured property.
- Actions to create, perfect, or enforce liens against the debtor’s property.
- Efforts to collect pre-petition debts by phone calls, letters, or other direct contact with the debtor.
In Chapter 9 municipal bankruptcies, the stay also protects certain officers and residents of the municipality in specified circumstances, to prevent indirect pressure on the debtor entity.
Key Limits and Statutory Exceptions
Despite its breadth, the automatic stay is not absolute. Federal law carves out specific exceptions for certain types of actions where public policy favors continuation even during bankruptcy.
Examples of common limits and exceptions include:
- Criminal proceedings against the debtor, which are generally not stayed.
- Certain family law matters, such as establishing or modifying child support or alimony, though collection methods may be affected.
- Some tax-related actions, like audits or assessments, while actual collection methods may still be restricted.
- In municipal bankruptcies, application of pledged special revenues to bond payments may continue despite the stay.
Because the statute contains many detailed exceptions, debtors and creditors often need case-specific analysis from a bankruptcy professional to determine whether a particular action is protected by or excluded from the stay.
How the Automatic Stay Affects Debtors
For debtors, the stay is often the most immediate and tangible benefit of filing for bankruptcy. It does not erase debts by itself, but it changes the short-term landscape dramatically.
Common practical effects for a debtor include:
- Immediate relief from collection contact such as phone calls, letters, and emails demanding payment.
- Temporary halt to foreclosure proceedings, allowing time to explore options like loan modification or Chapter 13 repayment plans.
- Stopped wage garnishments and bank levies arising from pre-bankruptcy judgments.
- Pause in repossession efforts for vehicles and other secured property, at least until the creditor obtains court permission to proceed.
However, the stay does not relieve the debtor of ongoing obligations. For example, if the debtor wishes to keep a home or car, payments usually must continue, and missed payments can give secured creditors grounds to seek relief from the stay.
How the Automatic Stay Affects Creditors
For creditors, the automatic stay represents a significant restriction on normal collection rights. Once the stay is in place, self-help and state-law enforcement mechanisms are largely off the table.
Creditors generally must:
- Cease active collection efforts on pre-petition debts.
- Stop or suspend pending lawsuits and enforcement actions related to those debts.
- Refrain from creating or perfecting new liens against the debtor’s property.
- Channel their claims through the bankruptcy process by filing proofs of claim and participating according to court procedures.
The stay is designed to prevent individual creditors from improving their position at the expense of others, and to ensure that distributions follow bankruptcy priorities rather than the timing of collection efforts.
Relief from the Automatic Stay: Creditor Options
Although the automatic stay is powerful, creditors are not without recourse. Under federal law, creditors can ask the bankruptcy court for relief from the stay, either to continue specific actions or to modify the stay’s scope.
Key points about stay relief include:
- Relief is usually requested through a formal motion filed with the bankruptcy court.
- The creditor must provide notice and an opportunity to be heard to affected parties.
- The court decides based on statutory standards such as “cause” or lack of equity and necessity for reorganization.
| Ground | Typical Creditor Argument |
|---|---|
| Cause, including lack of adequate protection | The collateral (such as a house or vehicle) is declining in value, and the creditor’s interest is not adequately protected by payments or other safeguards. |
| No equity in property | The property is worth less than the secured debt, so there is no value for unsecured creditors or the estate. |
| Property not necessary to effective reorganization | The property is not essential to a feasible reorganization plan that is reasonably in progress. |
If the court grants the motion, the stay may be lifted entirely or modified (for example, to permit foreclosure on a specific property while leaving other protections intact).
Consequences of Violating the Automatic Stay
Violating the automatic stay can be expensive and risky. Creditors who ignore or misunderstand the stay may face sanctions and damages.
Under federal law:
- An individual injured by a willful violation can seek actual damages, attorney’s fees, and, in appropriate cases, punitive damages.
- A violation is generally considered willful if the creditor knew about the bankruptcy and intended the actions that breached the stay; specific intent to violate the law is not required.
- Courts may treat actions taken in violation of the stay as void or voidable and can order reversal of those actions.
Because of these consequences, creditors often adopt cautious policies once a bankruptcy is filed, stopping automated collection and seeking legal advice before acting.
Special Considerations Across Bankruptcy Chapters
While the core rules of the automatic stay are similar across chapters, the practical impact differs depending on whether the debtor is liquidating or reorganizing.
- Chapter 7 (Liquidation) – The stay typically lasts for the duration of the case, often a few months, barring early relief or dismissal. It protects the debtor while non-exempt assets are collected and distributed.
- Chapter 13 (Individual reorganization) – The stay may remain in effect for three to five years while the debtor makes plan payments, though creditors can seek relief if payments falter or collateral is inadequately protected.
- Chapter 9 (Municipal bankruptcy) – The stay extends to certain actions involving municipal officers and residents and is coordinated with special revenue rules.
- Chapter 11 (Business reorganization) – The stay stabilizes operations and prevents piecemeal dismantling while the debtor negotiates a plan with creditors.
Practical Tips for Debtors and Creditors
Because the automatic stay involves detailed statutory provisions and serious consequences, both debtors and creditors benefit from careful, informed action.
For Debtors
- Provide complete and accurate information in the bankruptcy petition to ensure the stay applies correctly and creditors receive notice.
- Continue paying secured debts if you intend to keep the collateral, and discuss options with counsel if payments are not feasible.
- Document any collection efforts that continue after filing and consult an attorney about potential stay violations.
- Understand that the stay is temporary and part of a larger process; it does not by itself discharge or reduce debts.
For Creditors
- Immediately pause collection activities once you receive notice—or learn informally—of a bankruptcy filing involving your debtor.
- Review the specific chapter and circumstances to determine whether your claim is secured, priority, or general unsecured.
- File a proof of claim if required and follow court deadlines.
- Consider a motion for relief from the stay if your collateral is depreciating or if the debtor is not making required payments.
- Seek legal advice before taking any action that could be viewed as collection activity during the stay period.
Frequently Asked Questions (FAQs)
Does the automatic stay stop all creditor actions?
No. The stay is broad but not universal. It halts most collection efforts and judicial proceedings on pre-bankruptcy debts, but there are statutory exceptions, such as certain criminal and family law matters, and specific rules for tax and municipal revenue actions.
Do creditors need to be formally notified before the stay applies?
No. The stay takes effect automatically when the petition is filed, whether or not creditors have received official notice. However, notice is critical for practical compliance, and creditors who act after learning of the filing risk penalties for willful violations.
How long does the automatic stay usually last?
In general, the stay remains in place until the case is closed, dismissed, or a discharge is granted or denied. In Chapter 7, this may be a matter of months, while in Chapter 13 the stay can continue for several years, subject to motions for relief.
Can a creditor ever ignore the automatic stay?
Creditors must not ignore the stay. If they believe an exception applies or that they are entitled to proceed, they should seek guidance from counsel and, where appropriate, file a motion for relief with the bankruptcy court rather than acting unilaterally.
What should a debtor do if a creditor violates the stay?
Debtors should keep records of all communications and actions that appear to violate the stay and promptly inform their bankruptcy attorney. In some cases, the court can award damages, attorney’s fees, and other relief for willful violations.
References
- 11 U.S. Code § 362 – Automatic stay — Legal Information Institute, Cornell Law School. Accessed 2024-04-01. https://www.law.cornell.edu/uscode/text/11/362
- What is the automatic stay? — U.S. Bankruptcy Court, District of Minnesota. Accessed 2024-04-01. https://www.mnb.uscourts.gov/content/what-automatic-stay
- Automatic Stay, What Is It And Does It Protect A Debtor From All Creditors? — U.S. Bankruptcy Court, Central District of California. Accessed 2024-04-01. https://www.cacb.uscourts.gov/faq/automatic-stay-what-it-and-does-it-protect-debtor-all-creditors
- Bankruptcy and the Automatic Stay: What Every Lawyer Should Know — Oklahoma Bar Association Bar Journal. 2023-12. https://www.okbar.org/barjournal/december-2023/bankruptcy-and-the-automatic-stay/
- Stay Away From the Debtor? An Overview of the Automatic Stay in Bankruptcy — Barclay Damon LLP. 2021-03-22. https://www.barclaydamon.com/alerts/stay-away-from-the-debtor-an-overview-of-the-automatic-stay-in-bankruptcy
- Bankruptcy: Automatic Stays Research Guide — Tarrant County Law Library. 2020. https://www.tarrantcountytx.gov/content/dam/main/law-library/pdfs/research-guides/Bankruptcy_Automatic_Stays_Research_Guide.pdf
- Automatic Stay Bankruptcy: What is it & What Does it Do? — Debt.org. Updated 2023. https://www.debt.org/bankruptcy/automatic-stay/
Similar Articles








Read full bio of medha deb




