
Understanding Credit: A Practical Guide to Building Strong Financial Foundations
Learn how credit works, why it matters, and the key strategies to build, protect, and improve your credit health over time.
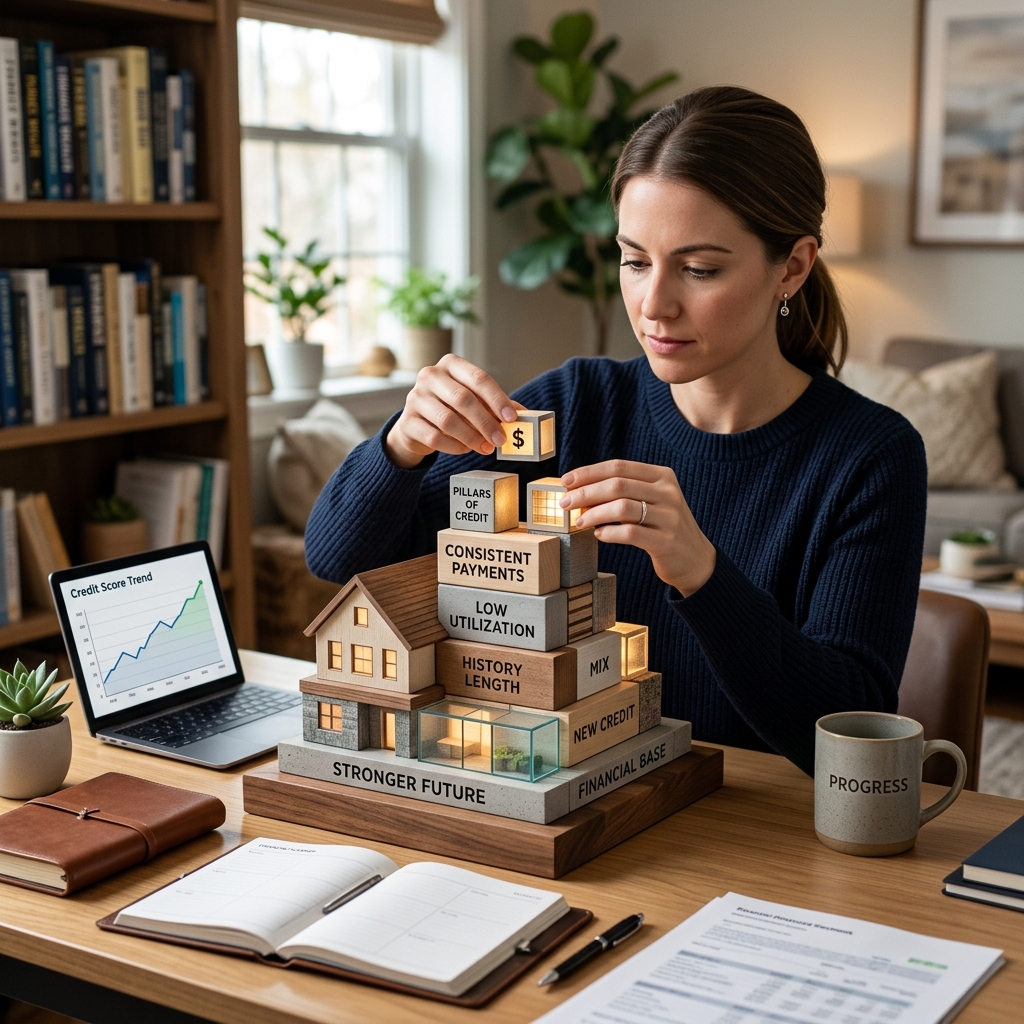
Credit touches nearly every part of modern financial life. It influences whether you can buy a home, finance a car, qualify for a credit card, and sometimes even get a job or rent an apartment. Yet many people use credit before fully understanding how it works. This guide breaks down the essentials so you can use credit as a tool, not a trap.
What Credit Really Means
At its core, credit is the ability to receive money, goods, or services now and pay for them later under agreed terms. When a lender, landlord, or company extends credit to you, they are trusting you to repay what you owe on time, typically with interest or fees.
When people talk about “your credit,” they often mean your credit history — a record of how you have used borrowed money and whether you paid it back as agreed.
Why Credit Matters
- Loan approval: Lenders use your credit to decide if they will approve mortgages, auto loans, student loans, and personal loans.
- Interest rates and terms: Better credit usually leads to lower interest rates and more favorable loan conditions.
- Housing and utilities: Landlords and utility companies may review your credit to evaluate payment reliability.
- Employment and insurance: Some employers and insurers consider credit information when assessing risk and responsibility.
In short, strong credit can save you significant money over time and open doors to more opportunities, while poor credit can make borrowing more expensive or even impossible.
Types of Credit You May Use
Not all credit works the same. Understanding the main types helps you choose and manage them more effectively.
Revolving Credit
Revolving credit allows you to borrow up to a certain limit, repay some or all of what you owe, and then borrow again without reapplying for a new account. Credit cards are the most common example.
- You have a credit limit set by the issuer.
- You can carry a balance from month to month.
- You are required to pay at least a minimum amount by the due date.
- Interest is charged on any unpaid balance, often at relatively high rates.
Installment Credit
Installment loans provide a lump sum of money that you repay in fixed amounts over a set period. Common examples include:
- Auto loans
- Personal loans
- Mortgages
With installment credit, you typically know exactly how much you will pay each month and for how long, making it easier to plan your budget.
Comparing Revolving and Installment Credit
| Feature | Revolving Credit | Installment Credit |
|---|---|---|
| Access to funds | Repeated borrowing up to a limit | Single lump sum at the start |
| Payment structure | Variable; minimum payment required | Fixed monthly payments |
| Interest rate | Often higher, especially on credit cards | Usually lower and fixed or predictably variable |
| Impact on credit utilization | Directly affects utilization ratio | Less direct impact on utilization |
Credit Reports: Your Financial Track Record
Your credit report is a detailed summary of your credit history compiled by nationwide credit bureaus such as Equifax, Experian, and TransUnion.
What a Credit Report Contains
- Personal identification information (name, address, Social Security number)
- Details of credit accounts (type, limit or loan amount, balance, payment history)
- Collection accounts and public records related to debt (such as certain judgments or bankruptcies, where permitted by law)
- Records of companies that have requested your report (credit inquiries)
Lenders rely on this report to evaluate your past behavior with borrowed money and to judge future risk.
Checking Your Credit Report
Reviewing your credit report regularly helps you spot errors, understand what lenders see, and detect signs of identity theft early.
- Confirm that all accounts listed belong to you.
- Check for incorrect balances, payment statuses, or limits.
- Look for unfamiliar inquiries or accounts that may signal fraud.
Credit Scores: Turning Your History into a Number
A credit score is a three-digit number, generally ranging from 300 to 850, that reflects how likely you are to repay a loan on time based on your credit report. Higher scores signal lower risk to lenders, while lower scores indicate higher risk.
What Credit Scores Measure
Credit scoring models, such as FICO and others, analyze data from your credit report to estimate the probability you will miss payments or default on a debt. Many models focus on the likelihood that you might be at least 90 days late on a payment within the next two years.
Key Factors That Influence Your Score
While exact formulas are proprietary, widely used scores tend to weigh certain factors more heavily:
- Payment history: Whether you pay bills on time is typically the most important factor, accounting for around 35% of a FICO® Score.
- Credit utilization: The percentage of revolving credit you are using versus your total limits can represent about 30% of your score.
- Length of credit history: How long your accounts have been open and your average account age.
- Types of credit: A mix of installment and revolving accounts can be viewed favorably when managed well.
- Recent credit inquiries and new accounts: Frequent applications or many new accounts in a short time can lower your score temporarily.
Understanding Credit Utilization
Your credit utilization ratio compares the amount of credit you are using to the total revolving credit available to you. For example, if your total credit card limits are $10,000 and your total balances are $2,000, your utilization is 20%.
Many experts recommend keeping utilization below about 30%, and lower is generally better, because high utilization can make you appear more financially stretched.
Creditworthiness: How Lenders See You
Creditworthiness is a lender’s overall assessment of your ability and willingness to repay borrowed money. It includes your credit score and report, but may also factor in your income, employment history, and debt-to-income ratio.
Important Elements of Creditworthiness
- Payment reliability: Consistent on-time payments show you are dependable.
- Debt-to-income ratio: The share of your monthly income that goes toward debt payments helps lenders judge whether additional debt is manageable.
- Length and stability of history: Long-standing accounts and steady employment can strengthen your profile.
- Account mix and usage: Responsible use of different types of credit indicates experience managing debt.
Debt-to-Income Ratio Explained
Your debt-to-income (DTI) ratio is calculated by dividing your total monthly debt payments by your gross monthly income. Lenders use this measure to estimate how much additional debt you can reasonably handle.
Lower DTI ratios generally make it easier to qualify for new loans and credit lines, while high ratios suggest that your budget may already be stretched.
Building Credit from the Ground Up
If you are new to credit or rebuilding after past difficulties, there are practical steps you can take to develop a positive credit history over time.
Foundational Steps
- Start with responsible accounts: Consider secured credit cards or small installment loans you can comfortably afford, ensuring they report to major credit bureaus.
- Always pay on time: On-time payments are one of the most powerful ways to demonstrate reliability and improve scores.
- Keep balances modest: Avoid maxing out cards and aim for a low utilization percentage.
- Track your obligations: Use calendar reminders, budgeting tools, or auto-pay to avoid missed due dates.
Healthy Habits for Strong Credit
- Review credit reports regularly to catch errors and fraud.
- Limit the number of new credit applications in a short period.
- Maintain older accounts where possible to preserve length of history.
- Use credit primarily for planned expenses you can repay, not for everyday overspending.
Managing and Reducing Debt
Good credit is not just about having access to borrowing; it is also about keeping debt at levels you can comfortably manage.
Organizing What You Owe
Start by listing all your debts so you have a clear picture of your situation.
- Name of each lender or credit card issuer
- Current balance
- Interest rate
- Minimum payment amount
- Monthly due date
Compare this information with your monthly income and essential expenses to determine how much you can pay above the minimums on higher-interest debts.
Strategies to Pay Down Debt
- Target high-interest accounts: Paying extra toward debts with the highest rates can reduce overall interest costs.
- Maintain minimums on all accounts: Avoid missed payments and late fees while focusing extra funds strategically.
- Consider consolidation carefully: Combining debts into a single loan can simplify payments if terms are favorable and you avoid taking on new debt.
- Commit to a fixed monthly payoff amount: Treat debt reduction like a required bill in your budget.
Protecting Your Credit and Identity
Protecting your credit is just as important as building it. Fraud and identity theft can damage your credit history and scores if not addressed quickly.
Monitoring and Security Measures
- Regular monitoring: Check your credit reports to spot unauthorized accounts or suspicious activity.
- Fraud alerts and freezes: After identity theft or a data breach, you can place alerts or freezes to make it harder for others to open new accounts in your name.
- Credit freeze basics: A freeze restricts new credit checks, making it difficult for someone else to open accounts using your information; you must contact each major bureau to place or lift a freeze.
Everyday Practices to Safeguard Credit
- Use strong, unique passwords for banking and credit accounts.
- Shred or securely dispose of documents that contain sensitive information.
- Be cautious about sharing personal data online or by phone.
- Respond promptly to notices of suspicious activity from lenders or credit bureaus.
Frequently Asked Questions About Credit
Does checking my own credit hurt my score?
No. When you check your own credit report or score, it is considered a soft inquiry and does not affect your credit score. Only certain types of lender-initiated “hard” inquiries may impact your score.
How long does negative information stay on my credit report?
Negative items such as late payments or collection accounts typically remain on your credit report for several years, although specific time frames depend on the type of information and applicable law. Their impact on your score tends to lessen over time, especially as you establish a recent pattern of responsible behavior.
Is closing old credit cards always a good idea?
Not necessarily. Closing an old card can reduce your available credit and shorten your average account age, which may negatively affect your credit utilization and score. If the card has no annual fee and you can avoid misuse, keeping it open may be more beneficial.
Can I build credit without a credit card?
Yes. Installment loans such as auto loans, student loans, or personal loans can also help you build credit if they are reported to the bureaus and you make payments on time. Some people use small, manageable loans or credit-builder products specifically designed to help establish a credit history.
What is considered a “good” credit score?
Score ranges vary by model and lender, but generally, higher scores (closer to 850) indicate lower risk. Many lenders view scores in the mid- to high-600s and above as more favorable, while very high scores can qualify you for the best available rates. Remember, however, that each lender sets its own criteria.
References
- Understanding Your Credit — Federal Trade Commission (FTC). 2023-05-10. https://consumer.ftc.gov/articles/understanding-your-credit
- Money Basics: Guide to Building and Maintaining Credit — National Credit Union Administration (NCUA). 2022-08-01. https://mycreditunion.gov/brochure-publications/brochure/money-basics-guide-building-and-maintaining-credit
- Credit Score Basics: What Impacts Your Score and Why It Matters — Experian. 2023-09-12. https://www.experian.com/blogs/ask-experian/credit-education/score-basics/
- What Is Creditworthiness and How Can I Build Credit? — TD Bank. 2023-04-06. https://www.td.com/us/en/personal-banking/learning/borrowing-credit/understanding-the-basics-credit-creditworthiness
- Understanding Credit — Institute of Gerontology, Wayne State University. 2017-01-01. https://iog.wayne.edu/outreach/2017_understanding_credit_book.pdf
Similar Articles








Read full bio of medha deb




