
Ulta Beauty Rewards Mastercard: A Practical Guide
Learn how the Ulta Beauty Rewards Mastercard works, its benefits, fees, and risks so you can decide if it fits your spending habits.
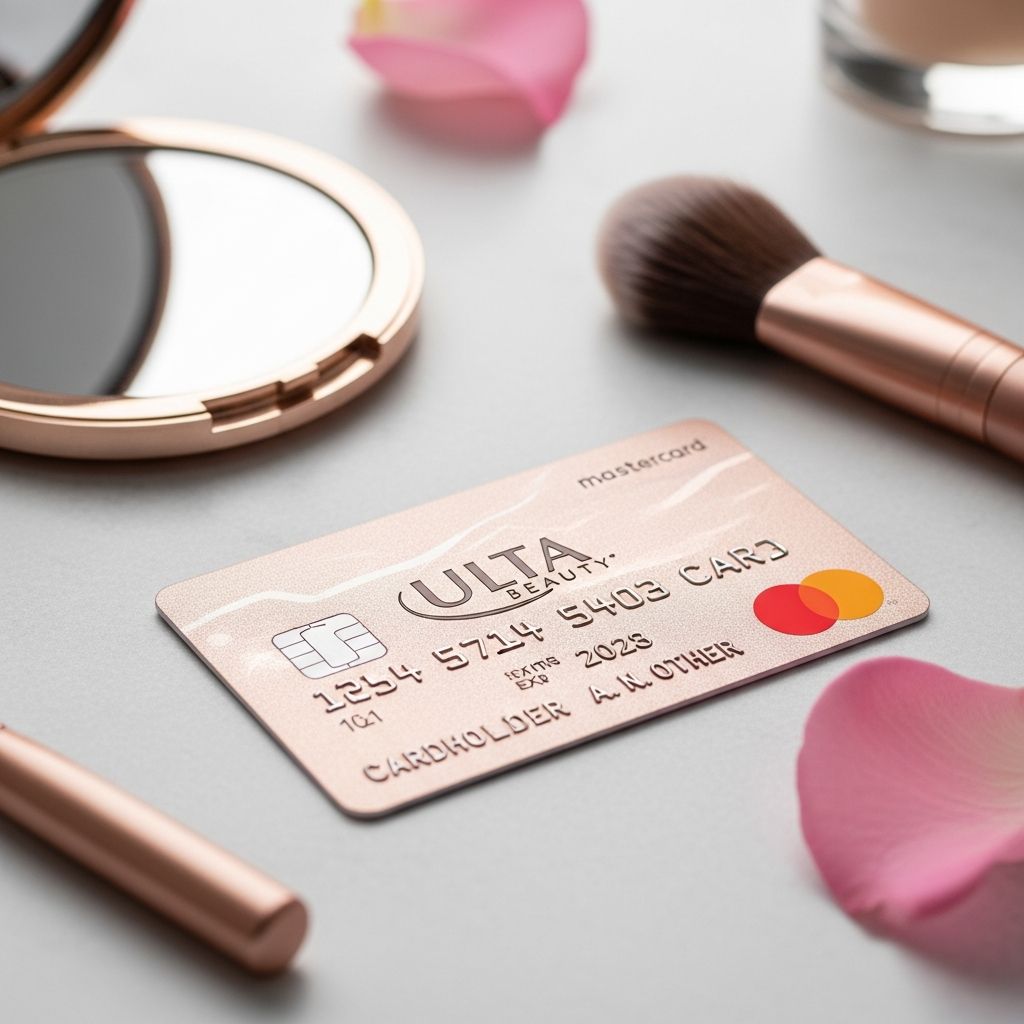
The Ulta Beauty Rewards Mastercard is a co-branded credit card issued by Comenity Capital Bank that lets you earn points on Ulta purchases and everyday spending. It can be rewarding for frequent Ulta customers, but like most store cards, it may carry a relatively high interest rate and other costs you should understand before applying.
How the Ulta Beauty Rewards Mastercard Works
This card is designed to tie your everyday spending to Ulta’s loyalty program. When you use it, you earn store rewards instead of (or in addition to) traditional cash back or travel miles. The card works in two key ways:
- Store card features: Extra points when you shop at Ulta Beauty, in-store or online.
- General-purpose card features: Because it runs on the Mastercard network, you can use it almost anywhere Mastercard is accepted, not just at Ulta.
Although specific reward rates and promotional offers can change over time, the core idea is that purchases translate into points, and points can be turned into Ulta rewards certificates.
Card Basics at a Glance
| Feature | What It Means |
|---|---|
| Issuer | Comenity Capital Bank, which manages many retail and co-branded credit cards. |
| Network | Mastercard – usable at millions of merchants worldwide where Mastercard is accepted. |
| Type | Unsecured revolving credit card with a variable APR based on your credit profile and market rates. |
| Rewards structure | Points on Ulta purchases and points on non-Ulta purchases; points convert into Ulta rewards. |
| Annual fee | Typically no annual fee, but always confirm the fee table in the latest card agreement before applying. |
Before you apply, you should review the current pricing and terms document, which issuers must post and update under federal rules for credit card agreements.
Rewards: How You Earn and Redeem Points
The main appeal of the Ulta Beauty Rewards Mastercard is the ability to earn more Ulta points faster. The exact earning rates can change, but the general pattern looks like this:
- Ulta purchases: You earn Ulta loyalty points for being a rewards member, plus additional points because you pay with the co-branded card.
- Everywhere else: You earn a smaller number of points on non-Ulta purchases, which still count toward Ulta rewards.
- Promotions: Occasionally, Ulta or the issuer may offer limited-time multipliers, such as extra points on specific categories or during special events.
Points typically redeem as Ulta rewards coupons that reduce the cost of future purchases. This means your rewards are effectively store credit rather than cash back to your bank account.
Things to Check in the Official Rewards Terms
Because reward programs can be modified by the issuer with notice, you should carefully read the loyalty program rules before relying on a particular earning rate.
- Minimum number of points required before you can redeem.
- Point expiration rules if your account becomes inactive.
- Whether returns or disputed transactions reduce your points balance.
- Any caps on how many points you can earn in a year.
Interest, Fees, and Other Costs
Store and co-branded retail cards often charge higher interest rates than many general cash-back cards, especially for borrowers with lower credit scores. If you carry a balance, interest can quickly outweigh the dollar value of the rewards you earn.
Key Cost Elements to Understand
- Purchase APR: A variable rate that moves when benchmark interest rates change; it applies to any unpaid balance after the grace period.
- Late payment fee: A fee added if your minimum payment is not received by the due date.
- Returned payment fee: A fee if your payment is declined by your bank.
- Foreign transaction fee: A percentage charge on purchases made in foreign currency or outside the U.S., if applicable.
- Cash advances: Some cards allow cash advances at ATMs, but these often carry a high APR and additional fees and usually do not earn rewards.
Credit card issuers are required under federal truth-in-lending rules to clearly disclose these rates and charges in a standardized format known as the Schumer box. Review this table carefully before you submit an application.
Credit Requirements and Approval Considerations
The Ulta Beauty Rewards Mastercard generally targets consumers with at least fair to good credit, though approval is never guaranteed. The issuer typically looks at factors such as:
- Your credit score and history of on-time payments.
- Your existing debts and credit utilization.
- Your stated income and ability to repay.
Applying for this card will usually generate a hard inquiry on your credit report, which can cause a small, temporary drop in your score. If your application is approved, opening a new account will also affect your overall available credit and utilization rate, both of which factor into common credit-scoring models.
Is the Ulta Beauty Rewards Mastercard Right for You?
Whether this card is a good fit depends mostly on how often you shop at Ulta and whether you tend to carry a balance on your credit cards.
Who Might Benefit Most
- Shoppers who make frequent Ulta purchases throughout the year.
- Cardholders who pay their statement balance in full most months, minimizing interest charges.
- Consumers who prefer rewards in the form of discounted beauty products rather than flexible cash back.
Who Should Be Cautious
- People who regularly carry balances and are paying interest on multiple cards.
- Anyone close to their credit limits, since a new card may encourage extra spending.
- Shoppers who rarely visit Ulta; in that case, a general rewards card may provide more useful benefits.
Using the Card Responsibly
To get value from any rewards card, including the Ulta Beauty Rewards Mastercard, you should prioritize responsible credit management. Research on consumer credit behavior shows that understanding card terms and tracking balances can significantly reduce the risk of problem debt.
Best Practices for Cardholders
- Pay on time, every time: Set up automatic payments for at least the minimum due, and ideally for the full statement balance.
- Keep utilization low: Consider keeping your balance below about 30% of your credit limit to support a healthier credit profile.
- Track rewards and expiration dates: Log in periodically to verify your points balance and any upcoming expirations so you do not lose rewards.
- Review statements: Check each statement for unauthorized charges and errors; federal law limits your liability for fraudulent credit card use if you report it promptly.
Online Account Management and Security
Once approved, you will typically be able to manage the Ulta Beauty Rewards Mastercard through an online portal or mobile app operated by the issuer. From there you can check balances, make payments, and review rewards.
Because credit cards involve sensitive personal and financial data, issuers must follow security standards and consumers should adopt safe habits. The Payment Card Industry Data Security Standard (PCI DSS) provides technical and operational requirements for organizations that store or process cardholder data. Consumers can enhance their own security by:
- Avoiding public Wi-Fi for account logins.
- Using strong, unique passwords and enabling multifactor authentication where available.
- Never sending full card numbers by email or text.
- Promptly reporting any suspicious activity on their accounts.
Comparing Store Cards to Other Credit Card Options
Before choosing a specialty card, you may want to compare it with general-purpose rewards cards, cash-back cards, or low-APR cards offered by major banks and credit unions. Many independent credit card comparison sites use strict editorial standards to evaluate features objectively and help consumers understand trade-offs between rewards and costs.
| Card Type | Potential Advantages | Potential Drawbacks |
|---|---|---|
| Store Co-Branded Card (like Ulta Mastercard) |
|
|
| General Cash-Back Card |
|
|
| Low-Interest or 0% Intro APR Card |
|
|
How to Apply and What Happens Next
If you decide to move forward, you can usually apply for the Ulta Beauty Rewards Mastercard online, via mail, or in some cases in an Ulta store. To process your application, the issuer may ask for:
- Your full name and contact information.
- Social Security number or other taxpayer identification number.
- Employment or income details.
After you submit your application:
- You may receive an instant decision or be told that your application needs further review.
- If approved, you will be assigned a credit limit based on your credit history and income.
- You should receive the card by mail along with the full cardmember agreement and disclosure documents.
Under U.S. rules, issuers must make card agreements for open-end consumer credit available online and update them when terms change, which can help you compare products and understand your rights.
Frequently Asked Questions
Does the Ulta Beauty Rewards Mastercard charge an annual fee?
Many store-branded rewards cards do not charge an annual fee, but you should always confirm the current fee schedule in the official pricing disclosures before applying, as terms can change over time.
Can I use the Ulta Beauty Rewards Mastercard anywhere?
Yes. Because it is on the Mastercard network, you can generally use it wherever Mastercard is accepted, not just at Ulta stores. However, you typically earn the highest rewards on Ulta purchases.
Will applying for this card affect my credit score?
Yes. Submitting an application usually leads to a hard credit inquiry, which may temporarily lower your score slightly. Over time, responsible use—such as on-time payments—can help build a stronger credit history.
Do Ulta rewards points expire?
Point expiration policies are governed by the loyalty program rules, which may change. Check the most recent Ulta rewards terms to see if points expire after a period of inactivity or on a fixed schedule.
What should I do if my card is lost or stolen?
You should immediately contact the issuer using the number provided in your account materials or on your statement. Federal law limits consumer liability for unauthorized credit card transactions, particularly when the loss is reported promptly.
References
- Editorial Guidelines — CardRates.com. 2023-05-11. https://www.cardrates.com/editorial-guidelines/
- Editorial Guidelines — CreditCards.com. 2023-04-18. https://www.creditcards.com/editorial-guidelines/
- 12 CFR § 1026.58 – Internet posting of credit card agreements — Consumer Financial Protection Bureau. 2023-01-01. https://www.consumerfinance.gov/rules-policy/regulations/1026/58
- Guide to Securely Storing Credit Card Information — LawPay. 2022-06-15. https://www.lawpay.com/about/blog/storing-credit-card-information/
- Truth in Lending Act (Regulation Z) — Board of Governors of the Federal Reserve System / CFPB. 2023-01-01. https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/truth-lending-act/
Similar Articles








Read full bio of medha deb


