
Smart Strategies To Reduce Your Federal Income Taxes
Discover practical, legal ways to lower your taxable income and keep more of your hard‑earned money every year.
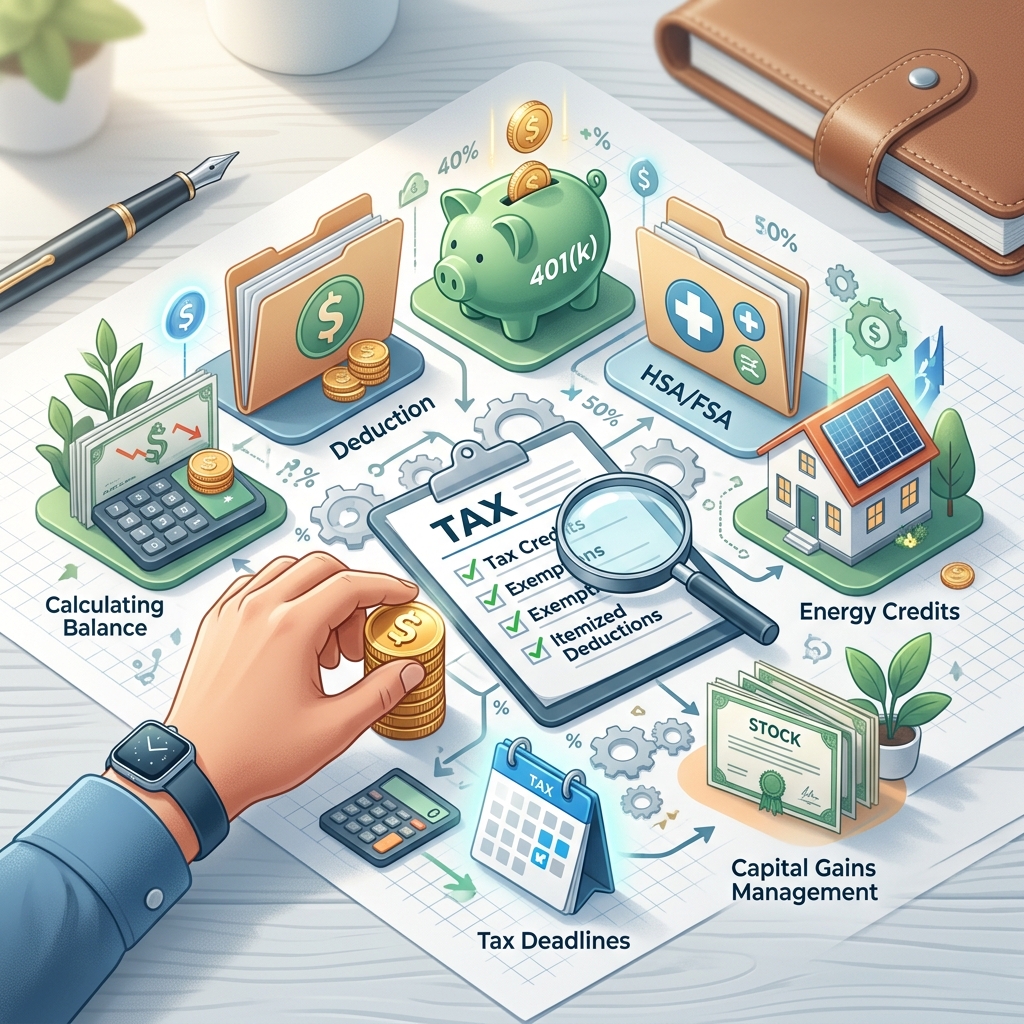
Federal income taxes can feel overwhelming, but with thoughtful planning you can legally reduce your taxable income and potentially lower the amount you owe each year. Tax savings usually come from a combination of deductions, credits, smart timing, and the way you invest and save for the future.
This guide explains key strategies individual taxpayers commonly use to trim their tax bill, using everyday language and practical examples. It is for general information only and is not a substitute for personalized advice from a tax professional or financial advisor.
Understanding The Two Main Paths To Tax Savings
Most tax strategies work through one of two basic mechanisms: reducing taxable income or reducing tax liability directly.
| Approach | How It Works | Common Examples |
|---|---|---|
| Deductions | Lower the income the IRS uses to calculate your tax. | Mortgage interest, state and local taxes (SALT), charitable donations, retirement contributions. |
| Credits | Reduce your tax bill dollar-for-dollar after it is calculated. | Earned income tax credit, child tax credit, American Opportunity credit. |
Effective tax planning usually combines both: you seek deductions that make sense for your situation and also ensure you claim every credit you qualify for.
Year-Round Tax Planning: Why Timing Matters
Many people think about taxes only when returns are due, but the strongest savings often come from decisions made throughout the year, not just at filing time.
- Track income and major expenses monthly so you can estimate your tax bracket and adjust strategies as needed.
- Schedule potential deductions (such as charitable gifts or medical procedures) in a way that groups them into a single year if that helps you exceed the standard deduction and benefit from itemizing.
- Review your withholding and estimated tax payments at least once a year to avoid penalties and large surprises at tax time.
Financial institutions emphasize that proactive, year-round planning is one of the most reliable ways to lower taxes because it gives you time to use all available tools, instead of rushing at the end of the year.
Boost Retirement Contributions To Cut Taxable Income
Contributing to tax-advantaged retirement accounts is one of the most powerful ways to lower taxable income while also saving for the future.
Workplace Retirement Plans
If you have access to a workplace plan such as a 401(k), 403(b), or similar arrangement, contributions to traditional (pre-tax) accounts generally reduce your taxable income for the year. Financial firms note that workers can often contribute tens of thousands of dollars annually, and older workers may be allowed additional “catch-up” contributions.
- Pre-tax contributions lower the income reported on your tax return.
- Employer matches do not reduce your current taxes directly, but add to your retirement savings without extra out-of-pocket cost.
- Automatic increases can help you gradually reach the maximum allowed contribution over time.
Traditional IRAs
Traditional Individual Retirement Accounts (IRAs) also allow many taxpayers to deduct contributions, depending on income level and whether they are covered by a workplace plan. Large financial institutions emphasize that IRA contribution limits change periodically, so you should verify current limits and eligibility before contributing.
By shifting part of your income into pre-tax retirement accounts, you postpone taxes until you withdraw funds, usually in retirement when you may be in a lower tax bracket.
Use Health Accounts To Combine Tax Savings And Medical Planning
Health-related savings arrangements can provide significant tax advantages while helping you cover medical expenses.
Health Savings Accounts (HSAs)
HSAs are available to people enrolled in qualifying high-deductible health plans. These accounts are often described as offering a “triple tax benefit”:
- Tax-deductible contributions: Money you put in usually reduces taxable income.
- Tax-free growth: Investment gains in the account are not taxed while they remain inside.
- Tax-free withdrawals for qualified medical expenses: Distributions used for eligible health costs generally are not taxed.
Major financial firms highlight HSAs as one of the few tools that can lower current taxes, provide long-term investment potential, and fund medical needs.
Flexible Spending Accounts (FSAs)
FSAs, usually offered by employers, allow you to set aside pre-tax dollars for healthcare or dependent care expenses. While unused funds may not roll over fully, using an FSA correctly can reduce taxable wages and cover predictable costs like childcare or routine medical visits.
Make The Most Of Itemized Deductions
Taxpayers can either use the standard deduction or itemize. If your deductible expenses exceed the standard deduction, itemizing may lower your tax bill.
State And Local Tax (SALT) Deduction
Itemizing taxpayers may deduct certain state and local income, sales, and property taxes up to a federal cap. Recent tax law changes in the United States have raised this cap for some years and income ranges, but limits still apply. High-income households or residents of high-tax states should pay particular attention to SALT rules when estimating potential savings.
Mortgage Interest And Home-Related Costs
Interest on a qualifying home mortgage may be deductible when you itemize. In addition, some homeowners with dedicated home offices may be able to deduct a portion of housing costs such as rent, utilities, or insurance when they use part of their home exclusively and regularly for business.
Charitable Contributions
Donations to eligible charities, including cash and the fair market value of goods, can be deductible if you itemize. You may also deduct certain out-of-pocket expenses related to volunteer work, such as mileage driven for charitable purposes.
- Keep detailed records of cash donations, receipts for goods, and mileage logs.
- Consider grouping contributions in a single year to maximize itemized deductions.
Some taxpayers use donor-advised funds to bunch several years of giving into one tax year, potentially increasing their deductions.
Leverage Tax Credits For Direct Reductions In Tax
While deductions reduce the income being taxed, tax credits reduce the tax itself and can yield substantial savings for eligible households.
Financial and banking resources highlight several frequently used credits, including:
- Earned Income Tax Credit (EITC) – Designed for low- to moderate-income workers; eligibility depends on income, filing status, and number of qualifying children.
- Child Tax Credit – Available to many families with qualifying children, with amount and eligibility affected by income and other conditions.
- Education Credits – Such as the American Opportunity Tax Credit or Lifetime Learning Credit, which can help offset the cost of higher education.
- Dependent Care Credit – Helps families cover eligible childcare or dependent care expenses so they can work or look for work.
A critical step in reducing taxes is reviewing IRS guidelines or using reputable tax software to ensure you claim every credit for which you qualify.
Manage Investments With Tax Efficiency In Mind
The way you buy, sell, and hold investments can have a meaningful impact on your tax bill. Large financial institutions frequently recommend incorporating tax-loss harvesting, asset location, and careful timing of capital gains into your strategy.
Tax-Loss Harvesting
Tax-loss harvesting involves selling investments that have declined in value to realize a loss, then using that loss to offset capital gains elsewhere.
- Realized losses can offset realized capital gains.
- If total losses exceed gains, you may be able to offset a limited amount of ordinary income each year and carry forward remaining losses to future years.
- Be mindful of “wash-sale” rules, which limit claiming losses if you repurchase a substantially identical investment within a specific period.
Strategic Capital Gains Realization
In some situations, investors deliberately realize gains during years when they expect to be in a lower tax bracket. Financial advisors sometimes refer to this as tax-gain harvesting, and it can be useful for long-term planning.
Asset Location
Asset location means placing investments in accounts based on their tax characteristics—for example, holding tax-inefficient investments (like high-turnover funds or taxable bonds) inside retirement accounts, and tax-efficient investments (like index funds or municipal bonds) in taxable accounts. Thoughtful asset location can reduce annual taxable income from investments while still supporting long-term goals.
Special Opportunities For Older Taxpayers
Tax rules often provide unique options for older adults, which can further reduce taxes in retirement years.
- Catch-up contributions to certain retirement plans allow older workers to save more on a tax-advantaged basis.
- Additional standard deductions for taxpayers above a certain age can increase the amount of income shielded from tax.
- Qualified charitable distributions (QCDs) from IRAs allow some individuals past a specified age to send money directly from their IRA to a charity. These distributions can satisfy required minimum distributions and are typically excluded from taxable income, offering a distinct tax advantage.
Because rules and dollar limits for these provisions change over time, it is important to consult current IRS publications or trusted financial institutions when planning.
Working With Professionals And Staying Informed
Federal tax law evolves regularly. Changes to deductions, credits, and income thresholds can alter which strategies are most effective in any given year. As a result, it is essential to:
- Review IRS publications annually or use reliable guidance from major financial firms and banks to stay current on rules and limits.
- Consult a tax professional if your situation involves business income, complex investments, real estate, or significant life changes.
- Coordinate tax planning with overall financial planning so that decisions about saving, investing, and giving fit together and support long-term goals, not just short-term tax savings.
Frequently Asked Questions About Lowering Federal Taxes
Do I need to itemize to save on taxes?
No. Some tax benefits, such as certain credits and above-the-line deductions (like some student loan interest deductions), may be available even if you do not itemize. However, if your deductible expenses exceed the standard deduction, itemizing could yield additional savings.
Is it better to reduce taxable income or use credits?
Both approaches can be valuable. Deductions lower the income used for tax calculations, while credits directly reduce the tax owed. For many taxpayers, the most effective strategy is to use all appropriate deductions and then claim every eligible credit.
Can everyday workers benefit from tax-loss harvesting?
Yes, as long as you have taxable investment accounts with realized gains and losses. Financial firms note that tax-loss harvesting can be useful for households with even modest investment portfolios, provided they pay attention to the rules and costs involved.
Are HSAs only for high-income taxpayers?
No. HSAs are tied to the type of health insurance plan, not income level. Anyone enrolled in a qualifying high-deductible health plan and meeting IRS requirements can use an HSA, gaining the associated tax benefits.
How often should I review my tax strategy?
At minimum, it is wise to review your tax situation once a year, especially before year-end, and whenever you experience major life events such as marriage, divorce, a new child, buying a home, or starting a business. Year-round monitoring helps you adjust withholding, estimated payments, and contributions as needed.
References
- 8 ways to potentially lower your taxes — Ameriprise Financial. 2024-02-15. https://www.ameriprise.com/financial-goals-priorities/taxes/ways-to-lower-taxes
- 9 ways to potentially reduce your taxable income — Fidelity Investments Learning Center. 2024-01-18. https://www.fidelity.com/learning-center/personal-finance/how-to-reduce-taxable-income
- Act now: 14 ways to lower your tax bill — J.P. Morgan Private Bank. 2025-01-10. https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/act-now-14-ways-to-lower-your-tax-bill
- 5 Ways to Save on Your Taxes This Year — Union Bank. 2024-03-05. https://www.gounion.bank/u-for-you-blog/5-ways-to-save-on-your-taxes
- 10 Tax Tips That Could Save You Money — Merrill Lynch / Bank of America. 2025-02-03. https://www.ml.com/articles/tax-tips-that-could-save-you-money.html
- Ways for High Earners to Lower Taxable Income — White Coat Investor community discussion. 2024-06-01. https://www.reddit.com/r/whitecoatinvestor/comments/1k1m7j4/ways_for_high_earners_to_lower_taxable_income/
- The Working Families Tax Cuts Deliver Biggest Wins for the Working Class — U.S. House Committee on Ways and Means. 2024-04-25. https://waysandmeans.house.gov/theonebigbeautifulbill/fact-sheets/the-one-big-beautiful-bill-delivers-biggest-wins-for-the-working-class/
Similar Articles








Read full bio of medha deb




