Many families assume that estate taxes only affect billionaires, but rising property values, retirement savings, closely held businesses, and life insurance can push an estate into taxable territory. With careful planning, you can often minimize estate taxes and pass more wealth to the people and causes you care about.
This guide explains how estate taxes work in the United States and outlines practical, legally recognized ways to lower your taxable estate. It draws on general principles of tax law, but real planning decisions should be made with help from a qualified estate planning attorney and tax professional.
Understanding When Estate Taxes Apply
Before focusing on reduction strategies, it is important to understand when estate tax may be an issue at all.
The federal estate tax applies only to estates over a certain size, known as the federal estate tax exemption. This threshold changes over time with inflation adjustments and legislative changes and is measured by the total value of a person’s assets at death, plus certain taxable gifts made during life.
| Year of Death | Estate Value Above Which a Return Is Required |
|---|---|
| 2022 | $12.06 million |
| 2023 | $12.92 million |
| 2024 | $13.61 million |
| 2025 | $13.99 million |
| 2026 | $15.00 million |
These thresholds are set by federal law and published by the Internal Revenue Service (IRS). Many people will never owe federal estate tax, but high-net-worth households, owners of successful businesses, and individuals in high-cost real estate markets may cross these limits.
Separate from federal rules, more than a dozen states and the District of Columbia impose their own estate taxes or inheritance taxes, often at much lower thresholds than the federal level. As a result, you may face state-level transfer taxes even if you are well below the federal exemption.
Key Concepts to Know
- Gross estate: The total value of all property you own at death, including real estate, investments, retirement accounts, business interests, and some life insurance.
- Taxable estate: The gross estate minus deductions, such as debts, certain expenses, the marital deduction, and charitable bequests.
- Unified credit / basic exclusion amount: A lifetime amount that shields transfers (during life or at death) from federal estate and gift tax.
Core Strategy: Start Planning Early
Estate tax reduction is most effective when it is part of a long-term plan, not a last-minute move. Early planning gives you time to:
- Move appreciating assets out of your estate before they grow further.
- Use annual gift exclusions over many years.
- Design and implement trusts with appropriate terms.
- Coordinate with state estate or inheritance tax rules.
Financial institutions and planning organizations consistently emphasize that proactive planning is essential to manage estate tax exposure and reduce the risk of forced asset sales to pay taxes.
Using Lifetime Gifts to Shrink Your Estate
One of the simplest ways to reduce the size of your taxable estate is to give assets away while you are alive. Well-structured lifetime gifts can remove both the current value and the future growth of those assets from your estate.
Annual Gift Tax Exclusion
Federal law allows you to give up to a set amount each year to as many individuals as you like without incurring federal gift tax or using your lifetime exemption. This is known as the annual gift tax exclusion.
Financial planning resources note that this exclusion is adjusted periodically and can be leveraged by:
- Making annual gifts to children, grandchildren, or other relatives.
- Splitting gifts with your spouse, effectively doubling the annual amount you can transfer to each recipient.
- Spreading gifts over multiple years to gradually move large sums out of your estate.
Educational and Medical Payments
Certain payments for someone else’s benefit do not count as taxable gifts at all when made directly to the provider:
- Tuition paid directly to an educational institution.
- Medical expenses paid directly to a medical provider.
Because these transfers are excluded from gift tax, they can be an efficient way to help family members while reducing the size of your estate over time.
Gifting to Reduce Future Growth
Gifting is especially powerful when it involves assets you expect to appreciate significantly, such as a growing business or investment portfolio. By transferring these assets earlier in life, you:
- Move current value out of your estate.
- Allow future appreciation to occur outside your taxable estate.
Estate planning professionals often pair these gifts with trusts or family entities to retain some control while still achieving tax benefits.
Trusts as Tools for Estate Tax Reduction
Trusts are legal arrangements in which one party (the trustee) holds and manages property for the benefit of others (the beneficiaries). Properly structured trusts can remove assets from your taxable estate, shift future growth to heirs, and provide control and protection.
Irrevocable Trusts
Assets you transfer to an irrevocable trust are generally not considered part of your taxable estate, provided you relinquish sufficient control and follow applicable tax rules. Common uses include:
- Holding life insurance to prevent policy proceeds from being included in your estate.
- Transferring investment or business interests while retaining professional management.
- Protecting assets from creditors or future legal claims.
Law firms and estate planning commentators frequently highlight irrevocable trusts as a key technique to separate assets from an estate, particularly for high-net-worth families.
Specialized Trust Structures
More advanced trust strategies allow for precise control over income, principal, and remainder interests. Examples used in practice include:
- Grantor retained annuity trusts (GRATs): The grantor contributes assets to a trust but retains a right to receive fixed payments for a term of years. At the end of the term, remaining assets pass to beneficiaries, often at a reduced gift tax cost.
- Qualified personal residence trusts (QPRTs): The grantor transfers a home to a trust while retaining the right to live in it for a set period, potentially reducing the taxable value of the transfer.
- Grantor trusts: Trusts where the grantor pays income tax on trust earnings, which can further reduce the grantor’s taxable estate without additional gift tax.
These techniques require detailed legal and tax analysis, but they can substantially reduce estate tax for large estates when designed and administered correctly.
Charitable Giving and Estate Taxes
Charitable gifts are not only a way to support causes you care about; they can also deliver significant estate and income tax benefits. Transfers to qualified charitable organizations are generally deductible for estate tax purposes and may also generate income tax deductions when made during life.
Lifetime Charitable Gifts
Strategies for incorporating philanthropy into estate tax planning include:
- Direct contributions to public charities or donor-advised funds.
- Donating appreciated securities to avoid capital gains tax while securing an income tax deduction.
- Pairing charitable donations with lifetime gifting to family, balancing personal and philanthropic goals.
Charitable Trusts
Charitable trusts can combine personal income benefits with eventual charitable gifts:
- Charitable remainder trusts (CRTs): You transfer property to a trust, receive income for life or a term of years, and the remainder goes to charity. These trusts can reduce current income tax and remove assets from your taxable estate.
- Charitable lead trusts (CLTs): A charity receives income for a period, after which remaining assets pass to your heirs, potentially at a reduced transfer tax cost.
These vehicles are often recommended for individuals with highly appreciated assets or strong philanthropic priorities.
Leveraging the Marital Deduction and Spousal Planning
The federal tax system allows unlimited transfers between spouses who are U.S. citizens free of estate and gift tax, known as the marital deduction. While this can defer estate taxes until the second spouse’s death, it does not automatically minimize overall taxes.
Using Both Spouses’ Exemptions
Effective estate plans usually aim to take full advantage of both partners’ exemptions. Common approaches include:
- Leaving some assets outright or in certain trusts for children or other beneficiaries at the first spouse’s death.
- Using credit shelter or bypass-type trusts to preserve the first spouse’s exemption.
- Relying on portability rules, where available, to allow a surviving spouse to use a deceased spouse’s unused federal estate tax exemption.
The exact approach depends on asset levels, state law, and family goals, but coordinated spousal planning is often central to reducing estate taxes in married couples.
Family Entities and Valuation Discounts
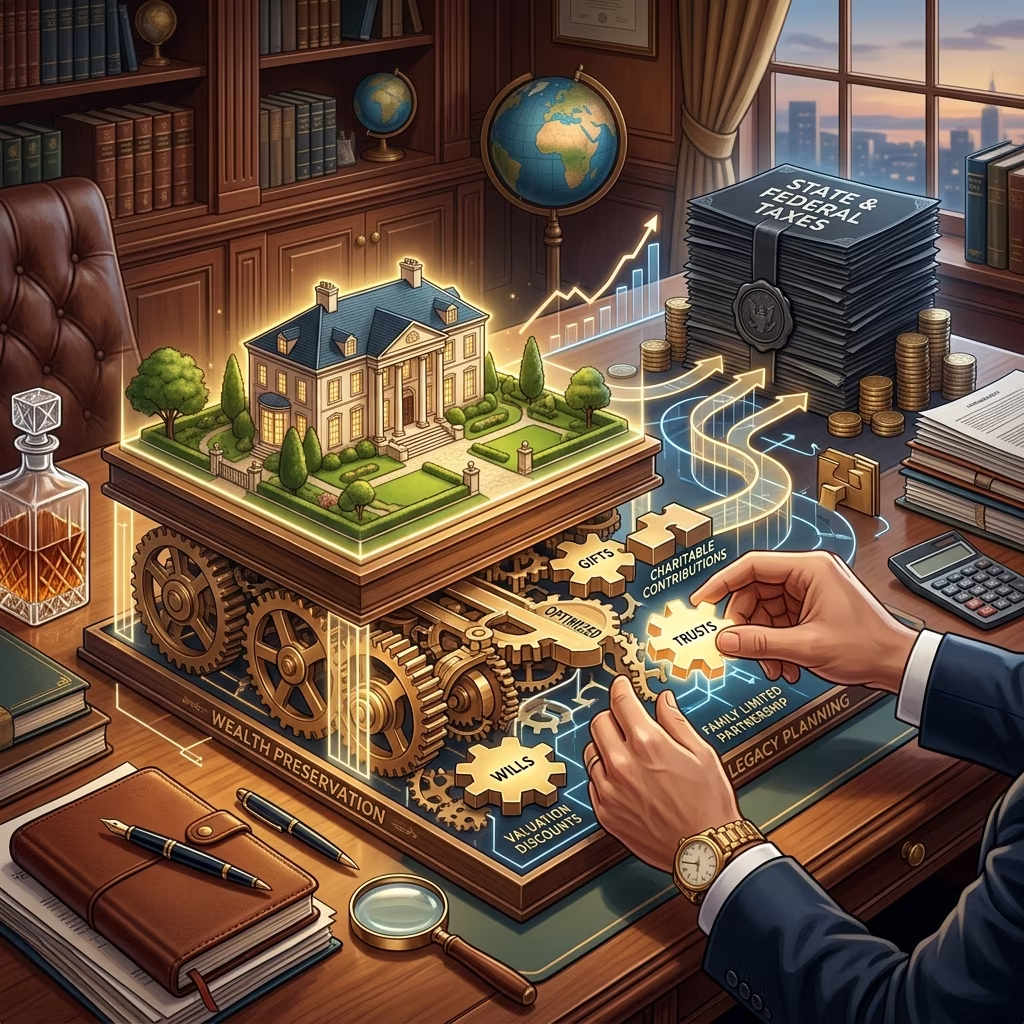
For families with closely held businesses, investment real estate, or large concentrated portfolios, creating a family limited partnership (FLP) or family limited liability company (LLC) can be another powerful planning tool.
In a typical arrangement:
- Parents contribute assets to an FLP or LLC and receive managing interests and non-controlling interests.
- They then gradually transfer non-controlling interests to children or trusts.
Because transferred interests often lack control and marketability, professional appraisers may apply valuation discounts when determining the fair market value of those interests for gift and estate tax purposes. This allows more underlying value to be moved out of the estate while reporting a lower taxable value, subject to IRS scrutiny and legitimate business purposes.
Coordinating Estate Taxes with Liquidity Planning
Even if you successfully reduce your taxable estate, your estate may still owe taxes and other expenses. Planning for how those costs will be paid is crucial to avoid forced sales of family businesses, real estate, or long-term investments.
Life Insurance as a Funding Tool
Many advisors recommend using life insurance to provide liquidity for estate taxes. When owned inside an irrevocable life insurance trust, policy proceeds can remain outside your taxable estate and be used to:
- Help heirs pay estate taxes and settlement costs.
- Fund buy-sell agreements for family businesses.
- Equalize inheritances among beneficiaries when some receive illiquid assets.
Major financial institutions note that properly structured insurance can allow families to preserve long-held assets rather than selling them rapidly to raise cash for tax obligations.
State Estate and Inheritance Taxes
Federal planning is only part of the picture. Some states impose their own estate or inheritance taxes, often with lower exemptions and different rules than the federal system. According to large financial planning institutions, several states have exemption levels that fall far below the federal threshold, making state planning necessary for many moderately wealthy households.
To address state-level exposure, individuals sometimes:
- Consider their state of domicile in long-term plans.
- Use gifting, trusts, and charitable strategies tailored to state law.
- Coordinate with local professionals familiar with their state’s estate and inheritance tax regimes.
Putting It All Together: A Practical Planning Checklist
Every family’s situation is unique, but the following checklist summarizes the main areas to discuss with your estate planning team:
- Estimate the gross and taxable value of your estate, including life insurance and business interests.
- Review federal and state estate or inheritance tax exposure.
- Create or update a will, powers of attorney, and health care directives.
- Evaluate whether revocable and irrevocable trusts would improve control, protection, or tax outcomes.
- Implement a structured lifetime gifting program using annual exclusions and education/medical exclusions.
- Consider charitable strategies that align with your values and tax goals.
- Coordinate business succession plans, including buy-sell agreements and funding mechanisms.
- Ensure adequate liquidity, potentially through insurance and cash reserves, to pay future estate taxes and expenses.
- Review your plan periodically as laws, asset levels, and family circumstances change.
FAQs About Reducing Estate Taxes
Do I really need to worry about estate taxes if my wealth is mostly in my home and retirement accounts?
It depends on the combined value of all your assets and your state’s tax laws. Federal estate tax applies only above a relatively high threshold, but state estate or inheritance taxes can apply at much lower levels. Even if you are under federal limits, planning can still help you manage state taxes and ensure that your assets transfer smoothly to your chosen beneficiaries.
Are lifetime gifts always the best way to reduce estate taxes?
Lifetime gifts are a powerful tool, but they are only one part of a comprehensive plan. You must balance tax savings with your own financial security and consider the legal, emotional, and practical effects of transferring ownership. In some cases, using trusts or family entities might provide better control or protection than outright gifts.
Will I lose all control if I use irrevocable trusts or family limited partnerships?
Not necessarily. Many structures allow you to retain management roles or oversight while still removing assets from your taxable estate. However, the more control you retain, the more carefully the structure must be analyzed from a tax perspective. The balance between control and tax benefits should be evaluated with professional guidance.
How often should I review my estate tax plan?
Most advisors recommend revisiting your plan whenever there is a major life event (marriage, divorce, birth of a child or grandchild, death of a spouse) or a significant change in your asset levels. You should also review your plan when tax laws change, particularly around federal and state estate tax exemptions, which have shifted several times in recent years.
Can charitable giving eliminate estate taxes entirely?
For some individuals with strong philanthropic goals, it is possible to direct enough assets to charity that little or no estate tax is owed. For many others, charitable strategies are used to reduce, rather than eliminate, estate tax exposure while still providing for family. Tools such as charitable trusts and donor-advised funds make it easier to tailor the balance between family inheritance and charitable impact.
References
- Estate Tax — Internal Revenue Service. 2024-01-01. https://www.irs.gov/businesses/small-businesses-self-employed/estate-tax
- 5 Tips to Help Reduce Estate Taxes — Fidelity Investments. 2024-02-15. https://www.fidelity.com/learning-center/personal-finance/how-to-avoid-estate-taxes
- Reduce the Taxable Value of an Estate — Ameriprise Financial. 2024-03-10. https://www.ameriprise.com/financial-goals-priorities/family-estate/reduce-taxable-value-estate
- 10 Strategies to Reduce the Value of a Client’s Estate — WealthCounsel. 2023-08-01. https://info.wealthcounsel.com/blog/10-strategies-to-reduce-the-value-of-a-clients-estate
- Ten Advanced Estate Planning Techniques — Venable LLP. 1999-10-01. https://www.venable.com/insights/publications/1999/10/ten-advanced-estate-planning-techniques
- Estate Tax Planning: Legal Strategies to Reduce Taxes — LegalShield. 2024-04-01. https://www.legalshield.com/blog/estate-tax-planning
- Mastering Estate Taxes: How to Plan Ahead to Protect Your Financial Assets — J.P. Morgan Private Bank. 2023-06-20. https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/mastering-estate-taxes-how-to-plan-ahead-to-protect-your-financial-assets