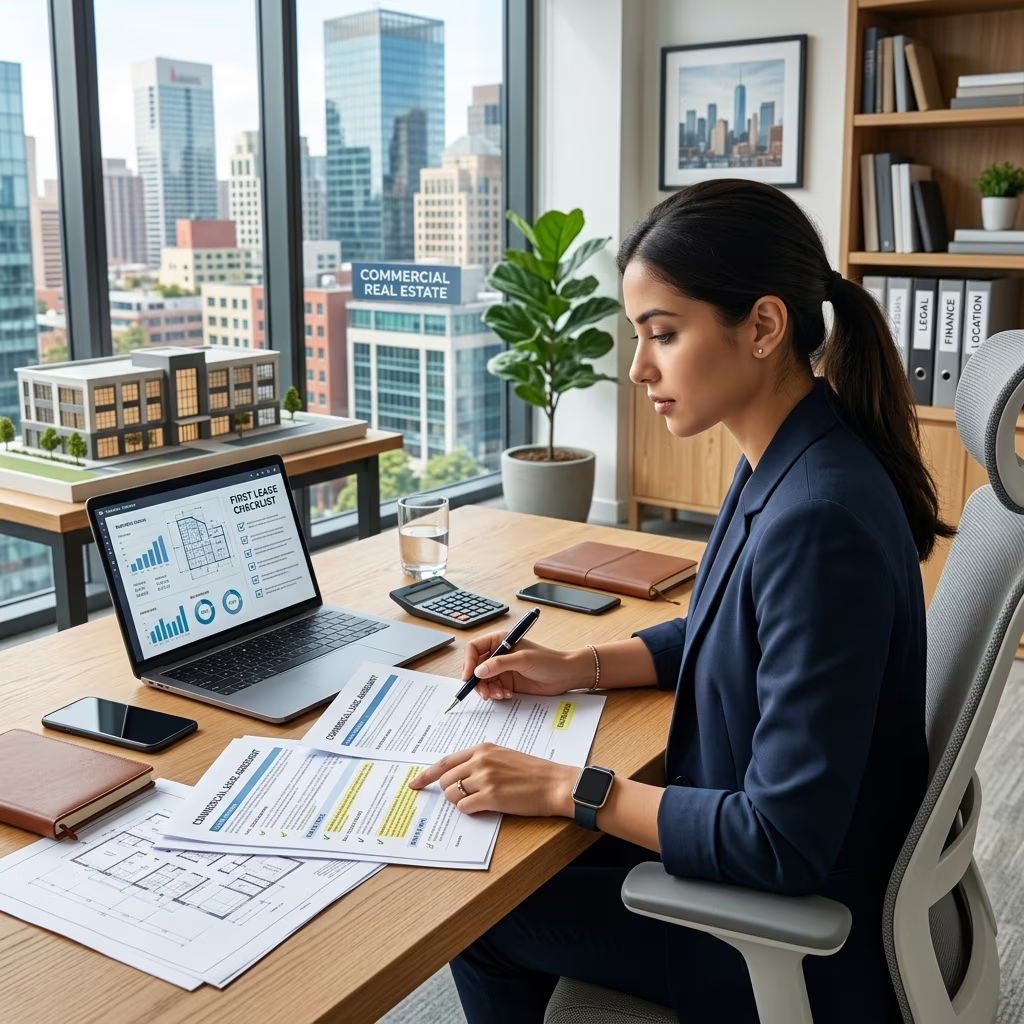
Signing a commercial lease is one of the biggest commitments many small business owners make. The right lease can support growth and stability, while the wrong one can lock you into high costs, legal headaches, and an inflexible space your business outgrows too quickly. This guide walks you through practical steps to review, understand, and negotiate your first lease with confidence.
Instead of diving straight into legal jargon, you will learn how to build a checklist, assemble the right advisors, and spot clauses that affect your money, flexibility, and personal risk. The goal is simple: help you sign a lease that fits your business plan, your budget, and your long‑term strategy.
Why Commercial Leases Are Different From Residential Leases
Many first‑time business tenants expect commercial leases to work like apartment leases. In reality, commercial leases are usually longer, more complex, and less regulated than residential agreements. Important protections that exist for residential tenants often do not apply to businesses, and landlords expect tenants to negotiate terms before signing.
- Fewer standard forms: Commercial leases are often customized, so each landlord may use different language and structures.
- More negotiation room: Key terms like rent, renewal options, build‑out responsibilities, and assignment rights are generally negotiable.
- Greater financial exposure: You may be responsible not just for rent, but for taxes, insurance, maintenance, and shared building costs under lease types such as triple‑net arrangements.
Because of these differences, treating a commercial lease as a simple, standard contract is risky. A deliberate, systematic review process is essential.
Assemble Your Advisory Team Before You Sign
Before you scrutinize clauses, make sure you have the right people at the table. Professional advice costs money, but a single poorly drafted clause can cost far more over the life of the lease.
| Advisor | Primary Role | Key Questions They Help Answer |
|---|---|---|
| Business Attorney | Review legal terms, identify hidden risks, negotiate protective language. | What rights do I have to renew, exit, or sublease? Which laws govern disputes? |
| Accountant or Financial Advisor | Evaluate total occupancy costs and cash‑flow impact over the lease term. | Can the business afford worst‑case costs? How will rent escalations affect profits? |
| Insurance Professional | Match required coverage to the lease terms and business risks. | What policies and limits do the landlord and lender require? |
| Real Estate Broker (optional) | Compare market terms and help negotiate rent and concessions. | Is this rent and lease structure competitive for the area and property type? |
Share your business plan and realistic projections with these advisors so they can tailor their advice to your growth expectations, risk tolerance, and timeline.
Clarify What You Are Leasing and for How Long
Before getting lost in fine print, verify basic details: the space you are renting, your allowed use, and the length of your commitment. Errors at this level can create serious operational problems.
Confirm the Premises Description
- Location details: Check that the address, unit number, and floor match the space you toured.
- Size and layout: Verify square footage, how it is measured, and whether common areas (hallways, loading docks) are included.
- Boundaries and access: Look for clear descriptions of walls, entrances, shared facilities, and any restricted maintenance areas such as the roof or mechanical rooms.
If your business depends on particular features—parking, signage, storage, or delivery docks—make sure they are explicitly mentioned in the lease rather than assumed.
Understand Lease Term and Renewal Options
The lease term and renewal rights shape how long you are tied to the location and how flexible you will be if your business grows or shifts.
- Initial term: Confirm the start and end dates, and whether there is a rent‑free or build‑out period before you must begin paying full rent.
- Renewal rights: Identify options to extend, the amount of notice required, and how the rent will be set for renewal periods.
- Automatic changes: Review any automatic rent increases, CPI‑based escalations, or operating cost adjustments that occur during renewal.
Discuss with your accountant whether your projected revenue and business plan align with the duration and any escalation patterns you see in the contract.
Map Out the Full Cost of Occupancy
Rent is only one component of what you pay. A careful lease review should build a complete picture of your total occupancy costs, including variable charges that may rise over time.
Break Down Rent and Additional Charges
- Base rent: The fixed amount due each month or year for the space itself.
- Operating expenses: Your share of property taxes, building insurance, maintenance, and common‑area costs, often called CAM charges or additional rent.
- Utilities and services: Responsibility for electricity, water, gas, internet, trash removal, and HVAC maintenance should be clearly assigned.
- Security deposit and fees: Review deposit requirements, late payment fees, and any administrative or management fees.
Under a triple‑net lease, tenants typically pay base rent plus most operating costs for taxes, insurance, and maintenance. This structure can significantly change your monthly expenses compared with a gross lease where more costs are included in rent.
Plan for Rent Increases and Financial Cushion
Leases often include scheduled rent increases or adjustment mechanisms. Understanding how and when rent can change helps you prepare for future cash‑flow demands.
- Escalation clauses: Identify step‑ups (e.g., annual percentage increases) or index‑based adjustments tied to inflation or operating expenses.
- Caps and floors: Look for limits that prevent extreme increases and ensure adjustments are predictable.
- Budget buffer: Work with your accountant to estimate a realistic cushion—often several months of operating expenses—to cover slow periods or unexpected costs.
By modeling best‑case and worst‑case cost scenarios, you can avoid entering into a lease that your business cannot sustain if costs rise or revenue fluctuates.
Know What You Can Do in the Space
A lease should clearly state how you may use the premises and whether you have any exclusive rights. These clauses affect both your current operations and future business opportunities.
Permitted Use and Restrictions
- Business type: Confirm that the lease explicitly allows your industry (retail, office, manufacturing, restaurant) and any special activities like on‑site production or events.
- Regulatory compliance: Check that the space can be legally used for your purpose under local zoning and health or safety codes; you may need permits or inspections before opening.
- Operational limits: Watch for restrictions on hours of operation, noise, odors, deliveries, or customer traffic that could hinder your business model.
Exclusivity and Competition
If your business depends on a unique position in a shopping center or building, you may want clauses that limit direct competitors from leasing nearby space.
- Exclusive use rights: These provisions can prevent the landlord from renting adjacent units to businesses offering the same core products or services.
- Anchor tenants and co‑tenancy: Some leases tie your obligations to the presence of anchor stores or minimum occupancy levels, which can matter for retail foot traffic.
Discuss how important exclusivity is for your business; negotiating these terms early is far easier than trying to fix competition issues later.
Allocate Maintenance, Repairs, and Build‑Out Duties
Commercial lease obligations for repairs and improvements vary widely. Clarifying who is responsible for what helps you avoid surprise bills and disputes.
- Structural vs. interior: Leases often place structural elements (roof, foundation, exterior walls) under landlord responsibility, while tenants handle interior fixtures and finishes.
- System maintenance: Confirm responsibilities for HVAC, plumbing, electrical, and fire‑safety systems, especially ongoing service contracts.
- Alterations and build‑outs: Identify whether you need landlord approval for renovations, who pays for improvements, deadlines for completing work, and whether you must remove alterations at the end of the lease.
When planning your build‑out, coordinate timelines for permitting, contractor schedules, and inspection requirements with the lease start date to avoid paying full rent before you can operate.
Manage Insurance and Risk Transfer
Most commercial leases require tenants to carry specific types of insurance and name the landlord or lender as additional insureds. Matching these requirements with your actual risk profile and budget is crucial.
- Required policies: Typical coverage includes general liability, property insurance for your contents and improvements, and sometimes business interruption insurance.
- Coverage limits: Ensure policy limits meet or exceed the minimums in the lease while remaining affordable.
- Certificates and endorsements: Landlords often require proof of coverage and special endorsements; confirm timing and documentation obligations.
Discuss indemnification clauses, waiver of subrogation, and mutual release provisions with your attorney and insurance professional so you understand who bears responsibility for different types of losses.
Plan Your Exit Strategy Before You Move In
No business owner expects failure, but smart planning acknowledges that your needs may change. Building a realistic exit strategy into the lease can significantly reduce future stress.
Early Termination and Default
- Termination rights: Look for clauses that allow you to end the lease early under defined conditions, such as prolonged landlord default, casualty damage, or failure to obtain key permits.
- Default consequences: Understand late fees, acceleration clauses (requiring payment of remaining rent), and landlord remedies if you miss payments or breach obligations.
- Cure periods: Notice and cure provisions give you a window to fix issues before they become formal defaults; negotiate sufficient time.
Assignment and Subletting
Assignment and subletting clauses address whether you can transfer the lease to another business or share space if your circumstances change.
- Landlord consent: Many leases require landlord approval before you assign or sublet; aim for language that prevents unreasonable withholding of consent.
- Partial subleases: If you might want to rent part of your space to another business, confirm that the lease allows partial subletting.
- Successor entities: Consider provisions that allow assignment to an affiliated company or buyer if you sell your business.
A clear exit strategy can turn a rigid, risky lease into a flexible tool that adapts with your business over time.
Protect Yourself From Personal Liability
One major advantage of operating as a corporation or LLC is limited personal liability. However, commercial leases sometimes include personal guarantees that bypass this protection.
- Identify guarantees: Look for any clauses requiring you, as an individual, to guarantee lease obligations or pledge personal assets.
- Negotiate limitations: Consider requesting reduced guarantee amounts, time limits, or release provisions once the business demonstrates strong performance.
- Separate business credit: Work toward building credit in the name of your company so future leases rely less on personal guarantees.
Discuss personal guarantees carefully with your attorney and accountant; the long‑term implications can be significant if your business encounters unexpected difficulties.
Final Pre‑Signing Checklist
Before signing, set aside time to walk through a structured checklist. Use the list below as a starting point and adapt it to your situation.
- Have a business attorney reviewed every key clause and explained your rights and obligations in plain language?
- Has your accountant confirmed that projected revenue covers worst‑case occupancy costs, including rent escalations and operating expenses?
- Is the description of the premises accurate, and does it reflect the actual space and amenities you expect to use?
- Are permitted uses, exclusivity, and zoning considerations aligned with your business model and growth plans?
- Are maintenance, repairs, and build‑out responsibilities clearly divided between you and the landlord, with realistic timelines for opening?
- Do you understand all insurance requirements and have a plan to obtain coverage before move‑in?
- Is there a viable exit strategy, including reasonable assignment, subletting, and termination provisions?
- Have you minimized or carefully structured any personal guarantees to protect your personal assets?
If you can answer “yes” to each of these questions, you are far better positioned to sign a lease that supports—not undermines—your small business.
Frequently Asked Questions About First Commercial Leases
Do I really need a lawyer to review my first lease?
While not legally required in most jurisdictions, working with a business attorney is strongly recommended. Commercial leases involve complex allocation of risk, and subtle language can dramatically change your rights. An attorney can flag one‑sided provisions, suggest better wording, and help you negotiate improvements before you commit.
How can I tell if the rent is reasonable for my area?
Compare the proposed rent, lease type, and additional charges with similar properties in the same neighborhood and of the same class. Local commercial brokers and economic development agencies sometimes offer data or tools to help small businesses assess comparable terms. Your accountant can then fold these numbers into cash‑flow projections to see whether the lease fits your budget.
What is the difference between gross and triple‑net leases?
In a gross lease, many building‑level expenses—such as taxes, insurance, and some maintenance—are included in the base rent. In a triple‑net lease, tenants typically pay base rent plus separate charges for property taxes, insurance, and maintenance, making total costs more variable and sometimes higher over time. Understanding which structure applies is crucial for accurate budgeting.
Can I negotiate terms even if the landlord says the lease is standard?
Yes. “Standard” leases are usually drafted in the landlord’s favor and are starting points, not fixed rules. Many landlords expect negotiation on items such as renewal options, repair responsibilities, assignment rights, and personal guarantees. Being prepared with specific requests and alternatives increases your chances of a balanced agreement.
How far in advance should I start the leasing process?
It is prudent to begin searching and reviewing draft leases several months before you need to occupy the space. This timeline allows for site selection, build‑out planning, permitting, and negotiation without rushing into unfavorable terms. Early planning also helps coordinate utilities, insurance, and staff relocation before opening day.
References
- Checklist for Signing a Commercial Lease for Your Small Business — FindLaw / Thomson Reuters. 2020-07-02. https://www.findlaw.com/legalblogs/small-business/checklist-for-signing-your-first-small-business-commercial-lease/
- Small Businesses and Commercial Lease Guide — Travelers Insurance. 2022-03-15. https://www.travelers.com/resources/business-industries/small-business/5-things-to-know-before-renting-or-leasing-space
- Commercial Lease Checklist for Small Businesses — City of Seattle Office of Economic Development. 2018-06-01. https://www.seattle.gov/documents/departments/economicdevelopment/restaurants/final%20full%20lease%20tool.pdf
- Commercial Lease Review Checklist for Businesses — Joseph & Joseph Co. LPA. 2025-05-23. https://josephandjoseph.com/2025/05/23/commercial-lease-review-checklist-for-business-owners/
- A Tenant’s Checklist for Commercial Lease Negotiations — Outside GC. 2019-09-10. https://outsidegc.com/blog/a-tenants-checklist-for-commercial-lease-negotiations/
- Essential Commercial Lease Checklist for Business — OMB Solicitors. 2023-02-01. https://omb.com.au/commercial-lease-checklist-key-clauses-to-review-before-you-sign/
- How to Lease Commercial Space: The Ultimate Checklist — Cummings Properties. 2024-04-05. https://cummings.com/how-to-lease-commercial-space.html