
Protecting Yourself From Home Improvement Loan Scams
Learn how to spot, avoid, and respond to home improvement loan scams before they drain your equity and your savings.
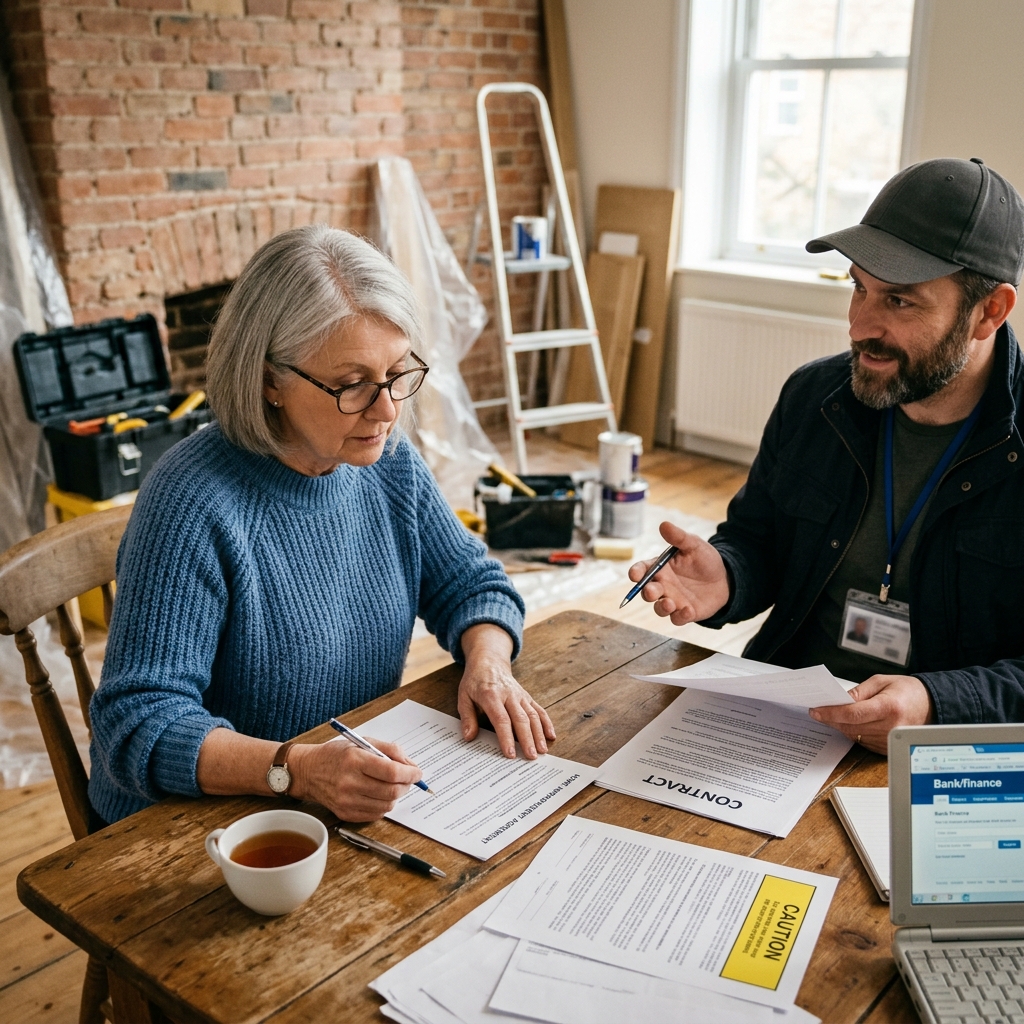
Home renovation can boost your property value and comfort, but it also opens the door to scammers who target homeowners with deceptive financing and bogus improvements. When a contractor arranges a loan that you barely understand, you risk losing savings, damaging your credit, or even putting your home at risk as collateral. Understanding how these scams work and how to finance your project safely is essential for protecting your home and your wallet.
Why Home Improvement Loan Scams Are So Dangerous
Home improvement loan scams blend two vulnerabilities: the complexity of lending and the urgency of repairs or upgrades. Scammers know that many homeowners are not experts in credit terms, interest rates, or lien documents, and they exploit this knowledge gap to push expensive or fraudulent financing.
Common consequences of falling for a home improvement loan scam include:
- Excessive debt from high-interest loans or hidden fees tucked into the contract.
- Liens against your home that you did not fully understand, increasing the risk of foreclosure if you miss payments.
- Poor or incomplete workmanship despite paying substantially for the project.
- Loss of savings through upfront payments or cash transfers that are hard to recover.
- Damage to your credit profile if you default on a loan you never should have taken in the first place.
These scams often imitate legitimate renovation financing, making it critical to distinguish honest offers from abusive or fraudulent schemes.
How Home Improvement Loan Scams Typically Work
Fraudsters rarely present their scheme as a “scam.” Instead, they pose as friendly contractors or sales representatives offering an easy solution to pay for the work. Below is a typical progression of events in a home improvement loan scam.
1. The Approach: Unsolicited Offers and High-Pressure Pitches
Many scams start with an unsolicited approach, such as a contractor knocking on your door, a telemarketing call, or a flyer promising steep discounts on repairs. They may claim they “just finished a job nearby” and have materials left over or say they noticed a problem with your roof, siding, or driveway.
Red flags at this stage include:
- Showing up uninvited and insisting damage is urgent.
- Offering a “today-only” deal if you agree immediately.
- Discouraging you from seeking other bids or opinions.
2. The Financing Hook: “We Can Arrange a Loan For You”
Once you show interest in the project, the scammer offers to “take care of the financing,” presenting themselves as a convenient intermediary between you and a lender. They may push:
- Home equity loans or lines of credit tied to your house.
- Installment loans with high interest and long repayment periods.
- Deferred interest offers that spike in cost after an introductory period.
According to consumer protection agencies, scammers often suggest specific lenders they “work with” and discourage you from speaking directly with your bank or credit union. They may rush you through paperwork, gloss over terms, or ask you to sign forms you have not fully read.
3. The Paper Trail: Complex Contracts and Hidden Terms
At this stage, the scammer pairs a confusing renovation contract with loan documents. The paperwork may:
- Fail to clearly separate the cost of the project from the cost of financing.
- Contain clauses allowing the contractor to change materials or prices without your explicit approval.
- Include authorization for the contractor to receive funds directly from the lender.
- Require you to sign a completion certificate before the project is fully done.
If you sign without understanding the documents, you may agree to a loan that is far more expensive than you realize or give the contractor access to funds before any work occurs.
4. The Outcome: Poor Work, Abandoned Jobs, or Overbilling
Once the financing is in place, dishonest contractors often perform substandard work, fail to finish, or disappear entirely after receiving payment from the lender. You then face the double burden of repairing defective construction and repaying a loan for work that did not meet your expectations.
If the loan is secured by a lien on your home and you cannot keep up with payments, your risk extends beyond inconvenience to potential loss of your property.
Key Warning Signs of a Home Improvement Loan Scam
Recognizing warning signs early can help you avoid trouble. National consumer and aging organizations highlight several patterns that frequently appear in home improvement and financing scams.
| Warning Sign | Why It Matters |
|---|---|
| Contractor is not licensed or insured | Unlicensed workers are harder to hold accountable and may be operating illegally. |
| Insists on arranging financing for you | May steer you into costly loans or receive kickbacks from lenders. |
| Demands full payment or large deposits upfront | Upfront cash reduces your leverage if work is poor or incomplete. |
| Requests payment in cash, wire transfers, or prepaid cards | These methods are difficult to trace or reverse in case of fraud. |
| Pressures you to sign quickly without reading documents | Rushing prevents you from spotting abusive clauses or unfamiliar loan terms. |
| Refuses to provide a detailed written contract | A vague agreement makes disputes harder to resolve and evidence weaker. |
| Asks you to get permits yourself | Permits are typically the contractor’s responsibility; shifting the task may signal inexperience or fraud. |
| Discourages you from contacting your own bank or advisor | Isolating you from trusted financial institutions increases their control. |
How to Safely Finance Home Improvements
Not all contractor-arranged financing is fraudulent, but the safest approach is to separate your choice of contractor from your choice of lender. Consumer guidance repeatedly stresses arranging your own financing through institutions you already know and trust.
1. Start With Your Existing Financial Institutions
Before considering any loan proposed by a contractor, speak with:
- Your bank or credit union about personal loans, home equity loans, or lines of credit.
- Your mortgage lender about refinancing or home equity options.
These institutions can explain interest rates, total costs, and repayment schedules in clear terms, allowing you to compare offers objectively. If a contractor’s recommended lender seems significantly more expensive or opaque, that is a strong warning sign.
2. Understand Common Financing Products
While details vary, many renovation projects are financed through a few standard types of credit:
- Home equity loan: A lump-sum loan secured by your home, usually with a fixed interest rate.
- Home equity line of credit (HELOC): A revolving line secured by your home, with a variable rate and flexible draws.
- Unsecured personal loan: A fixed-term loan not tied to your home, typically with higher rates but less risk of foreclosure.
- Credit card financing: Sometimes used for smaller projects, but often costly if not repaid quickly.
Ask lenders to provide a standardized disclosure of costs and risks, and never sign until you can explain the loan’s terms in your own words.
3. Keep Financing and Contracting Decisions Separate
To reduce the risk of being steered into an abusive loan:
- Choose your contractor based on skill, licensing, and references—not on their ability to “get you a loan.”
- Secure financing independently, comparing multiple offers.
- Refuse to sign documents that give the contractor authority to approve loan terms or access funds without your confirmation.
This separation ensures you retain control over both the work and the way you pay for it.
Choosing Trustworthy Contractors Before You Borrow
Even the best loan terms cannot rescue a project managed by a dishonest or incompetent contractor. Federal, state, and nonprofit agencies recommend a systematic vetting process before hiring anyone.
1. Verify Licensing, Insurance, and Complaints
To confirm a contractor is legitimate:
- Check with your state or local licensing agency to see if the contractor is properly licensed and whether any complaints have been filed.
- Ask for proof of liability insurance and, when applicable, workers’ compensation coverage.
- Confirm that the business name, address, and phone number match what appears in official records and on the contract.
2. Seek Multiple Bids and Independent References
Experts recommend getting written estimates from at least three contractors for substantial projects. Each estimate should describe:
- Scope of work and materials.
- Estimated start and completion dates.
- Total price and payment schedule.
Additionally:
- Ask for references from recent customers and, if possible, visit completed projects.
- Check online reviews and Better Business Bureau records, keeping in mind that a few negative comments are less concerning than repeated patterns of similar complaints.
3. Insist on a Detailed Written Contract
A written contract protects both you and the contractor by clearly documenting expectations. At minimum, your contract should include:
- Full legal name, address, phone number, and license number of the contractor.
- Description of all work to be performed and materials to be used.
- Start and completion dates, including conditions that may justify changes.
- Total price, schedule of payments, and any deposit limits.
- Procedures for change orders—extra work or materials must be documented and priced before being done.
- A statement of your right to cancel, where required by law, particularly for contracts signed at your home.
Read every clause and ask questions until you are comfortable; never rely solely on verbal assurances.
Safe Payment Practices During Your Project
How and when you pay can influence your leverage if something goes wrong. Consumer guidance provides consistent recommendations for safer payment arrangements.
1. Limit Deposits and Avoid Paying in Full Upfront
Some jurisdictions restrict the size of deposits contractors may request. Even where no legal cap exists, it is wise to:
- Pay a modest deposit only after you have a signed contract.
- Schedule progress payments tied to completion of clearly defined stages.
- Reserve a final payment until the project is fully complete and you have inspected the work.
2. Use Traceable Payment Methods
To preserve evidence and potential remedies:
- Pay by check or credit card rather than cash, prepaid cards, or untraceable apps.
- Keep copies of all invoices, receipts, and cancelled checks.
- Document any changes in writing before sending additional payments.
Traceable payments help you demonstrate what was paid, when, and for what purpose if a dispute or legal action becomes necessary.
3. Verify Completion Before Signing Anything
Some scams involve pressuring you to sign a completion certificate or lien waiver while work is incomplete. Before signing:
- Inspect all areas of the project and confirm they match the contract description.
- Ensure the job site is clean, with tools and debris removed.
- Obtain written warranties for materials and workmanship.
- Confirm that subcontractors have been paid to avoid unexpected liens.
If You Suspect You’ve Been Scammed
Acting quickly can improve your chances of limiting financial damage and obtaining a remedy. Consumer protection agencies and nonprofit organizations recommend a structured response if you suspect fraud or severe misconduct.
1. Start With the Contractor
Some problems result from poor communication rather than deliberate fraud. First, try to resolve the issue directly:
- Document your concerns in writing and request specific corrections or a plan to finish the work.
- Follow up important phone calls with letters sent by certified mail and keep copies for your records.
2. Contact Relevant Authorities
If negotiation fails or you believe you were intentionally misled:
- File a complaint with your state or local consumer protection agency.
- Report the business to the Better Business Bureau, which tracks patterns of misconduct.
- Notify your state attorney general, especially when larger sums or widespread patterns of fraud are involved.
These agencies can offer guidance on next steps and may investigate significant cases of contractor or loan fraud.
3. Consult Legal and Financial Professionals
Because home improvement loan scams often involve complex contracts and liens, consulting professionals is critical:
- Speak with an attorney experienced in consumer or construction law about potential claims, contract rescission, or defenses against foreclosure.
- Meet with a trusted financial advisor or credit counsellor to understand the impact on your budget and credit, and to plan repayment or renegotiation strategies.
If you believe the loan itself was fraudulent or issued under deceptive circumstances, you may have rights under state and federal consumer credit laws, which a lawyer can explain.
Frequently Asked Questions (FAQs)
1. Is it ever safe to let a contractor arrange my loan?
It can be safe in limited circumstances when the contractor is reputable, the lender is well-established, and you review all loan documents independently. However, consumer agencies generally recommend arranging financing through your own bank or credit union to avoid conflicts of interest and hidden costs.
2. How can I tell if a loan offered for my renovation is too expensive?
Compare the loan’s interest rate, fees, and repayment term with similar products offered by your bank or credit union. If the contractor’s lender is significantly more costly or refuses to provide clear disclosures, treat this as a warning sign and seek other options.
3. What should I do if a contractor asks me to sign blank or incomplete documents?
Never sign blank or partially filled forms. Insist that every space is completed and that you understand each section before signing. If the contractor resists, stop the process and consider finding a different professional.
4. Are large deposits always a scam?
Not always, but deposits that seem excessive or are demanded in cash can indicate trouble. Check whether your state has legal limits on contractor deposits and consider using staged payments based on completed work instead of large upfront sums.
5. Can I cancel a home improvement contract after signing?
In many jurisdictions, you have a right to cancel certain contracts within a short “cooling-off” period, especially for agreements signed at your home. This right should be explained in the contract, but you may need to act within a specific number of days. Check with your state consumer agency or attorney for details.
References
- How to Avoid Home Improvement Scams — Office of the Texas Attorney General. 2023-05-01. https://www.texasattorneygeneral.gov/consumer-protection/home-real-estate-and-travel/how-avoid-home-improvement-scams
- Home Improvement Scams: Tools to Reduce Your Risk — USAging.
- What Is a Home Improvement Scam? Learn 8 Warning Signs — National Council on Aging. 2023-02-15. https://www.ncoa.org/article/what-is-a-home-improvement-scam-learn-8-warning-signs/
- Protect Your Home and Your Wallet: Avoiding Home Improvement Scams — CEFCU. 2022-08-10. https://cefcu.com/post/protect_your_home_and_your_wallet_avoiding_home_improvement_scams.html
- Here’s How to Uncover a Home Improvement Scam — AARP. 2024-03-20. https://www.aarp.org/money/scams-fraud/home-improvement/
Similar Articles








Read full bio of medha deb




