Payday loans are widely advertised as a quick way to get cash between paycheques, but in Canada they are one of the most expensive forms of credit you can use. Understanding how these loans work, how they are regulated, and what alternatives exist can help you avoid turning a short-term cash problem into long-term financial stress.
What Is a Payday Loan?
A payday loan is a short-term, high-cost loan typically for a small amount of money, often up to about $1,500, with a due date tied to your next paycheque. These loans are sometimes called high-cost credit or cash advances because the fees are far higher than standard bank loans or credit cards.
Key characteristics of payday loans in Canada include:
- Small loan amounts, usually up to around $1,500.
- Very short repayment periods, from a few days up to roughly 62 days.
- Minimal approval requirements, often no traditional credit check.
- Flat fees charged per $100 borrowed instead of a typical interest rate.
- Repayment scheduled to line up with your next paycheque.
On the surface, this looks simple: you borrow a few hundred dollars and repay it when you get paid. But the fee structure makes these loans extremely expensive.
How Payday Loan Costs Are Calculated
Unlike most credit products, payday lenders charge a fixed fee per $100 borrowed, not a standard interest rate. Under federal rules in Canada, the maximum cost is currently capped at $14 per $100 borrowed in provinces that have payday loan regulations. While $14 may not sound like much, converting that fee into an annual percentage rate (APR) reveals how costly these loans really are.
A $14 fee on a $100 loan over two weeks works out to roughly 365% APR when expressed as an annual interest rate. The shorter the term and the higher the fee, the more extreme the APR becomes, especially when compared to typical bank products where interest may range from just above the prime rate to about 21%.
| Type of product | Example cost | Approximate APR |
|---|---|---|
| Payday loan | $14 fee per $100 borrowed over 2 weeks | ~365% APR |
| Small bank loan / line of credit | Interest just above prime up to ~21% | ~6%–21% APR |
| Credit card cash advance | Interest often around 20%–23% plus a fee | ~20%–25% APR |
In practice, this means that payday loans can cost many times more than other short-term borrowing options. Some analyses have found payday loans can be dozens of times more expensive than a cash advance on a credit card when costs are annualized.
Who Can Get a Payday Loan?
Payday lenders are designed to approve borrowers quickly, even when they might not qualify for bank loans or credit cards. In many provinces, lenders generally ask for proof that you have:
- A regular source of income.
- An active bank account.
- A permanent address.
To secure repayment, lenders typically require you to:
- Sign a pre-authorized debit agreement allowing them to withdraw payments and fees directly from your bank account, or
- Provide a post-dated cheque for the full amount you owe, including fees.
This structure gives the lender strong access to your funds on payday and reduces the chance that you can delay repayment if your budget is tight.
Legal Rules and Consumer Protections
Because payday loans are so expensive and can cause financial hardship, Canada has specific rules governing these products. At the federal level, there is a cap on the cost of borrowing for payday loans in provinces that regulate them, and each province or territory may add its own rules on fees, licensing, and maximum loan amounts.
Important protections include:
- Licensing requirements: Payday lenders must hold a valid license in the province or territory where they operate.
- Fee limits: The maximum cost of borrowing is generally capped at $14 for each $100 borrowed in regulated provinces.
- Dishonoured payment fees: Lenders may charge a one-time fee if a payment is returned, but this is also typically capped (for example, at $20 in some jurisdictions).
Even with these rules, the loans remain extremely costly. The purpose of regulation is not to make payday loans cheap, but to prevent practices that are considered abusive and to ensure borrowers have at least some basic protections.
Why Payday Loans Are So Risky
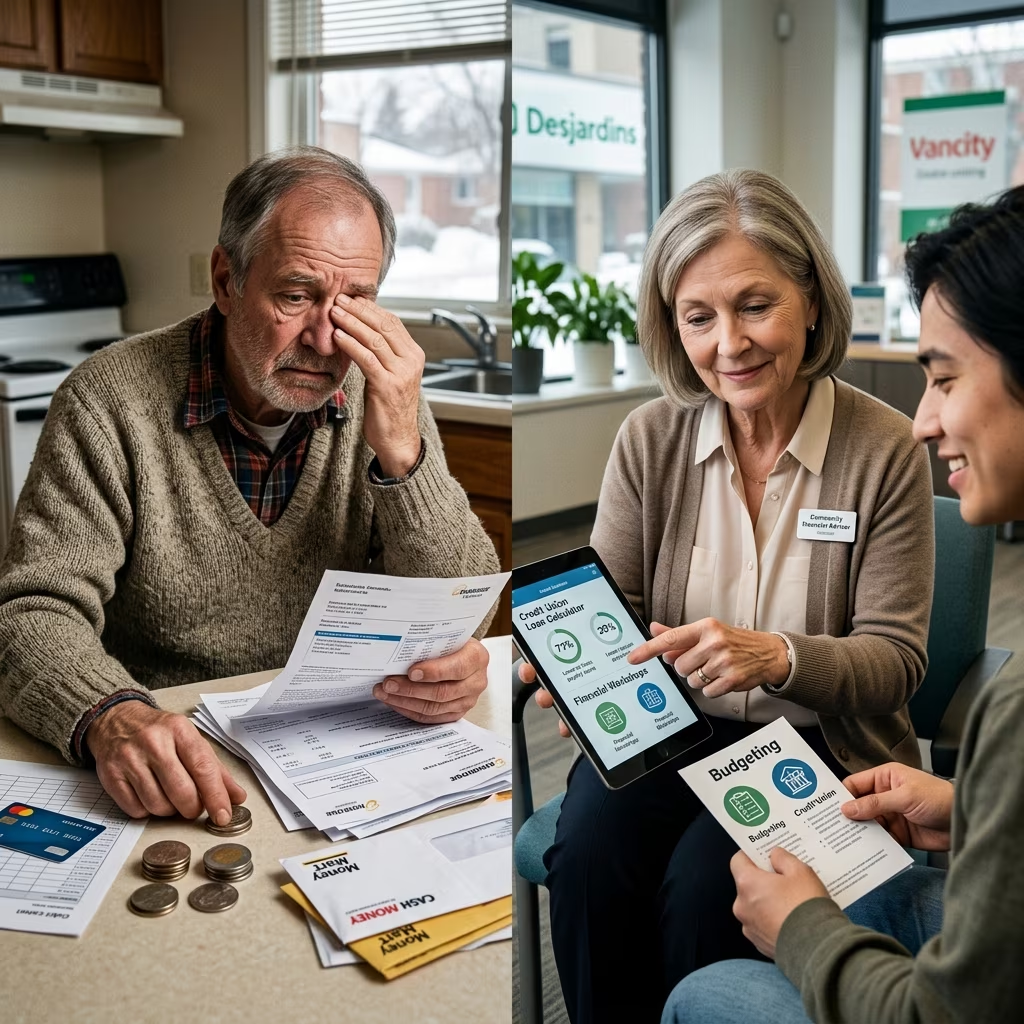
The main risk of payday loans is not that they are hard to get—approval is often fast and easy—but that they are hard to repay without affecting your ability to cover everyday expenses. If you take out a loan and cannot repay it in full on your next payday, you may end up paying additional fees, rolling over the loan, or taking out another loan to cover the first.
Common problems include:
- Debt cycles: Borrowers may repeatedly renew or replace loans, trapping themselves in a pattern of borrowing every pay period.
- Budget strain: Repaying the full amount plus fees on your next paycheque leaves less money for rent, groceries, and bills.
- Additional charges: Missed payments can lead to extra fees and interest, increasing your total debt.
- Limited flexibility: Because lenders often can withdraw funds directly from your account, you may have little control over timing once the due date arrives.
These risks explain why consumer agencies describe payday loans as an expensive way to borrow and warn that they can increase your overall debt if you cannot pay them back on time.
Alternatives to Payday Loans from Banks and Credit Providers
If you need short-term cash, there are often less expensive options than payday lenders. Some Canadian banks and credit unions offer small, short-term products specifically designed to compete with payday loans at much lower costs.
Bank Lines of Credit and Small Loans
Many banks provide:
- Personal lines of credit you can draw on as needed.
- Small installment loans with predictable monthly payments.
Interest rates on these options generally range from just above the bank’s prime rate to around 21% APR, far below the effective 365% APR of typical payday loans. While approval may require a credit check and proof of income, these products are designed to be affordable and manageable over time.
Credit Card Cash Advances
Using a credit card cash advance is not ideal due to fees and relatively high interest. However, when used for a very short period and repaid quickly, it can still be significantly cheaper than a payday loan. Analyses comparing a two-week $300 payday loan with a similar credit card cash advance found that the cash advance could cost a fraction of the payday fee once annualized.
If you choose this option:
- Keep the borrowing small.
- Repay the advance as soon as possible.
- Avoid making new purchases on the card until the advance is cleared.
Newer Alternatives: Cash Advance and Fintech Products
In recent years, financial technology (fintech) companies in Canada have introduced products that provide small amounts of cash ahead of payday without traditional interest charges. These services are often marketed as safer alternatives to payday loans and bank overdrafts, although they still come with fees.
Examples include apps offering:
- 0% interest cash advances with a flat fee for instant access.
- Lines of credit with no interest and small service charges for fast transfers.
Some providers emphasize that federal restrictions on payday loan fees (such as the $14 per $100 cap) still result in very high APRs, and position their products as ways to avoid those costs. While these services can lower your borrowing expense, it is still important to read the terms carefully and ensure that fees are affordable relative to the amount borrowed.
Non-Borrowing Strategies to Cover Short-Term Gaps
Not every cash shortfall has to be solved with a loan. In some situations, non-borrowing strategies may be less stressful and less expensive in the long run. Credit counselling organizations and insolvency firms often recommend exploring these options first.
Examples include:
- Negotiating with creditors: Contact utility providers, landlords, or other creditors to ask for an extension or a temporary payment arrangement.
- Using an emergency fund: If you have savings set aside, this is precisely the kind of situation they are meant for.
- Overdraft protection: Arranging overdraft coverage on your bank account can sometimes cost less than both bounced payments and payday loans.
- Selling items or earning extra income: Short-term side work or selling unused belongings can help cover a temporary gap.
- Family and friends: Borrowing modest amounts informally can sometimes be cheaper, provided everyone clearly understands the repayment plan.
How to Decide If a Payday Loan Is Your Only Option
In some emergencies, you may feel that a payday loan is the only way to keep the lights on or avoid a serious consequence. If you are considering this step, it is important to approach it cautiously and with a plan.
Ask yourself:
- Can I realistically repay the loan in full on my next payday and still cover rent, food, and essential bills?
- Have I compared the cost with alternatives like a small bank loan, line of credit, or cash advance?
- Is the lender licensed in my province or territory?
- What happens if I miss a payment? Understanding extra fees and collection practices is crucial.
If the answer to any of these questions suggests that repayment will be difficult, it is wise to reconsider and explore other strategies, including speaking with a non-profit credit counsellor.
Practical Tips Before Borrowing
If you decide to use a high-cost loan despite the risks, following a few practical steps can reduce the likelihood that a short-term solution becomes a long-term problem.
- Borrow the smallest amount possible: Only cover the immediate emergency, not discretionary spending.
- Create a repayment plan: Map out exactly how the loan will be repaid and which non-essential expenses you may need to cut temporarily.
- Check your bank account timing: Ensure your paycheque arrives before any automatic withdrawal the lender may initiate.
- Review your rights: Look up provincial consumer protection rules so you understand fee caps and licensing requirements.
- Plan for the future: Once the immediate situation is under control, consider building an emergency fund or restructuring your debts to reduce reliance on short-term credit.
Frequently Asked Questions About Payday Loans in Canada
Are payday loans legal in Canada?
Yes. Payday loans are legal, but they are subject to federal and provincial rules. Lenders must be licensed in the province or territory where they operate, and there are caps on the maximum cost of borrowing in jurisdictions that regulate these products.
How much can I borrow with a payday loan?
Loan amounts are typically small. In many regulated provinces, consumers may borrow up to about $1,500, with repayment due within a short period, often no more than 62 days.
Why is the APR on payday loans so high?
Payday lenders charge a flat fee per $100 borrowed rather than a traditional interest rate. When that fee—such as $14 per $100 borrowed—is converted into an annual percentage rate for a loan lasting only a couple of weeks, the APR appears extremely high, often around 365%.
Will a payday lender check my credit?
One reason payday loans are attractive to some borrowers is that approval usually does not depend on a standard credit score. Lenders focus more on proof of income, a bank account, and a permanent address, although practices may vary by company.
What happens if I miss a payday loan payment?
If you cannot repay on time, you may face additional fees and interest charges, and your debt can grow quickly. Some provinces cap dishonoured payment fees (for example, at $20), but you may also incur charges from your bank if the lender’s withdrawal causes an overdraft.
Are cash advance apps safer than payday loans?
Many cash advance apps in Canada advertise 0% interest and position themselves as alternatives to high-cost payday loans and overdraft fees. While they can be cheaper, they still charge service fees, so you should compare costs carefully and make sure you are not becoming dependent on these advances each pay period.
References
- Payday loans — Financial Consumer Agency of Canada. 2024-03-01. https://www.canada.ca/en/financial-consumer-agency/services/loans/payday-loans.html
- Banks and alternatives to payday loans — Canadian Bankers Association. 2023-09-12. https://cba.ca/article/banks-and-alternatives-to-payday-loans
- Payday loan alternatives will cost you less — Yahoo! Finance Canada. 2017-10-19. https://ca.finance.yahoo.com/news/payday-loan-alternatives-will-cost-less-172708394.html
- 5 Best Cash Advance Apps (Canada): Options for 2026 — Bree. 2025-01-10. https://www.trybree.com/post/cash-app-canada
- Loans & apps like iCash for fast funding — Finder Canada. 2024-11-05. https://www.finder.com/ca/payday-loans/loans-like-icash
- 8 alternatives to payday loans — Hoyes Michalos. 2023-06-07. https://www.hoyes.com/blog/8-alternatives-to-payday-loans/