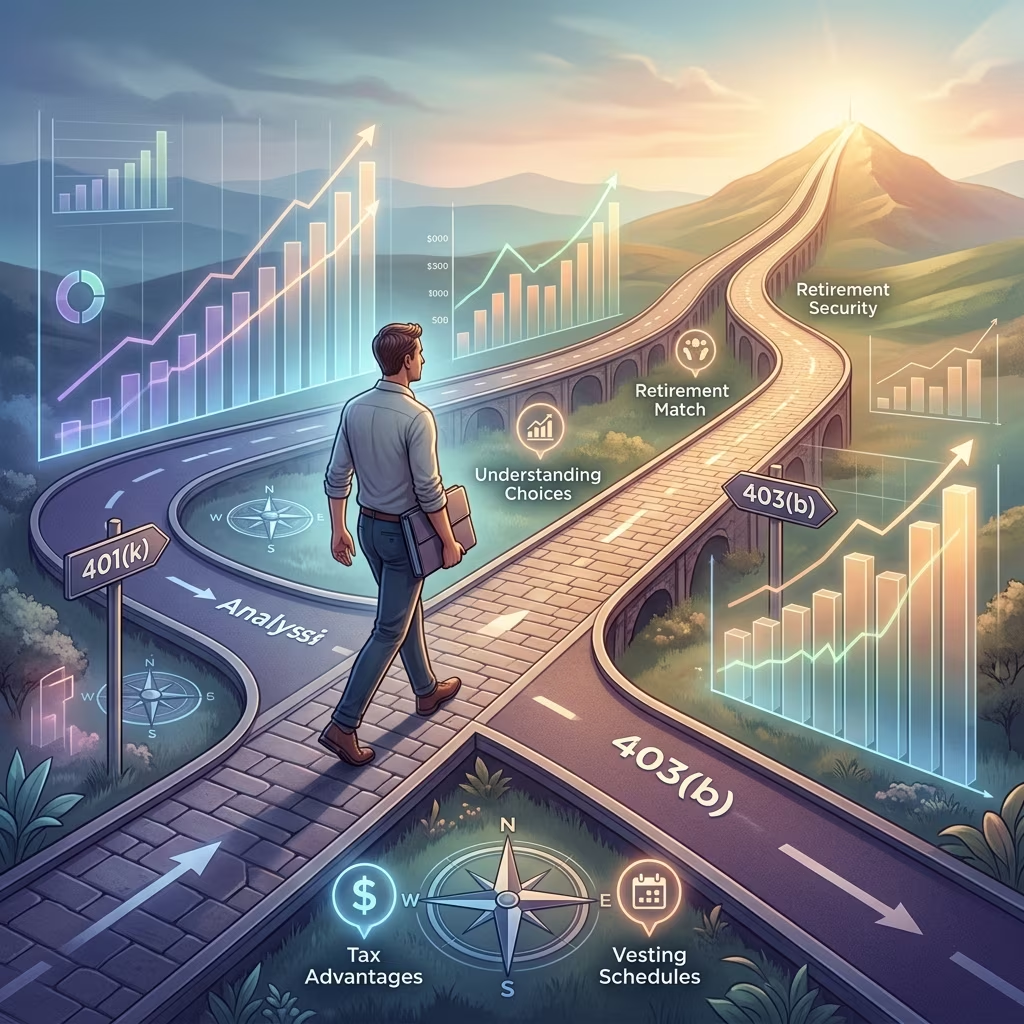
Employer-sponsored retirement plans are one of the most powerful tools available to help you build long-term financial security. Two of the most common plan types are the 401(k) and the 403(b) plan. Although they share many similarities, they are designed for different kinds of employers and have some unique features that can affect how you save.
This guide explains how each plan works, the main differences between them, and practical strategies for using either type to reach your retirement goals.
1. Big Picture: What 401(k) and 403(b) Plans Are
Both 401(k) and 403(b) plans are tax-advantaged workplace retirement plans that allow you to contribute part of your salary into an investment account for your future retirement.
- 401(k): Typically offered by for-profit companies and some tax-exempt organizations.
- 403(b): Typically offered by public schools, certain nonprofit organizations, and some faith-based entities recognized under section 501(c)(3) of the Internal Revenue Code.
Regardless of plan type, the core idea is the same: you reduce your current income by contributing to the plan, invest the money, and let it grow for retirement, usually on a tax-deferred or potentially tax-free basis.
2. Who Can Use Each Plan?
The first key distinction between 401(k) and 403(b) plans is who is eligible, which is driven by the type of employer you work for.
| Plan Type | Typical Employers |
|---|---|
| 401(k) | For-profit companies; some tax-exempt organizations may also offer 401(k) plans. |
| 403(b) | Public schools, colleges, universities; 501(c)(3) charitable organizations; certain churches and faith-based organizations. |
Private-sector, for-profit businesses cannot offer 403(b) plans, but eligible nonprofit and public entities may be able to choose between offering a 401(k) or a 403(b) in some cases.
3. How Contributions Work
In both 401(k) and 403(b) plans, contributions are typically made directly through payroll. You decide how much of your paycheck will go into the plan, and your employer sends that amount to the plan provider.
3.1 Employee Salary Deferrals
Contributions are commonly referred to as salary deferrals. You elect a percentage or fixed dollar amount to be taken from each paycheck and deposited into your account.
- Money contributed to a traditional 401(k or 403(b) is generally pre-tax, meaning you do not pay income tax on it in the year you make the contribution.
- In many plans, you may also have access to a Roth option, which uses after-tax contributions but allows potential tax-free withdrawals later, provided you follow IRS rules.
Because contributions are taken from your paycheck automatically, these plans can make it easier to save consistently without having to manually move money each month.
3.2 Employer Contributions
Many employers offer contributions that supplement what you save yourself. These can significantly accelerate your retirement savings.
- Matching contributions: The employer contributes a percentage of what you put in, up to a limit (for example, 50% of the first 6% of salary you contribute).
- Non-elective contributions: The employer contributes on your behalf even if you do not contribute yourself in some plan designs.
Employer contributions into both 401(k) and 403(b) plans are also generally tax-deferred while in the account.
4. Tax Advantages and Growth
One of the biggest advantages of 401(k) and 403(b) plans is the way they are treated for tax purposes. These plans are designed to encourage long-term saving by offering favorable tax treatment.
4.1 Traditional (Pre-Tax) Contributions
- Your contributions are excluded from your taxable income in the year you make them, lowering your current income tax bill.
- Investments inside the account grow tax-deferred, meaning you do not pay tax on interest, dividends, or capital gains each year.
- When you withdraw money in retirement, those distributions are treated as ordinary income and taxed at your then-current rate.
4.2 Roth Contributions
Many employers now offer Roth versions of 401(k) and 403(b) plans.
- Roth contributions are made with after-tax dollars, so they do not reduce your taxable income in the year of contribution.
- If you meet IRS rules (including a five-year holding period and being at least age 59½ for qualified distributions), earnings can be withdrawn tax-free.
Choosing between traditional and Roth contributions often depends on whether you expect your tax rate to be higher or lower in retirement.
5. Contribution Limits and Catch-Up Rules
The IRS sets annual limits on how much you can contribute to workplace retirement plans. 401(k) and 403(b) plans share similar core limits, but 403(b) plans may have an additional catch-up feature in certain circumstances.
| Feature | 401(k) | 403(b) |
|---|---|---|
| Basic employee contribution limit (example: 2024) | Same core limit as 403(b); participants may contribute up to a fixed IRS amount (e.g., $23,000 in 2024). | Same core limit as 401(k); participants may contribute up to the IRS maximum (e.g., $23,000 in 2024). |
| Age 50+ catch-up | Additional amount allowed for participants age 50 or older (e.g., $7,500 in 2024). | Similar age 50+ catch-up rules; some 403(b) plans may allow an extra long-service catch-up for certain employees. |
Exact dollar amounts change over time, so it is important to check current IRS guidance or your plan materials for the latest limits.
6. Investment Options Inside the Plans
Your retirement plan is not just a savings account; it is an investment account. Over the decades until retirement, how you invest can be just as important as how much you contribute.
- Most plans offer a menu of mutual funds, including stock funds, bond funds, and blended or target-date funds.
- Some 403(b) plans still use annuities as investment vehicles, reflecting their history as tax-sheltered annuity plans.
- Your employer or the plan provider may offer default options, but you generally have the ability to choose and adjust your investments.
Because investment choices and fees can vary widely, reviewing your plan’s materials and, if needed, consulting a financial professional can help you select an appropriate mix for your risk tolerance and time horizon.
7. Withdrawals, Early Access, and Penalties
401(k) and 403(b) plans are built for retirement, so the IRS places restrictions on when you can take money out without penalty.
7.1 Standard Retirement Withdrawals
- In general, distributions from either type of plan before age 59½ may be subject to a 10% early-withdrawal penalty, plus income tax if the money is pre-tax.
- After reaching retirement age, withdrawals are taxed as ordinary income for traditional accounts. Roth accounts may allow tax-free withdrawals when rules are met.
7.2 Special Situations
Both plan types may permit earlier access under specific conditions:
- Separation from service: Some plans allow penalty-free withdrawals after you leave the employer at or after a particular age (for example, age 55 in certain circumstances).
- Hardship distributions: Plans may allow withdrawals for defined hardships, such as preventing eviction or paying certain medical expenses, subject to IRS rules and plan terms.
- Loans: Many plans allow participants to borrow against their account balance up to IRS limits (for example, up to 50% of the account or $50,000, whichever is less).
Using hardship withdrawals or plan loans can undermine long-term growth, so they are generally considered last-resort options.
8. Required Minimum Distributions (RMDs)
To ensure that retirement savings are eventually taxed, the IRS requires many plan participants to begin taking required minimum distributions (RMDs) once they reach a specified age.
- RMD rules apply to both 401(k) and 403(b) plans, though details have changed over time and can vary based on plan history.
- The required amount is determined using IRS life expectancy tables and the total balance in applicable retirement accounts.
- In many cases, participants can delay RMDs from the plan sponsored by their current employer if they continue working past the standard RMD age.
- Failure to take the required amount can result in a substantial tax penalty on the undistributed portion.
403(b) plans can have special RMD considerations for certain older contributions, particularly those made before specific dates, so it is important to review plan documents or IRS guidance.
9. Key Differences Between 401(k) and 403(b)
Although 401(k) and 403(b) plans share much of the same tax structure and overall purpose, there are practical differences that may influence which plan you use or how you use it.
| Aspect | 401(k) | 403(b) |
|---|---|---|
| Employer type | Primarily for-profit companies, plus some tax-exempt organizations. | Public schools, certain nonprofits, and some churches/faith-based organizations. |
| Historical structure | Workplace retirement plan under ERISA with a broad investment menu. | Originally created as tax-sheltered annuity plans; still commonly use annuities and mutual funds. |
| Plan design flexibility for employers | Widely used in corporate settings; extensive design options for profit-sharing, matching, and automatic features. | Often tailored to educational and nonprofit environments; may include special catch-up provisions based on years of service. |
From an individual saver’s perspective, the everyday experience of contributing and investing may feel very similar, regardless of whether your plan is a 401(k) or a 403(b).
10. Practical Strategies to Maximize Your Plan
Whether you have a 401(k) or a 403(b), using the plan effectively can make a large difference in your future financial security.
10.1 Start Early and Contribute Regularly
- Begin contributions as soon as you are eligible, even if the amount is modest.
- Increase your contribution rate when you receive raises or bonuses.
- Consider setting a long-term goal, such as saving a specific percentage of your income.
10.2 Capture the Full Employer Match
- Review your plan documents to understand how your employer match works.
- Try to contribute at least enough to receive the maximum match; otherwise, you may be leaving money on the table.
10.3 Choose Investments Thoughtfully
- Use diversified funds, such as broad stock and bond funds, to spread risk.
- Consider target-date funds as a simple way to invest if you prefer professional allocation based on your expected retirement year.
- Review your investment mix periodically and adjust if your goals or circumstances change.
10.4 Understand Your Plan’s Fees
- Compare expense ratios for funds offered in your menu.
- Be aware of administrative or recordkeeping fees that may reduce net returns.
10.5 Coordinate With Other Retirement Accounts
- If you have IRAs or other workplace plans from previous employers, consider how they fit with your current strategy.
- Rollovers may help you consolidate accounts, but pay attention to preserving tax advantages and avoiding early withdrawal penalties.
11. Frequently Asked Questions (FAQs)
Q1: Is a 403(b) better than a 401(k)?
Neither plan is inherently better; they serve similar purposes. The main differences relate to employer type, some plan design features, and historical use of annuities in 403(b) plans. For most employees, the quality of the specific plan—fees, investment options, and employer contributions—matters more than the label.
Q2: Can I have both a 401(k) and a 403(b)?
In some situations, people who work for more than one eligible employer or change jobs may end up with both types of accounts during their careers. Each plan is subject to IRS contribution limits, and combined limits may apply, so it is important to check current rules and coordinate contributions carefully.
Q3: What happens to my plan when I change jobs?
If you leave an employer, your 401(k) or 403(b) plan may allow you to keep the account where it is, roll it over to a new employer’s plan, or transfer it to an individual retirement account (IRA). Distributions that are paid directly to you instead of being rolled over can be taxable and may incur penalties if you are under the applicable age threshold.
Q4: Are my retirement plan contributions protected from creditors?
401(k) plans are generally subject to federal protections under ERISA, while 403(b) plans may have different protections depending on whether they are covered plans and on state law. For detailed protection rules, legal advice or specific regulatory guidance may be needed.
Q5: How do I know if I should choose Roth or traditional contributions?
The choice depends on your current and expected future tax situation. Traditional contributions reduce your taxable income now but lead to taxable withdrawals later, whereas Roth contributions do not lower current taxes but may provide tax-free income in retirement if IRS requirements are met. Many savers use a combination of both to diversify tax treatment.
References
- IRC 403(b) Tax-Sheltered Annuity Plans — Internal Revenue Service. 2024-03-15. https://www.irs.gov/retirement-plans/irc-403b-tax-sheltered-annuity-plans
- What Is a 403(b)? — Fidelity Investments. 2023-11-01. https://www.fidelity.com/learning-center/smart-money/what-is-a-403b
- 401(k) vs 403(b): What’s the Difference? — Fidelity Investments. 2023-10-10. https://www.fidelity.com/learning-center/smart-money/401k-vs-403b
- IRC 403(b) Tax-Sheltered Annuity Plans — Internal Revenue Service. 2024-03-15. https://www.irs.gov/retirement-plans/irc-403b-tax-sheltered-annuity-plans
- What Are the Differences Between 401(k) and 403(b) Plans? — National Council on Aging. 2024-02-20. https://www.ncoa.org/article/what-are-the-differences-between-401-k-and-403-b-plans/
- 401(k) vs. 403(b) Plans: Key Differences for Employers — J.P. Morgan. 2023-07-18. https://www.jpmorgan.com/insights/retirement/401k-vs-403b-plans-key-differences-for-employers
- What to Know About 401k and 403b Retirement Plans — GreenPath Financial Wellness. 2023-09-05. https://www.greenpath.com/blog/401k-403b-retirement-plans/