When you sell highly appreciated real estate, the resulting capital gains tax can significantly erode your profit. Understanding lawful strategies to defer, reduce, or in some cases avoid capital gains can help you preserve more of your wealth and reinvest efficiently. This guide explains major planning tools, their legal framework, and the vital role of tax and legal professionals in structuring these transactions.
Understanding Capital Gains Tax on Real Estate
Capital gains tax arises when you sell a property for more than your adjusted basis, which is generally your original cost plus allowable improvements minus any depreciation and certain deductions. Long-term gains (for property held longer than one year) are typically taxed at preferential federal rates, but large gains can still generate a sizeable tax bill.
Key Concepts Before You Plan
- Basis: Usually the purchase price plus closing costs and capital improvements, minus depreciation and certain write-offs.
- Amount realized: The gross sale price minus selling expenses such as commissions and transfer taxes.
- Capital gain: Amount realized minus adjusted basis; this is the number your tax planning strategies aim to manage.
- Holding period: Whether the gain is short-term or long-term, which affects the applicable tax rate.
Real estate investors often look for ways to delay recognizing this gain, allowing them to keep more capital working in new investments. Several legal mechanisms can accomplish that deferral if they are carefully structured and documented.
Primary Residence vs. Investment Property
The available tax tools differ dramatically depending on whether the property is your main home or an investment or business asset. The Internal Revenue Code gives special treatment to a taxpayer’s principal residence via a home sale exclusion, while strategies like 1031 exchanges focus on investment or business property.
| Property Type | Typical Tax Treatment | Common Deferral/Reduction Strategies |
|---|---|---|
| Main home (principal residence) | May qualify for exclusion of up to $250,000 (single) or $500,000 (married filing jointly) of gain if ownership and use tests are met. | Home sale exclusion; timing of sale; partial installment sale. |
| Rental or commercial investment property | Generally fully taxable gain unless you use a qualified deferral or reduction strategy. | 1031 exchange, installment sale, deferred sales trust, charitable remainder trust, step-up in basis. |
| Mixed-use or vacation property | Complex rules; portions may be eligible for different treatments depending on actual use. | Segregation of use, potential partial 1031 treatment, or home sale exclusion on qualifying use. |
The Home Sale Exclusion
For your primary residence, federal law allows many homeowners to exclude a substantial portion of the gain when they sell. If you meet both the ownership and use tests—generally having owned and lived in the home for at least two of the five years prior to the sale—you may exclude up to $250,000 of gain if you are single or $500,000 if you are married filing jointly.
- You must meet both the ownership and use tests in the five-year window preceding the sale.
- The exclusion is generally available only once every two years.
- If your gain exceeds the applicable limit, the excess may still be taxable.
Even when you use the exclusion, you may still be able to spread recognition of any remaining gain through an installment sale structure, though you must report and document the transaction accurately.
Major Strategies to Defer Capital Gains on Investment Real Estate
Owners of rental, commercial, or other investment property have several commonly used strategies to manage capital gains. Each technique comes with strict rules and potential pitfalls, making professional guidance essential.
1. 1031 Like-Kind Exchanges
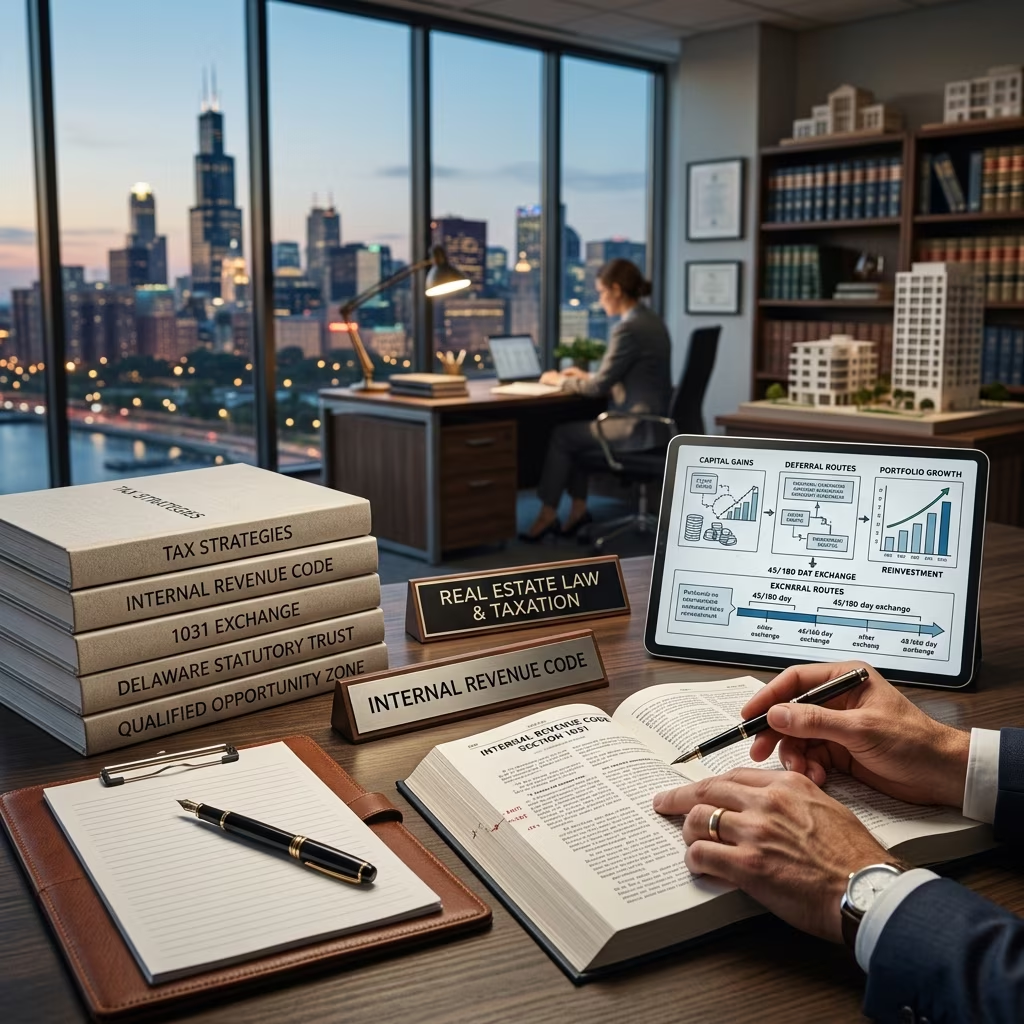
A 1031 exchange, named after Internal Revenue Code Section 1031, allows taxpayers to defer capital gains taxes by exchanging one business or investment property for another of “like-kind”. Rather than selling and paying tax immediately, you reinvest the proceeds into a replacement property and defer the gain into the future.
Core Requirements for a Valid 1031 Exchange
- Like-kind property: Both relinquished and replacement assets must be held for business or investment purposes; personal residences or vacation homes used solely for personal enjoyment do not qualify.
- Value and debt: To fully defer tax, the replacement property (or properties) must be of equal or greater value, and you generally must reinvest all net proceeds and maintain or increase your level of debt.
- Strict timelines: You have 45 days from the sale to identify potential replacement property and 180 days to close on the replacement acquisition.
- Use of a qualified intermediary (QI): You cannot receive, control, or temporarily hold the sale proceeds; a QI must hold funds in escrow and facilitate the exchange.
When properly executed, a 1031 exchange allows you to roll your gain into the new property rather than recognizing it immediately. This can be especially powerful for long-term portfolio growth, although the deferred gain and depreciation are “built into” the replacement property’s basis.
Practical Tips for 1031 Exchanges
- Document rental activity to substantiate that property is held for investment, including leases and payment records.
- Consider separate legal entities, such as LLCs, to keep investment holdings distinct from personal-use property.
- Work with a CPA or attorney who regularly handles 1031 exchanges; the rules are technical and mistakes can trigger immediate taxation.
2. Installment Sales
An installment sale occurs when you receive the sale price in periodic payments over time rather than in a single lump sum. Under the installment method, the portion of gain associated with each payment is recognized in the year that payment is received, effectively spreading tax liability across multiple years.
This method does not eliminate capital gains—it shifts them into future years, which may help you manage your tax brackets, cash flow, or anticipated changes in your overall income.
- Seller and buyer agree to a structured payment plan (for example, monthly or annual installments).
- Each payment consists of principal (return of basis), gain, and potentially interest; only the gain portion is subject to capital gains tax.
- The installment method can be used for both investment property and, in some circumstances, property that also benefits from the home sale exclusion.
Because installment contracts create ongoing legal and financial relationships between buyer and seller, they should be drafted with robust protections, including provisions for default, security interests, and tax reporting obligations.
3. Deferred Sales Trusts and Similar Structures
Some owners of appreciated property use specialized trust arrangements, such as a deferred sales trust, to postpone recognizing capital gains. In these structures, the property is sold to a trust, which then sells it to the ultimate buyer. The seller receives payments from the trust over time, deferring recognition of gain as long as principal remains within the trust and is reinvested.
Key concepts include:
- Sale of the property to the trust rather than directly to the buyer.
- Reinvestment of proceeds within the trust, which may hold diversified assets.
- Tax on capital gains generally becoming due only as you receive principal distributions, not while funds remain invested in the trust.
These strategies are complex and must be carefully analyzed against IRS rules, case law, and individual circumstances. They are not suitable for every seller and typically require coordination among tax counsel, financial advisors, and trustees.
4. Charitable Planning Tools
Philanthropically inclined property owners may use charitable approaches to reduce or defer capital gains while benefiting causes they care about. Common tools include:
- Outright charitable donation of property: Donating appreciated real estate to a qualifying charity may allow you to avoid capital gains tax on the appreciation while obtaining a charitable deduction, subject to IRS limitations.
- Charitable remainder trust (CRT): You transfer the property to a CRT, which sells it without immediate capital gains tax at the individual level, then pays you or other beneficiaries an income stream. Remaining assets eventually pass to charity.
- Partial gift and partial sale: Combining donation with sale can produce both a charitable deduction and partial gain recognition.
Charitable strategies involve complex valuation rules and compliance requirements, and they are typically most effective for high-value properties and long-term planning horizons.
5. Relying on Step-Up in Basis at Death
Holding appreciated real estate until death may result in a “step-up” in basis for heirs. Under current law, inherited property’s basis is generally adjusted to fair market value at the date of death, which can significantly reduce or eliminate capital gains if heirs later sell the property.
This approach is not a deferral strategy in the transactional sense but a broader estate planning decision. It may be combined with other techniques, such as 1031 exchanges during life, followed by step-up at death, to minimize lifetime and intergenerational tax exposure.
Critical Legal and Compliance Considerations
All of the strategies described above operate within a detailed legal and regulatory framework. Missteps can turn what was intended to be a tax-deferral plan into a taxable event.
Documentation and Substantiation
- Accurate records of basis: Keep settlement statements, receipts for improvements, and depreciation schedules to establish your adjusted basis.
- Evidence of property use: For rentals or business properties, retain leases, rent rolls, and bank records demonstrating investment use; this is especially important for 1031 exchanges.
- Written agreements: Installment contracts, trust documents, and exchange agreements should be thoroughly drafted and executed.
Reporting Requirements
The IRS makes clear that even when exclusions or deferrals apply, many real estate transactions must be properly reported. For example, if you cannot exclude all of your gain on a principal residence, you generally must report the sale using Schedule D (Form 1040) and Form 8949. Investment property transactions often require additional forms and disclosures, particularly in installment sales and complex trust or exchange structures.
Why Professional Legal Help Is Essential
While the basic concepts behind tax deferral might sound straightforward, the implementation is rarely simple. Working with professionals can be the difference between a successful strategy and an expensive mistake.
Roles of Key Advisors
- Tax attorneys: Interpret complex IRS rules, draft legal documents, and advise on risk and compliance when using advanced strategies like deferred sales trusts or CRTs.
- Certified public accountants (CPAs): Model tax outcomes, prepare required returns and forms, and ensure consistent accounting treatment over many years.
- Real estate attorneys: Review purchase agreements, installment contracts, and exchange documents, and address state-level property law issues.
- Financial advisors: Help integrate tax strategies with investment objectives, cash flow needs, and retirement or estate planning.
Questions to Ask a Prospective Advisor
- How many 1031 exchanges or installment sales have you handled in the past few years?
- Are you familiar with both federal and state tax rules affecting real estate gains?
- Can you coordinate with my other advisors to align tax planning with broader financial goals?
- How do you charge for your services, and what level of ongoing support do you provide?
Strategic Planning: Matching Tools to Your Goals
No single solution is appropriate for every property owner. Effective planning requires clarifying your objectives and constraints, then choosing the strategy or combination of strategies that best fits your situation.
Common Objectives
- Maximize reinvestable capital by deferring immediate taxes through 1031 exchanges or trusts.
- Smooth income over time via installment sales or annuity-like trust distributions.
- Support heirs by planning for step-up in basis and minimizing taxable gain upon inheritance.
- Advance philanthropic goals while capturing tax benefits through charitable gifts or CRTs.
In many cases, property owners use a layered approach—for example, executing multiple sequential 1031 exchanges during their lifetime and relying on step-up in basis at death to reduce or eliminate remaining gains for heirs. Others combine a partial 1031 exchange with an installment sale or charitable component. Each layering decision should be vetted carefully to avoid unintended tax consequences.
FAQs: Capital Gains Deferral on Real Estate
Can I avoid capital gains tax by simply buying another house?
Buying another property does not automatically eliminate capital gains tax. To qualify for deferral under a 1031 exchange, you must follow specific IRS rules: the property must be held for investment or business purposes, be like-kind, and meet strict timelines and intermediary requirements. Personal-use homes generally do not qualify.
Is a 1031 exchange available for my principal residence?
No. 1031 exchanges apply to property held for business or investment purposes, not to your main home. Principal residences may instead qualify for the home sale exclusion of up to $250,000 or $500,000 of gain, subject to ownership and use tests.
Do I still owe tax if I use an installment sale?
Yes. Installment sales defer when you pay the tax but do not cancel it. You recognize a portion of the gain each year as you receive payments, which can help manage your tax bracket and cash flow.
Are deferred sales trusts approved by the IRS?
Deferred sales trusts are a planning concept rather than a single standardized product. Their effectiveness and compliance depend entirely on how the transaction is structured and documented in light of existing law and IRS guidance. You should seek independent legal and tax counsel before using any such arrangement.
Is holding property until I die always the best tax strategy?
Not necessarily. While step-up in basis can be valuable, decisions about holding or selling property should reflect your cash needs, risk tolerance, estate goals, and regulatory uncertainty. Comprehensive financial and legal planning is essential.
References
- Deferral of Capital Gains Tax vs. Step-Up in Basis — DK Law Group. 2023-04-10. https://www.dklawmd.com/blog/deferral-of-capital-gains-tax-vs-step-up-in-basis
- Capital Gains Tax Deferral – Deferred Sales Trust — Freedom Bridge Capital. 2022-09-01. https://www.freedombridgecapital.com/capital-gains-tax-deferral.htm
- What Are 5 Ways to Defer Taxes on Highly Appreciated Real Estate? — DHC Legal. 2023-01-15. https://dhclegal.com/what-are-5-possible-solutions-to-defer-taxes-on-highly-appreciated-real-estate/
- Deferring Taxes on Investment Property Sale: 1031 Exchange — Charles Schwab. 2023-05-05. https://www.schwab.com/learn/story/deferring-taxes-on-investment-property-sale
- Topic No. 701, Sale of Your Home — Internal Revenue Service. 2024-03-01. https://www.irs.gov/taxtopics/tc701