Probate is the court-supervised process used to validate a will, settle debts, and distribute property after death. For many families, that process adds delay, expense, and public administration to a time that is already difficult. There are lawful ways to structure property ownership and beneficiary arrangements so that at least some assets transfer outside probate.
The best approach is rarely a single document. In practice, avoiding probate usually depends on combining several planning tools and keeping account titles, deeds, and beneficiary forms aligned with your wishes.
Why Many People Try to Avoid Probate
People often want to bypass probate because it can be slow and procedural. Assets that must pass through court may not reach heirs immediately, and the process can require filings, notices, and formal oversight.
Probate can also make estate details part of the public record, which is another reason some people prefer private transfer methods such as trusts or beneficiary designations.
- It may delay distributions to heirs.
- It can increase administrative work for the personal representative.
- It may expose estate information to public review.
- It can create avoidable friction if documents are outdated or inconsistent.
Use a Revocable Living Trust for Broad Probate Avoidance
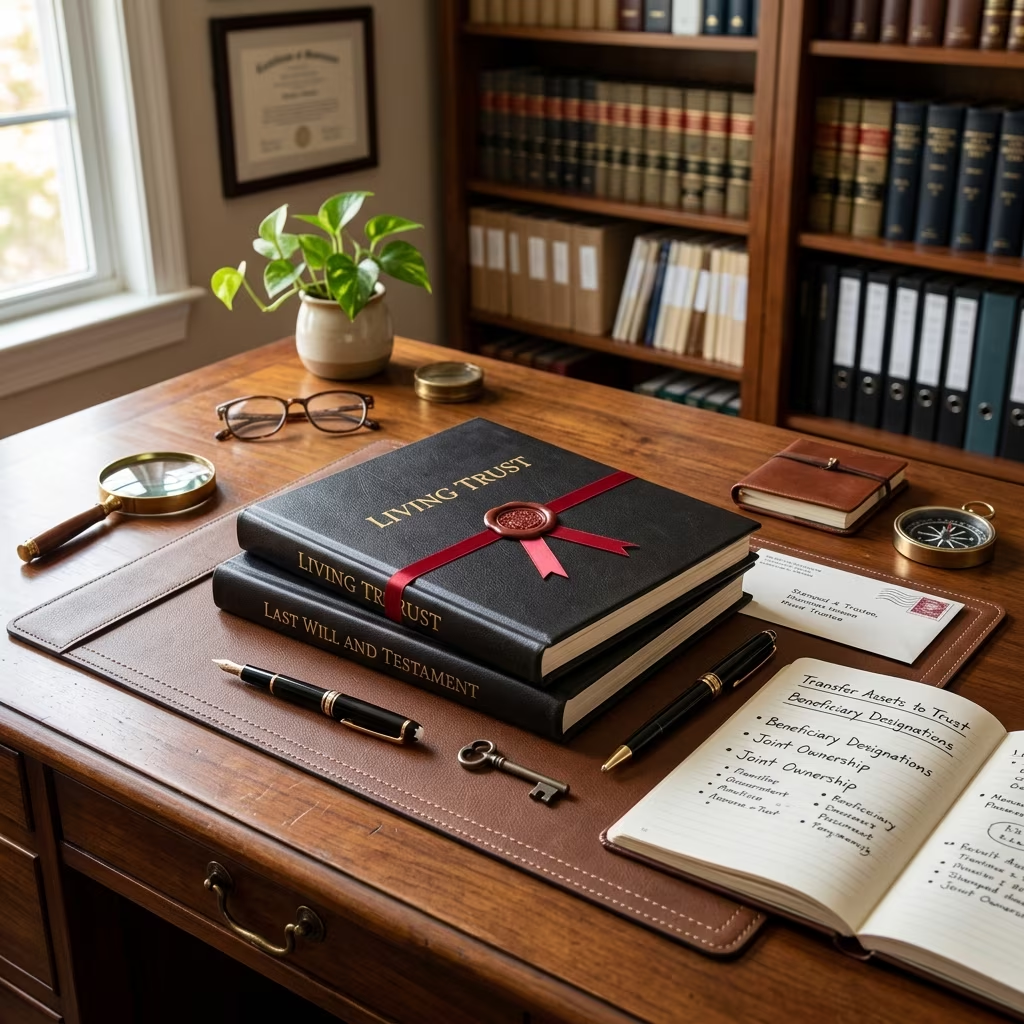
A revocable living trust is one of the most flexible ways to keep property out of probate. When assets are properly transferred into the trust during life, the trustee can manage them without court involvement after death.
This structure is attractive because the person creating the trust can usually remain in control while alive, then name a successor trustee to distribute the property later according to written instructions.
That said, a trust works only for assets that are actually placed into it. If a home, account, or other property is left outside the trust, that asset may still need to go through probate.
| Feature | Why it matters |
|---|---|
| Control during life | The trust creator can often keep managing the property. |
| Transfer at death | Assets in the trust may move directly to beneficiaries. |
| Funding requirement | Assets must be retitled or assigned to the trust to be effective. |
Rely on Beneficiary Designations Where They Are Available
Many financial products pass directly to named beneficiaries outside probate. Retirement plans, life insurance, and certain bank or investment accounts commonly allow both primary and contingent beneficiaries to be listed.
This method is simple, but it only works well when forms are current. If beneficiary designations are outdated, missing, or inconsistent with the rest of the estate plan, the result can be confusion or unintended transfers.
- Retirement accounts such as IRAs and 401(k)s often allow direct beneficiary transfer.
- Life insurance proceeds usually pass to the named beneficiary without probate.
- Bank accounts may be set up with payable-on-death instructions.
- Investment accounts may permit transfer-on-death designations.
Because beneficiary forms operate separately from a will, it is important to review them regularly and after major life events such as marriage, divorce, birth, death, or a move to another state.
Consider Joint Ownership for Select Assets
Joint ownership can avoid probate when the property is structured with a right of survivorship. In that setup, the surviving owner automatically becomes the sole owner at death.
This approach is common for homes, bank accounts, and some other assets. It can be efficient, but it is not always the best fit because adding another owner gives that person legal rights in the asset during life as well.
Married couples may also use tenancy by the entirety in states that recognize it, which is similar to joint tenancy but limited to spouses in many jurisdictions.
- Ownership can transfer automatically to the surviving owner.
- It may simplify transfer of a home or account.
- It can create risk if the added owner has creditor, tax, or family-law problems.
Use Transfer-on-Death and Payable-on-Death Tools
Transfer-on-death and payable-on-death designations are useful because they let the owner keep full control while alive and still direct the asset to a beneficiary at death.
POD designations are commonly used for bank accounts and certificates of deposit. TOD designations are often available for securities and, in some states, real estate or vehicles.
These tools are especially helpful for people who want a simple solution for one asset or a small group of assets without creating a full trust.
Do Not Assume a Will Alone Will Prevent Probate
A will is an important estate-planning document, but it does not generally avoid probate. Instead, it directs how probate property should be distributed once the court process begins.
That distinction matters. If the main goal is to keep assets out of court, a will can be part of the plan, but it should not be treated as the main probate-avoidance tool.
Real Estate Often Requires Extra Attention
Homes are among the most valuable assets in an estate, so they deserve special planning. A home may be kept out of probate by placing it in a properly funded trust, by using a TOD deed where state law allows it, or by arranging another ownership structure that transfers automatically at death.
If the deed, trust, and beneficiary plan do not match, the house may still end up in probate even if other assets pass smoothly.
For that reason, homeowners should review the deed language carefully and confirm that the transfer method is valid under state law.
Match Every Document to the Same Overall Plan
The most common mistake in probate planning is inconsistency. A trust may say one thing, a beneficiary form another, and a deed something else entirely.
A coordinated plan usually includes:
- A trust, if used, that is properly funded with the intended assets.
- Beneficiary forms that are current and complete.
- Deeds and account titles that reflect the intended transfer method.
- A will that handles any property left outside the other tools.
Periodic review is essential because life changes and asset changes can quietly undo a carefully built plan.
When Probate Avoidance Can Be Especially Useful
Probate avoidance is not only for large estates. It can be useful for anyone who wants a simpler transfer process, wants to reduce administrative burdens on loved ones, or owns assets that are well suited to nonprobate transfer tools.
It may be particularly helpful when an estate includes multiple account types, a home, retirement plans, or inherited property that should move quickly to a spouse, child, or other chosen beneficiary.
Common Mistakes That Can Put Assets Back Into Probate
Even well-intentioned planning can fail if the details are not maintained. The most common breakdowns are usually administrative rather than legal.
- Failing to retitle assets into a trust.
- Leaving beneficiary forms blank or outdated.
- Assuming a will overrides account designations.
- Adding joint owners without considering the broader consequences.
- Neglecting state-specific rules for TOD deeds or similar transfers.
Frequently Asked Questions
What is the simplest way to avoid probate?
For many people, the simplest approach is to use beneficiary designations on accounts that allow them, along with a trust or TOD/POD tools for assets that need extra planning.
Does a revocable living trust avoid probate automatically?
No. The trust can avoid probate only for assets that are actually transferred into it during life and properly maintained afterward.
Can a house avoid probate?
Yes, in many cases. A house may avoid probate if it is placed in a trust, titled with survivorship rights, or transferred through a TOD deed where state law permits it.
Do beneficiary designations override a will?
Generally, yes. Assets with valid beneficiary forms usually pass according to those designations rather than under the will.
Should every asset be placed in joint ownership?
No. Joint ownership can be effective for some assets, but it also gives the co-owner present legal rights and may create unintended risks.
Building a Practical Probate-Reduction Plan
A good probate-reduction strategy starts with an inventory of assets and how each one is titled. From there, the owner can decide which items belong in a trust, which should use beneficiary forms, and which might be best handled through joint ownership or a deed-based transfer.
That process should also include regular review. Changes in family structure, financial accounts, residence, and state law can alter the effectiveness of a plan over time.
When the documents work together, the result is usually a smoother transition for heirs and less dependence on court supervision.
References
- How to Avoid Probate: 4 Legal Methods to Bypass the Lengthy Court Process — Heartland Estate Law. 2025-01-01. https://heartlandestatelaw.com/blog/how-to-avoid-probate-4-legal-methods-to-bypass-the-lengthy-court-process/
- Estate Planning: How to Avoid Probate — Farm Bureau Financial Services. 2024-01-01. https://www.fbfs.com/learning-center/estate-planning-how-to-avoid-probate
- 5 Reasons to Avoid Probate — and How to Do It — LifeGen Law Group. 2024-01-01. https://www.lifegenlawgroup.com/5-reasons-to-avoid-probate-and-how-to-do-it/
- Avoiding Probate: A Guide for Annapolis Residents — Hartman. 2025-09-01. https://www.hartman.law/blog/2025/september/avoiding-probate-a-guide-for-annapolis-residents/
- How to Structure Your Estate to Avoid Probate — EP Wealth Advisors. 2024-01-01. https://www.epwealth.com/blog/estate-structure-avoid-probate
- Common Misconceptions in Estate Planning: Wills Avoid Probate — Amundsen Davis. 2024-01-01. https://www.amundsendavislaw.com/alert-common-misconceptions-in-estate-planning-wills-avoid-probate