
How Companies Should Handle CFPB Consumer Complaints
A practical, step‑by‑step guide for financial companies responding to CFPB consumer complaints effectively and compliantly.
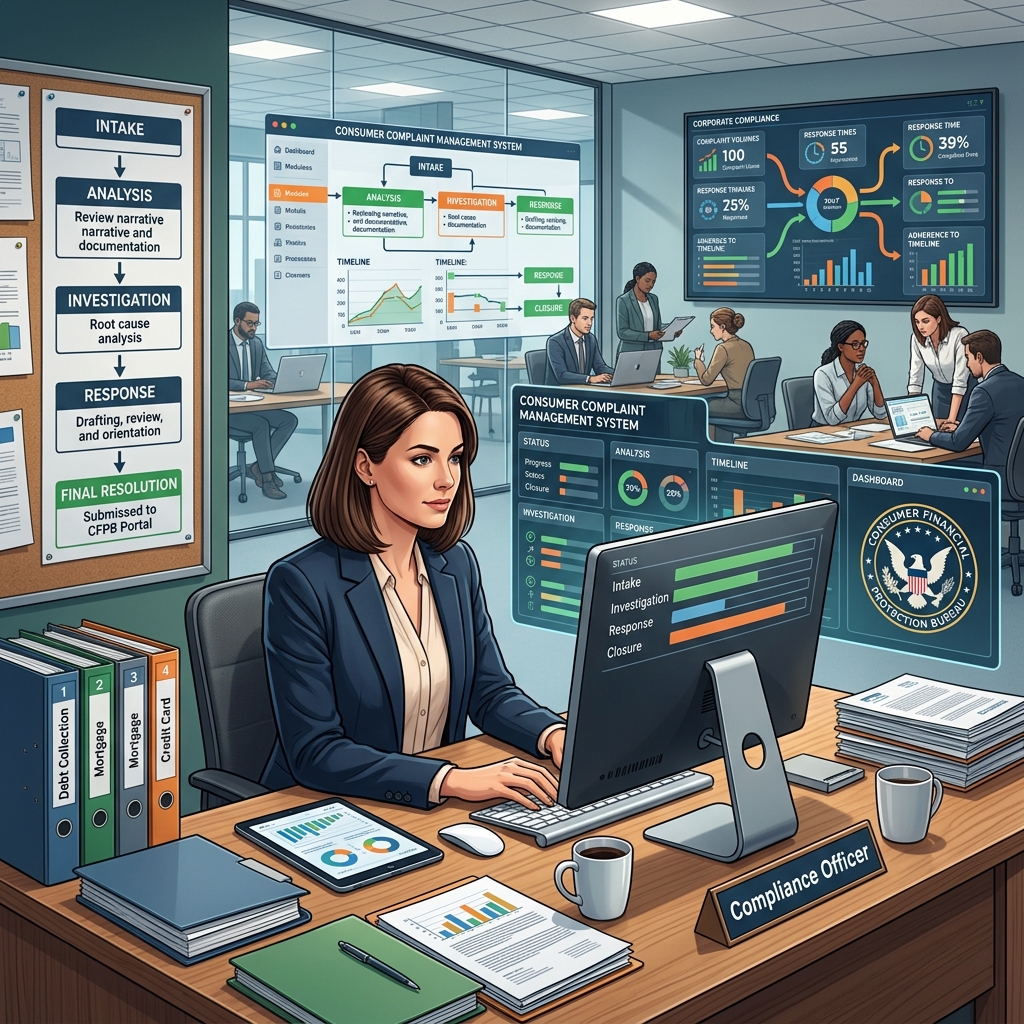
When a consumer files a complaint with the Consumer Financial Protection Bureau (CFPB), the CFPB often forwards that complaint to the company named and expects a timely, meaningful response. For financial institutions and other covered companies, having a disciplined process for handling these complaints is essential to meet regulatory expectations, manage reputational risk, and improve customer relationships.
This article explains, in practical and detailed terms, how companies should manage CFPB complaints from the moment they receive a notification through investigation, response, remediation, and long-term process improvement.
1. Understanding the CFPB Complaint Ecosystem
The CFPB operates a national platform where consumers can submit complaints about a wide range of financial products and services, including bank accounts, credit cards, mortgages, debt collection, and more. The Bureau then routes these complaints to the relevant company when possible and tracks how the company responds.
1.1 Why CFPB Complaints Matter to Companies
CFPB complaints are not simply customer service tickets. They are also compliance and regulatory signals. Patterns in complaints can influence supervisory attention and, in some circumstances, enforcement priorities. Taking each complaint seriously helps companies:
- Reduce regulatory risk by resolving issues that could indicate broader violations.
- Protect reputation by showing responsiveness to consumers and regulators.
- Identify systemic problems in products, disclosures, or servicing practices.
- Improve customer trust through fair and transparent resolutions.
1.2 How Complaints Reach Your Company
When a complaint is submitted to the CFPB and the Bureau determines your company is the appropriate recipient, the complaint is forwarded via the CFPB’s secure company portal or through other agreed-upon channels. The CFPB expects your company to:
- Review the complaint details and documents.
- Provide a response that addresses the consumer’s issues.
- Indicate what steps were taken to resolve or investigate.
2. Building a Robust Internal Complaint-Handling Framework
Effective handling of CFPB complaints starts with an internal framework that clearly defines roles, responsibilities, and procedures. Many financial institutions treat this as part of their broader complaint management or compliance management system, consistent with CFPB supervisory expectations.
2.1 Key Components of a Strong Framework
- Clear ownership of the CFPB portal and incoming complaints (often a compliance or complaint-management team).
- Written procedures describing intake, routing, investigation, communication, recordkeeping, and escalation.
- Defined timelines aligned with the CFPB’s expectations for prompt responses.
- Quality control and oversight to ensure responses are accurate, consistent, and appropriately documented.
2.2 Roles and Responsibilities
| Role | Typical Responsibilities for CFPB Complaints |
|---|---|
| Complaint Intake / Portal Administrator | Monitors CFPB portal, downloads new complaints, logs them, and routes to appropriate teams. |
| Operations / Business Unit | Reviews account-level information, gathers records, and proposes factual findings and resolution options. |
| Compliance / Legal | Assesses regulatory and legal risks, ensures responses are accurate, complete, and consistent with policy. |
| Senior Management | Oversees trends, approves high-risk responses, and supports remediation of systemic issues. |
| Quality Assurance / Audit | Performs periodic reviews of responses and underlying processes to ensure integrity and effectiveness. |
3. Intake: What to Do When You Receive a CFPB Complaint
Once your company receives a complaint from the CFPB portal, a disciplined intake process is crucial. Prompt action not only supports timely resolution but also demonstrates respect for the consumer and seriousness toward regulatory obligations.
3.1 Immediate Steps on Receipt
At a minimum, the intake team should:
- Log the complaint in an internal tracking system with a unique identifier and the CFPB complaint number.
- Verify the company match to ensure the complaint is correctly directed to your entity and business line.
- Identify key details such as product type, alleged issue, relevant dates, and requested resolution.
- Check for attachments provided by the consumer (statements, letters, emails, contracts) and store them securely.
- Assign ownership to an investigator or case manager who will coordinate the response.
3.2 Prioritization and Risk Flagging
Some complaints may require heightened attention due to potential legal or safety implications. During intake, consider flagging complaints that involve:
- Allegations of fraud, identity theft, or scams.
- Possible discrimination or unfair treatment.
- Large-dollar losses or imminent harm.
- Vulnerable consumers, such as older adults or people with disabilities.
Flagged cases may warrant expedited handling, additional legal review, or coordination with specialized teams such as fraud or security.
4. Investigating the Consumer’s Concerns
An effective investigation is at the core of a credible CFPB complaint response. The goal is to reconstruct what happened, evaluate whether policies and laws were followed, and determine what, if any, remediation is appropriate.
4.1 Gathering Facts
The investigator should gather internal and external information relevant to the complaint, including:
- Account histories, statements, transaction records, and call logs.
- Copies of disclosures, agreements, and notices provided to the consumer.
- Internal notes from prior customer service contacts, including any previous complaints.
- Communications and documents submitted by the consumer to the CFPB.
4.2 Evaluating Compliance and Policy Adherence
The investigation should not only confirm facts but also evaluate whether the company’s actions were consistent with:
- Applicable federal consumer financial laws (such as the Truth in Lending Act, Fair Credit Reporting Act, or Equal Credit Opportunity Act).
- Implementing regulations and official guidance.
- Internal policies, procedures, and service standards.
Because CFPB complaints often highlight potential legal issues, coordination with compliance and legal teams is important, especially where the complaint involves complex products, specialized regulations, or potential systemic issues.
4.3 Determining Root Causes
Beyond answering the question of whether the company was technically correct, investigators should consider why the issue occurred. Root-cause analysis helps determine whether the matter is:
- An isolated error (for example, a one-time processing mistake).
- A training gap (such as staff misunderstanding a policy).
- A system or operational issue (like a recurring calculation error).
- A product or disclosure problem (where terms are confusing or incomplete).
Understanding root cause helps inform both the specific case resolution and any broader remediation.
5. Crafting a Clear, Accurate, and Respectful Response
Once the investigation is complete, the company must prepare a response through the CFPB portal that addresses the consumer’s concerns, describes what was done, and, where appropriate, explains any relief offered.
5.1 Elements of an Effective CFPB Response
Responses should be concise yet thorough, avoiding jargon that could confuse the consumer. Core elements typically include:
- Summary of the complaint in neutral terms, confirming your understanding of the consumer’s concerns.
- Description of the review explaining what records were examined and what steps were taken during the investigation.
- Findings that clearly state what happened, referencing key dates and amounts where relevant.
- Outcome and resolution, specifying any refunds, corrections, or other actions taken (or explaining why no relief is provided).
- Future steps, such as changes to processes, additional monitoring, or recommendations for the consumer.
5.2 Tone and Consumer Focus
The CFPB encourages companies to provide responses that are understandable to consumers and that directly answer the issues raised. To that end, companies should:
- Use plain language and avoid unnecessary technical terms.
- Be respectful and avoid blaming the consumer.
- Address each question or allegation raised in the complaint.
- Acknowledge any errors or miscommunications and explain how they are being corrected.
5.3 Classifying the Response
Through the CFPB portal, companies generally categorize how the complaint was handled (for example, whether relief was provided). While specific classifications are defined by the CFPB, companies should ensure that the category selected accurately reflects the actual outcome and is consistent across similar cases.
6. Timeliness and Regulatory Expectations
Timely response is a central feature of the CFPB complaint process. The Bureau publicly emphasizes prompt handling of complaints and tracks company performance over time.
6.1 Internal Deadlines and Monitoring
To meet external expectations, companies should set internal deadlines shorter than the deadlines for providing final responses through the CFPB portal. Effective practices include:
- Automatic alerts for newly received complaints and approaching due dates.
- Daily or weekly status reports showing open cases and aging.
- Escalation triggers for complaints at risk of breaching timelines.
6.2 Handling Complex or Ongoing Issues
Some complaints involve complex issues that cannot be fully resolved immediately. In such cases, companies should still provide an update through the CFPB portal and explain any additional steps being taken. If ongoing investigation or remediation is required, the response should:
- Describe interim findings and actions taken so far.
- Indicate expected timeframes for final resolution, if known.
- Commit to updating the consumer if further material developments occur.
7. Escalation, Remediation, and Learning from Complaints
Individual complaints can reveal broader issues in a company’s practices. Regulatory guidance emphasizes the importance of using complaints to identify and correct systemic problems as part of a compliance management system.
7.1 Escalating High-Risk Cases
Companies should have criteria for when a complaint must be escalated to senior management, legal, or specialized risk committees. Common triggers include:
- Potential violation of law or regulation affecting multiple consumers.
- Allegations related to discrimination or unfair, deceptive, or abusive acts or practices (UDAAP).
- Significant financial exposure or potential for litigation.
- Complaints that mirror issues previously identified in examinations or enforcement actions.
7.2 Remediation Beyond the Individual Consumer
If a complaint reveals that other customers may have been affected by the same issue, the company should consider broader remediation steps, such as:
- Identifying all affected accounts and providing similar relief.
- Adjusting system logic or business rules that caused the issue.
- Updating disclosures, scripts, or training materials.
Taking these steps can reduce the risk of supervisory criticism or enforcement related to widespread issues.
7.3 Trend Analysis and Reporting
Aggregated complaint data is a valuable input for compliance and risk management. Companies can enhance their controls by:
- Regularly reviewing CFPB complaint trends by product, issue type, business line, and outcome.
- Comparing CFPB complaints with internal complaint channels to spot discrepancies.
- Reporting key metrics and notable themes to senior leadership and boards.
8. Coordination with Other Agencies and Resources
In some cases, a CFPB complaint may reference issues that involve other regulators or law enforcement. For example, complaints connected to identity theft or scams may intersect with responsibilities of the Federal Trade Commission, state attorneys general, or local law enforcement.
8.1 When Other Authorities May Be Involved
Companies should be prepared to cooperate, consistent with law and policy, when complaints:
- Involve suspected fraud or criminal conduct requiring law enforcement notification.
- Relate to state-law issues that may draw interest from state regulators or attorneys general.
- Raise safety or exploitation concerns for older adults or individuals with disabilities, which may implicate adult protective services.
8.2 Communicating with Consumers About External Resources
While your company’s primary responsibility is to address issues within its control, in some circumstances it may be appropriate to inform consumers about additional resources, such as:
- How to report fraud or identity theft to the Federal Trade Commission.
- How to reach state attorney general offices for broader consumer protection concerns.
- Available support services for victims of financial exploitation.
9. Governance, Documentation, and Continuous Improvement
A well-governed CFPB complaint process relies on strong documentation and ongoing evaluation. This not only supports efficient operations but also helps demonstrate to regulators that the company takes complaints seriously.
9.1 Documentation Standards
For each complaint, companies should maintain a complete file that may include:
- The original CFPB complaint and all attachments.
- Internal notes, emails, and records reviewed in the investigation.
- Decision rationales and approvals, especially for high-risk cases.
- Copies of responses submitted through the CFPB portal.
Consistent documentation is particularly important given that complaint files may later be reviewed in supervisory exams or other regulatory contexts.
9.2 Training and Staff Support
Staff involved in complaint handling should receive regular training covering:
- How to interpret CFPB complaint data and issue categories.
- Relevant consumer protection laws and internal policies.
- Best practices for communication and de-escalation with consumers.
- Use of internal systems for tracking, investigation, and reporting.
9.3 Periodic Reviews and Testing
Companies can strengthen their complaint programs by conducting periodic reviews, such as:
- Quality control reviews of a sample of CFPB responses to assess accuracy and clarity.
- Internal audits examining whether procedures are followed and whether records support conclusions.
- Gap analyses comparing complaint-handling practices to evolving regulatory expectations.
10. Frequently Asked Questions (FAQs) for Companies
10.1 Are companies required by law to respond to CFPB complaints?
The CFPB expects companies to respond to complaints it forwards, and this expectation is embedded in the Bureau’s supervisory approach and complaint-handling framework. While the precise legal obligations may vary depending on charter and regulator, failing to respond can raise significant supervisory and reputational concerns.
10.2 How fast should we respond to a CFPB complaint?
The CFPB emphasizes timely responses and tracks how quickly companies reply to complaints. Companies should set internal deadlines that allow time for investigation and review before the final response is due, and should escalate any case that appears at risk of delay.
10.3 Can we communicate directly with the consumer outside the CFPB portal?
Yes, companies often contact consumers directly to obtain additional information or to explain resolutions. However, the official record with the CFPB must still include a response submitted through the portal that accurately reflects what was done and what communications occurred.
10.4 What if we believe the complaint is about a different company?
During intake, you should confirm that the complaint properly relates to your company and the right affiliate or line of business. If you determine the complaint was misdirected, follow the CFPB’s instructions within the portal for indicating that it does not pertain to your company, and document the basis for that conclusion.
10.5 How do CFPB complaints relate to our broader compliance program?
Complaint data is one of several elements that the CFPB considers in evaluating a company’s compliance management system. Integrating CFPB complaints into your broader risk, audit, and governance processes can help identify emerging issues earlier and demonstrate a culture of compliance and consumer protection.
References
- Submit a complaint — Consumer Financial Protection Bureau. 2024-01-10. https://www.consumerfinance.gov/complaint/
- Consumer Financial Protection Bureau: About us — Consumer Financial Protection Bureau. 2023-11-15. https://www.consumerfinance.gov/about-us/
- Contact us — Consumer Financial Protection Bureau. 2024-02-01. https://www.consumerfinance.gov/about-us/contact-us/
- How to file a complaint with the CFPB: A step-by-step guide — Bankrate. 2024-03-05. https://www.bankrate.com/banking/how-to-file-a-complaint-with-the-cfpb/
- Submit a Complaint to the Consumer Financial Protection Bureau (CFPB) — Pennsylvania Legal Aid Network. 2023-09-01. https://www.palawhelp.org/resource/submit-a-complaint-about-a-financial-product-or-service
Similar Articles








Read full bio of medha deb




