Housing and credit counseling gives people practical help when money problems start affecting their home, rent, mortgage, or overall financial stability. These services can support homeowners, renters, and borrowers who need guidance on budgeting, delinquency, foreclosure, debt, or credit concerns. Federal agencies note that housing counselors can advise on buying a home, renting, defaults, forbearance, foreclosures, and credit issues, while HUD-approved counseling agencies can help people facing mortgage trouble or other homeownership challenges.
For many households, the value of counseling is not just information. It is a structured plan, a clearer view of options, and access to a trained professional who understands housing-related financial stress. That can matter most when a missed payment, a rising debt balance, or an unexpected income drop makes the future feel uncertain.
What Housing and Credit Counseling Covers
Housing and credit counseling can cover a wide range of issues, but the exact services depend on the agency. Some agencies focus on budgeting and debt management, while others provide broader support such as foreclosure counseling, homeowner education, mortgage delinquency help, or homebuyer preparation.
- Budget review to identify income, expenses, and spending gaps.
- Debt management help for unsecured debt and repayment planning.
- Credit report review and guidance on improving credit history.
- Foreclosure and delinquency counseling for borrowers behind on mortgage payments.
- Homebuyer education for people preparing to purchase a home.
- Rental and housing advice for people deciding how to handle housing costs.
Some agencies also help with consumer education, identity theft recovery, credit rating questions, and financial management counseling. That broader support can be useful because housing problems often overlap with other financial pressure points, such as high card balances, medical bills, or unstable employment.
When Counseling Becomes Especially Useful
Counseling is often most helpful when a person is not yet in crisis but can see one developing. For example, a homeowner who is struggling to make monthly payments may have more options if they seek help early rather than waiting until the lender has already moved far into the foreclosure process.
It can also help when someone is trying to build toward homeownership but needs a stronger financial foundation first. Credit counseling agencies commonly assist with budgeting, debt reduction, and credit report improvement, all of which can affect mortgage readiness.
People commonly seek housing or credit counseling when they are facing one or more of the following situations:
- A temporary loss of income or reduced hours
- Late mortgage payments or a notice from the lender
- Difficulty keeping up with rent or utility costs
- High credit card debt that is affecting monthly stability
- A need to rebuild credit before buying a home
- Confusion about forbearance, default, or foreclosure options
Because housing and credit problems often build gradually, counseling can function as a form of early intervention. The earlier someone understands their numbers and choices, the more likely they are to avoid avoidable damage.
How a Counselor Typically Helps
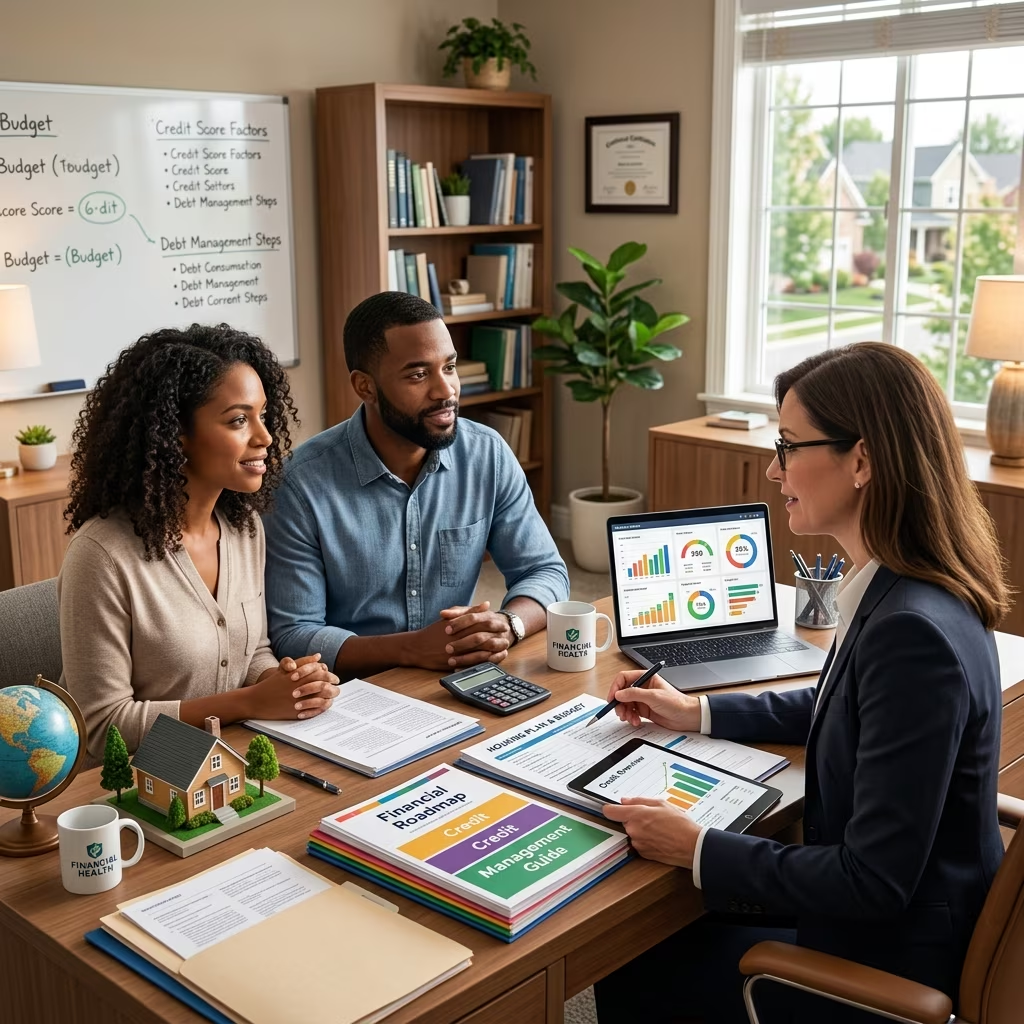
A counselor usually begins by reviewing the client’s financial picture. That can include income, housing expenses, debts, credit concerns, and any notices from a lender or landlord. From there, the counselor may help create a realistic budget, suggest priorities, and explain available options.
In a foreclosure-related case, the counselor may help a homeowner understand what the lender expects, what documents may be needed, and how to prepare for a conversation about repayment alternatives. Federal resources point users to housing counselors for advice on defaults, forbearances, and foreclosures, showing that counselors can play an important role in helping borrowers understand the process and their available paths.
In a credit counseling context, the counselor may review a credit report, identify problem areas, and suggest steps to improve credit behavior over time. Agencies listed in public service directories describe services such as credit score improvement, getting out of debt strategies, budgeting, and handling charge-offs or judgments.
Finding a Reliable Housing or Credit Counselor
Not every financial advice source is equally trustworthy. A reliable place to start is a HUD-approved housing counseling agency or a federally recognized housing counselor search tool. The CFPB directs consumers to find housing counselors through its resources and also points people to the nationwide HUD-approved counseling network. HUD also maintains a housing counselor search tool.
That matters because a qualified counselor should be able to explain options without pushing a product that benefits the counselor more than the client. In contrast, unverified services may promise quick fixes, charge hidden fees, or offer unrealistic results.
| What to look for | Why it matters |
|---|---|
| HUD approval or recognized counseling status | Shows the agency is part of a verified housing counseling system. |
| Clear explanation of fees | Helps you compare free and paid services before committing. |
| Specific service list | Lets you confirm whether the agency handles foreclosure, budgeting, or credit issues. |
| Contact information and availability | Makes it easier to schedule help quickly when time matters. |
Some agencies provide free counseling, while others may charge fixed fees for certain services. Public listings show that credit counseling may be free, with set fees for other types of support. Because pricing varies, it is smart to ask about costs before starting a session.
What to Bring to a Counseling Session
Being prepared helps a counselor give more useful advice. Even a strong counselor can only work with the information provided, so gathering documents in advance usually leads to better recommendations.
- Recent pay stubs or proof of income
- Mortgage statement or rental agreement
- Monthly bills and debt statements
- Credit report if you have one
- Any foreclosure, default, or late-payment notices
- A list of household expenses
- Questions you want answered
If you are seeking foreclosure help, keep all lender communications together. If you are seeking credit counseling, bring debt statements and a full list of accounts. The more complete the picture, the more specific the guidance can be.
Common Misunderstandings About Counseling
One common misunderstanding is that counseling guarantees a foreclosure will stop. In reality, counseling can improve understanding and help people prepare, but the outcome still depends on the lender’s rules, the borrower’s finances, and the timing of the intervention. Federal housing resources describe counseling as a support service for people facing defaults and foreclosures, not a guarantee of a particular legal result.
Another misunderstanding is that credit counseling and debt settlement are the same thing. They are not. Credit counseling usually focuses on budgeting, credit education, and debt management planning, while debt settlement is a separate approach with different risks and consequences. Public counseling agency descriptions emphasize budgeting, debt management, and credit-building rather than guaranteed debt reduction.
A third misunderstanding is that counseling is only for people in serious trouble. In practice, it can also help people who want to strengthen their finances before problems develop. Housing counseling resources specifically include help for homebuying, renting, and credit issues, which shows the service is not limited to crisis response.
How Counseling Fits into Foreclosure Prevention
Foreclosure prevention works best when homeowners act early. A counselor can help a borrower organize the facts, understand delinquency status, and communicate more effectively with the lender. CFPB and HUD resources both point consumers toward housing counseling for defaults and foreclosures, indicating that this is a recognized part of the prevention toolkit.
For borrowers with FHA, VA, or conventional loans, HUD-approved counseling agencies may also be able to help people who are behind on payments or worried about becoming delinquent. The practical benefit is that counseling can turn a vague fear into a plan. Instead of guessing, the homeowner can review numbers, understand deadlines, and explore possible next steps.
Frequently Asked Questions
Is housing counseling only for homeowners?
No. Housing counseling can also help renters and people preparing to buy a home. Federal resources describe advice for buying, renting, defaults, forbearances, foreclosures, and credit issues.
Are credit counseling services always free?
No. Some agencies provide free credit counseling, while other services may have fixed fees. Public service listings show both free counseling and fee-based offerings depending on the type of help requested.
Can a counselor negotiate with my lender for me?
Sometimes a counselor can help you prepare for discussions, organize documents, and understand your options. The exact level of assistance depends on the agency and the situation, but the counselor’s role is generally advisory and educational rather than a guarantee of negotiation success.
How do I know if an agency is legitimate?
Look for HUD approval, official housing counselor search tools, clear service descriptions, and transparent fee information. HUD and CFPB both provide access to recognized housing counseling resources.
Should I wait until I miss several payments before asking for help?
No. Counseling is often more effective when you seek it early, before the problem becomes harder to manage. Early action can make it easier to review budget options and foreclosure alternatives.
Practical Takeaway
Housing and credit counseling is best viewed as a problem-solving service. It helps people understand their money, protect their housing, and make informed choices during stressful financial periods. Whether the issue is foreclosure risk, debt pressure, weak credit, or preparing for homeownership, a qualified counselor can help build a clearer path forward.
For anyone facing housing stress, the most important step is often the simplest one: get help early, ask direct questions, and use trusted counseling resources rather than waiting for the situation to worsen.
References
- Housing and Credit Counseling, Inc. (HCCI) – Lawrence Public Library — Lawrence Public Library. 2026-07-09. https://lplks.org/content/housing-and-credit-counseling-inc/
- Credit Counseling – Fair Housing Council of Riverside County — Fair Housing Council of Riverside County. 2026-07-09. https://fairhousing.net/services/credit-counseling/
- HUD Approved Counseling Agencies – 211LA — 211LA. 2026-07-09. https://211la.org/services/Hx0V2Kd6pTV1GKdpu17mOmeiqOlWeA/hud-approved-counseling-agencies
- Find a Housing Counselor — Consumer Financial Protection Bureau. 2026-07-09. https://www.consumerfinance.gov/find-a-housing-counselor/
- Credit Counseling & Debt Management in Orange, CA — American Consumer Credit Counseling. 2026-07-09. https://www.consumercredit.com/about-us/locations/orange/
- housingcounseling — U.S. Department of Housing and Urban Development. 2026-07-09. https://www.hud.gov/i_want_to/talk_to_a_housing_counselor