When a lender moves to foreclose on a home, the case often turns on one critical piece of paperwork: the foreclosure affidavit. These sworn statements can determine whether a court allows a foreclosure to go forward or stops it in its tracks. In recent years, the practice known as robo-signing—mass, careless signing of affidavits—has raised serious questions about the accuracy and legality of many foreclosures.
This article provides a clear, practical explanation of what foreclosure affidavits are, how robo-signing undermines them, and what homeowners can do when they suspect that the paperwork in their case is wrong or misleading. It does not replace legal advice, but it will help you understand the issues so you can speak more effectively with a lawyer or housing counselor.
What Is a Foreclosure Affidavit?
An affidavit is a written statement of facts that is signed under oath before a notary public or other authorized official. In foreclosure cases, lenders or mortgage servicers use affidavits to show courts that they have the legal right to foreclose and that the borrower is in default on the loan.
A typical foreclosure affidavit attempts to establish several key points:
- Ownership of the loan: Who currently holds the mortgage or the right to enforce it.
- Default status: That the borrower has missed payments or otherwise breached the loan terms.
- Amount due: The total balance, late fees, interest, and other charges allegedly owed.
- Compliance with law: That required notices and loss mitigation steps were completed as prescribed by state law or contract.
Because the signer swears under penalty of perjury that the information is true, affidavits are meant to be reliable evidence. Courts often rely heavily on them in deciding whether to grant summary judgment (a foreclosure order without trial) or allow a sale to proceed.
Common Types of Affidavits in Foreclosure Cases
Depending on the state and the nature of the case, you may see several kinds of affidavits, including:
- Affidavit of default or debt: Describes the payment history, default date, and the amount currently due.
- Affidavit of holder or ownership: States that the lender or investor is entitled to enforce the mortgage and promissory note.
- Affidavit of compliance: Confirms that the lender followed pre-foreclosure requirements, such as good-faith loss mitigation efforts or statutory notices.
- Affidavit of service or notice: Swears that required foreclosure notices were properly mailed or delivered to the homeowner.
- Military status affidavit: Attests that the borrower is not on active military duty, which can affect foreclosure protections.
Each affidavit plays a specific role in proving that the foreclosure is lawful. If one is incorrect or incomplete, that can create grounds to challenge the case.
Why Affidavits Matter So Much in Foreclosure
In many states, especially those that use judicial foreclosure (where a court must approve the foreclosure), lenders rely on affidavits instead of live testimony to establish the facts of the case. For efficiency, courts often decide foreclosure cases largely on written submissions, meaning a single affidavit can carry enormous weight.
Key reasons affidavits are so important include:
- Evidence of default: The affidavit explains when the borrower stopped paying and how far behind they are.
- Evidence of standing: It shows that the foreclosing party actually owns, or has the right to enforce, the loan.
- Evidence of procedure: It can show that legally required steps—like sending notices or offering loss mitigation—were followed.
- Basis for quick judgment: Courts may grant summary judgment based largely on these sworn statements if they appear complete and accurate.
Because the foreclosure process can move quickly once affidavits are filed, homeowners need to understand how to spot potential problems early.
Understanding Robo‑Signing
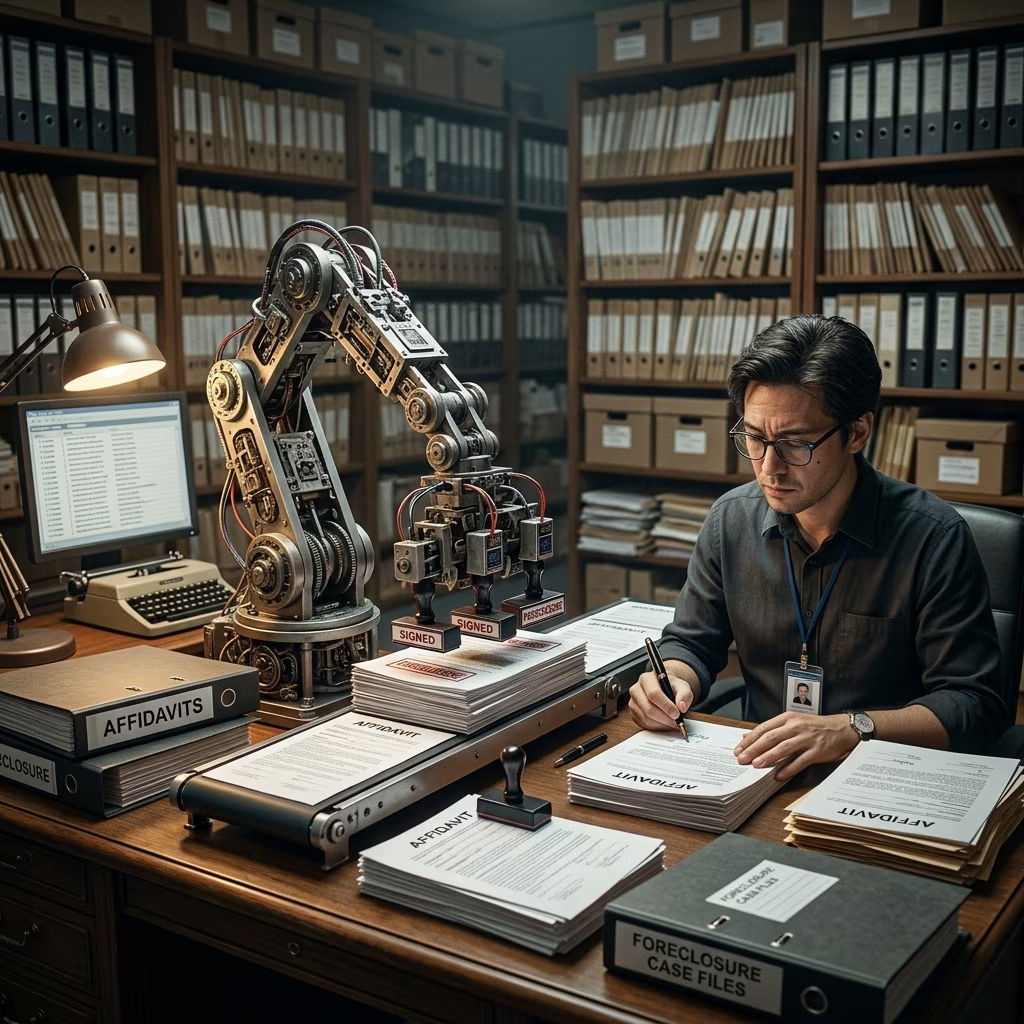
Robo-signing refers to the practice of rapidly signing large volumes of foreclosure affidavits or other legal documents without properly reviewing the underlying facts or supporting records. Instead of carefully checking loan files, some employees or contractors simply sign and notarize documents as a routine task, sometimes signing hundreds or thousands of affidavits in a single day.
How Robo‑Signing Happens
Robo-signing usually involves one or more of the following behaviors:
- No document review: Signers swear they have personal knowledge of the facts, but never examine the loan file or payment history.
- Mass production of affidavits: Signers process huge stacks of documents with little or no verification.
- Improper notarization: Notaries may stamp documents without witnessing the signature or affirming the oath.
- False job titles or authority: Signers may be labeled as “vice presidents” or “authorized agents” of multiple entities solely to sign paperwork.
Investigations and litigation over robo-signing exposed widespread flaws in foreclosure documentation, including affidavits that were incomplete, inaccurate, or outright false.
Why Robo‑Signing Is a Legal Problem
Robo-signing undermines the core purpose of an affidavit: to provide truthful, reliable information under oath. When a signer falsely claims personal knowledge or fails to verify the facts, the affidavit can be legally defective.
Potential legal issues include:
- False statements under oath: Swearing to facts without knowledge can amount to perjury or fraud.
- Lack of competent evidence: Courts may decide that robo-signed affidavits do not provide adequate proof of default or ownership.
- Due process concerns: Homeowners may be deprived of property based on unreliable or inaccurate paperwork.
- Violation of state procedures: Many states require the affiant to have personal knowledge and proper notarization; robo-signing can violate these rules.
As a result, some courts have denied or delayed foreclosures when they discovered robo-signed affidavits, and regulators have investigated the practice at major financial institutions.
Core Legal Requirements for Valid Foreclosure Affidavits
While specifics vary by state, several general standards apply to foreclosure affidavits in most jurisdictions:
| Requirement | What It Typically Means |
|---|---|
| Personal knowledge | The signer must have direct or reasonably reliable knowledge of the loan records and the facts stated. |
| Oath and notarization | The affiant signs under oath before a notary or authorized official, who confirms the identity and the sworn statement. |
| Specific factual detail | The affidavit should include concrete information, such as dates, amounts, and document references, not just general assertions. |
| Legal right to foreclose | The lender or servicer must explain its authority to enforce the mortgage and note, including assignments where necessary. |
| Compliance with statutes | The affidavit may need to certify compliance with state foreclosure laws, such as notice or loss mitigation requirements. |
States sometimes codify these requirements, especially in judicial foreclosure systems where affidavits form the backbone of the lender’s case.
How Robo‑Signing Affects Homeowners
For homeowners, robo-signing is more than a technical violation; it can affect whether a foreclosure is lawful and whether there are grounds to challenge the process.
Risks to Homeowners
Robo-signed affidavits can lead to several concrete harms:
- Incorrect balances: Errors in payment history or fees can inflate the alleged amount due.
- Misidentification of the lender: The wrong party may attempt to foreclose, raising questions about who truly owns the loan.
- Premature foreclosure: Paperwork may incorrectly indicate default or skip legally required pre-foreclosure steps.
- Limited opportunity to contest: If courts assume affidavits are reliable, homeowners may lose their property without a full airing of the facts.
Because of these risks, courts and regulators have become more willing to scrutinize foreclosure affidavits, especially when homeowners raise credible challenges to their accuracy.
Spotting Possible Problems in a Foreclosure Affidavit
If you are facing foreclosure, carefully reviewing any affidavits related to your case can help you identify issues worth discussing with an attorney. Common warning signs include:
- Very high volume signers: The same individual appears as the affiant on large numbers of cases, sometimes across multiple companies.
- Generic or vague language: The affidavit states conclusions (“borrower is in default”) without specific dates, amounts, or records.
- Inconsistent information: Figures in the affidavit do not match your statements, billing records, or other lender communications.
- Missing supporting documents: References to attached payment histories, notes, or assignments that are not actually included.
- Questionable notarization: Signatures dated differently from the notary stamp, or notarization that appears to have occurred in another state than the affiant’s stated location.
These signs do not guarantee that an affidavit is false, but they warrant closer scrutiny and may support a legal challenge.
Options for Challenging Faulty Affidavits
Homeowners have several potential avenues to challenge robo-signed or inaccurate affidavits, though the exact options depend on state law and whether the foreclosure is judicial or nonjudicial.
Judicial Foreclosure States
In states where foreclosures must go through court, homeowners typically respond directly within the lawsuit:
- File an answer: Deny incorrect allegations in the lender’s complaint and specifically contest any flawed affidavits.
- Oppose summary judgment: Argue that defective affidavits are not sufficient evidence and that a full hearing or trial is needed.
- Request discovery: Ask for underlying loan records, assignment documents, and information about the affiant’s role and training.
- Move to strike affidavits: Seek to exclude affidavits that lack personal knowledge, proper notarization, or accurate information.
Court decisions in some jurisdictions have emphasized that affidavits must be based on a careful review of records by someone competent to testify about the loan, not by a robo-signer with no real knowledge.
Nonjudicial Foreclosure States
Where foreclosures primarily occur outside court, options may include:
- Filing a lawsuit: Bring an action to stop the foreclosure or challenge the validity of the documents.
- Using statutory procedures: Some states provide specific processes to contest nonjudicial foreclosure, such as affidavits or objections recorded in the land records.
- Seeking bankruptcy protection: Chapter 13 bankruptcy can allow a homeowner to reorganize debts and raise challenges to the lender’s claim within the bankruptcy case.
In both judicial and nonjudicial systems, the availability and strength of these options depend on state law, the specific facts, and the homeowner’s ability to present evidence.
Proactive Steps for Homeowners Facing Foreclosure
Homeowners who act early usually have more options. Consider these practical steps if you receive foreclosure papers or suspect robo-signing:
- Gather your records: Collect mortgage statements, payment receipts, correspondence with the lender or servicer, and any prior modification agreements.
- Obtain copies of court filings: In judicial states, request copies of the complaint, affidavits, and exhibits filed with the court.
- Compare numbers and dates: Check whether the affidavit’s default date and amounts match your records.
- Note any discrepancies: Document inconsistencies or missing information and organize them for discussion with an attorney.
- Seek legal help fast: Contact a housing lawyer, legal aid office, or HUD-approved housing counselor as soon as possible. Deadlines for responding to foreclosure paperwork can be short.
Even if you do not ultimately contest the foreclosure, accurate information can affect deficiency judgments, tax consequences, and your ability to negotiate alternatives like loan modifications or short sales.
Frequently Asked Questions
1. Does robo‑signing automatically cancel a foreclosure?
Not automatically. A defective affidavit can provide grounds to challenge a foreclosure, and courts may delay or deny foreclosure if the lender’s evidence is unreliable. However, many courts allow lenders to correct paperwork or submit new affidavits. The impact depends on how serious the errors are and on state law.
2. How can I find out whether my state requires foreclosure affidavits?
Requirements for foreclosure affidavits are usually found in state statutes or court rules governing foreclosure procedures. These laws may specify what kind of sworn statements or certifications lenders must file. You can often locate them through your state’s official legislative or court websites, or by consulting a lawyer familiar with foreclosure practice in your area.
3. What if the affidavit lists the wrong amount I owe?
If you believe the amount stated in an affidavit is wrong, raise the issue as early as possible. Provide your own records showing payments, charges, or corrections. Courts rely on accurate figures to determine whether you are in default and by how much, and a significant discrepancy can undermine the lender’s case.
4. Can I represent myself when challenging an affidavit?
Many homeowners do represent themselves in foreclosure cases, but the rules of evidence and procedure can be complex. Because affidavits and robo-signing issues involve legal standards about proof and documentation, consulting with an attorney or legal aid organization is strongly recommended, even if you ultimately appear pro se (without a lawyer).
5. Are all mass-produced affidavits illegal?
Not necessarily. Large lenders and servicers handle many cases, so they may use standardized formats and workflows. The key legal question is whether each affidavit is based on a genuine, case-specific review by someone with personal knowledge of the records and whether the document is accurate and properly sworn. Mass production becomes problematic when speed replaces accuracy and truthfulness.
Key Takeaways
- Affidavits are central evidence in many foreclosure cases, meant to provide truthful, detailed facts about the loan and default.
- Robo-signing undermines affidavits by allowing people to sign them without real review or personal knowledge, raising serious legal concerns.
- Homeowners can challenge defective affidavits through court filings, discovery, and other legal tools, especially in judicial foreclosure states.
- Early action and good documentation significantly improve a homeowner’s chances of identifying and addressing errors in foreclosure paperwork.
If you suspect that your foreclosure involves robo-signed or inaccurate affidavits, consider speaking promptly with a qualified attorney to review your options. While this guide can help you understand the issues, only a lawyer licensed in your state can advise you on how the law applies to your specific situation.
References
- Affidavits and Robo-Signing — FindLaw. 2022-05-10. https://www.findlaw.com/realestate/foreclosure/affidavits-and-robo-signing.html
- Affidavits Re Pre-Foreclosure Actions — Texas Bankers Association. 2014-01-01. https://member.texasbankers.com/App_Themes/PB192/Documents/affidavitsrepreforeclosureactions.htm
- Foreclosure Steps and Timeline — Maryland People’s Law Library. 2023-03-15. https://www.peoples-law.org/foreclosure-steps-and-timeline
- False Affidavits in Foreclosures: What the Robo-Signing Mess Means for Homeowners — Nolo / Anthem EAP. 2011-10-20. https://www.anthemeap.com/ge-appliances/find-legal-support/resources/real-estate/legal-assist/false-affidavits-in-foreclosures-what-the-robo-signing-mess-means-for-homeowners
- Foreclosure Note + Deed of Trust Trustee — University of North Carolina School of Government (course materials). 2012-03-01. https://www.sog.unc.edu/sites/www.sog.unc.edu/files/course_materials/M.%20Smith-Foreclosure%20PPT%20slides.pdf
- Residential Mortgage Foreclosure Affidavit Policy — Cuyahoga County Court of Common Pleas. 2010-11-01. https://cp.cuyahogacounty.gov/media/1919/resmortaffidavitpol.pdf
- Setting Aside a Foreclosure Via Affidavit in Michigan — USFN. 2018-05-01. https://www.usfn.org/blogpost/1296766/476888/Setting-Aside-a-Foreclosure-Via-Affidavit-in-Michigan