Planning your estate is one of the most responsible decisions you can make for your family’s future. While the topic may feel overwhelming, breaking it down into manageable components makes the process far less daunting. At its core, estate planning involves identifying what you own, deciding who should receive your assets, and documenting your wishes regarding medical decisions and financial management. The foundation of this planning rests on several critical documents that work together to create a comprehensive strategy for protecting your loved ones.
Many people delay estate planning because they believe it only applies to the wealthy or elderly. In reality, anyone with assets—whether a home, vehicle, savings account, or personal belongings—benefits from having these documents in place. Without them, your family may face legal complications, delays in receiving inheritances, and costly court proceedings. This guide walks you through the fundamental documents that form the backbone of solid estate planning, explaining what each does and why you need it.
Understanding the Three Pillars of Estate Administration
Effective estate planning rests on three interconnected purposes: managing your assets during your lifetime, directing their distribution after your death, and authorizing trusted individuals to act on your behalf when you cannot. Each of these functions requires specific legal documents. The combination of these papers creates a safety net that protects your interests while you’re alive and ensures your wishes guide what happens to your estate afterward.
The first pillar focuses on asset management during your lifetime. If you become unable to handle your own affairs due to illness or incapacity, someone needs legal authority to manage your finances and make decisions on your behalf. The second pillar addresses distribution of your property after death, ensuring assets transfer to intended beneficiaries smoothly and according to your specifications. The third pillar covers healthcare decision-making when you’re incapacitated, allowing trusted people to direct your medical care based on your stated preferences.
The Comprehensive Will: Your Blueprint for Distribution
A will stands as the most fundamental estate planning document most people create. This legal instrument accomplishes multiple critical tasks simultaneously. It declares your intentions regarding property distribution, identifies who will oversee your estate’s settlement, and designates guardians for minor children if applicable. Without a will, state law determines how your assets are divided, which may not align with your actual wishes.
Beyond basic property distribution, a will allows you to accomplish several important objectives:
- Name an executor or personal representative who will manage your estate through the probate process
- Designate guardians for dependent children, ensuring they’re cared for by people you trust
- Specify how estate expenses, taxes, and debts should be paid
- Leave instructions for handling specific items of sentimental or significant value
- Name alternative executors in case your first choice is unable or unwilling to serve
The validity of your will depends on following your state’s specific requirements. Generally, you must sign it in the presence of witnesses who are not beneficiaries, have the document notarized in many cases, and ensure you were of sound mind when creating it. These formalities exist to prevent fraud and ensure your true wishes are honored.
Trusts: An Alternative Path for Property Management
While wills are essential, many people benefit from establishing a trust as part of their estate plan. A trust is a legal arrangement where you transfer property to a trustee—someone you trust—who manages those assets for the benefit of designated beneficiaries. Trusts offer distinct advantages over wills alone, particularly regarding probate avoidance and privacy protection.
The most common type is a revocable living trust, which you can modify or revoke during your lifetime. You maintain control over the trust assets while alive and can change the terms as your circumstances evolve. Upon your death, the trustee transfers assets to beneficiaries without going through the public probate process. This approach keeps your financial information private and typically settles estates more quickly than probate requires.
Different trust structures serve different purposes. Some people use trusts to manage assets for minor children until they reach adulthood. Others establish trusts to provide for family members with special needs or financial inexperience. Irrevocable trusts, which you cannot change after creation, may offer tax advantages in certain situations. The right trust structure depends on your specific goals and financial situation.
Powers of Attorney: Authorizing Financial Decision-Making
A durable power of attorney is a document that designates someone to manage your financial and legal affairs if you become unable to do so yourself. This document must remain effective even if you become incapacitated, which is why it’s called “durable.” Without this authorization, family members may need to go to court and obtain guardianship to access your accounts or pay your bills—an expensive and time-consuming process.
When you create a durable power of attorney, you identify an “agent” or “attorney-in-fact” who can:
- Access and manage your bank accounts
- Pay bills and manage financial obligations
- Buy, sell, or manage real estate
- Handle investment accounts
- File taxes on your behalf
- Manage business interests if applicable
The scope of powers can be broad or limited depending on your preferences. Some people grant their agent general authority to handle all financial matters. Others restrict the agent’s powers to specific accounts or time periods. You can also specify that the power of attorney becomes effective immediately or only upon your incapacity, depending on what works best for your situation.
Healthcare Directives: Guiding Medical Decisions
While financial documents protect your assets, healthcare directives protect your wellbeing and ensure your medical wishes are honored. This category includes several related but distinct documents. A health care power of attorney (also called a healthcare proxy or medical power of attorney) designates someone to make medical decisions on your behalf if you cannot communicate your own preferences. This person is legally bound to follow the directions you’ve established in advance.
A living will or advance directive documents your preferences regarding life-sustaining treatments if you face terminal illness or permanent unconsciousness. This document specifies whether you want mechanical ventilation, feeding tubes, resuscitation, or other interventions in specific medical scenarios. By clarifying these preferences beforehand, you spare your family from making agonizing decisions during your most vulnerable moments.
Many states also recognize a do-not-resuscitate (DNR) order, which directs medical professionals not to perform CPR if your heart stops or breathing ceases. This document is particularly important if you have a terminal diagnosis or believe quality of life matters more than prolonging life at all costs. Coupled with authorization to release medical information, these documents create a complete healthcare directive that ensures both your preferences and your appointed agent have legal standing.
Creating an Organized Asset Inventory
One of the most practical yet often overlooked components of estate planning is a comprehensive asset inventory. This document lists everything of value that you own, organized by category. Its purpose is straightforward: helping your executor locate and manage your assets efficiently while ensuring nothing gets overlooked.
Your inventory should include:
| Asset Category | What to Document |
|---|---|
| Real Estate | Property deeds, mortgages, tax assessments, recent appraisals |
| Financial Accounts | Bank account numbers, brokerage statements, CD information, location of safe deposit boxes |
| Retirement Assets | 401(k) account details, IRA information, pension documents, annuity contracts |
| Insurance Policies | Life insurance, disability insurance, homeowner’s and auto insurance documents |
| Vehicles and Equipment | Vehicle titles, boat registrations, recreational equipment ownership documents |
| Personal Property | Jewelry, art, collectibles, furniture, valuables with significant sentimental or monetary value |
| Debts and Liabilities | Mortgages, loans, credit card accounts, outstanding medical bills |
The value of a comprehensive inventory extends beyond the practical benefit of organization. It demonstrates the full scope of your estate to your executor and family members, prevents inadvertent omissions, and clarifies your intentions for specific items. This document should be updated annually or whenever you acquire significant assets or incur major debts.
Supporting Documents That Strengthen Your Plan
Beyond the core documents, several supporting papers complement your estate plan and provide crucial information. A letter of instruction, separate from your will, offers personal guidance to your family about your values, philosophy, and preferences for matters not covered in legal documents. This informal letter might explain why you made certain decisions, provide account usernames and passwords for digital assets, or share insights about caring for pets or managing a business.
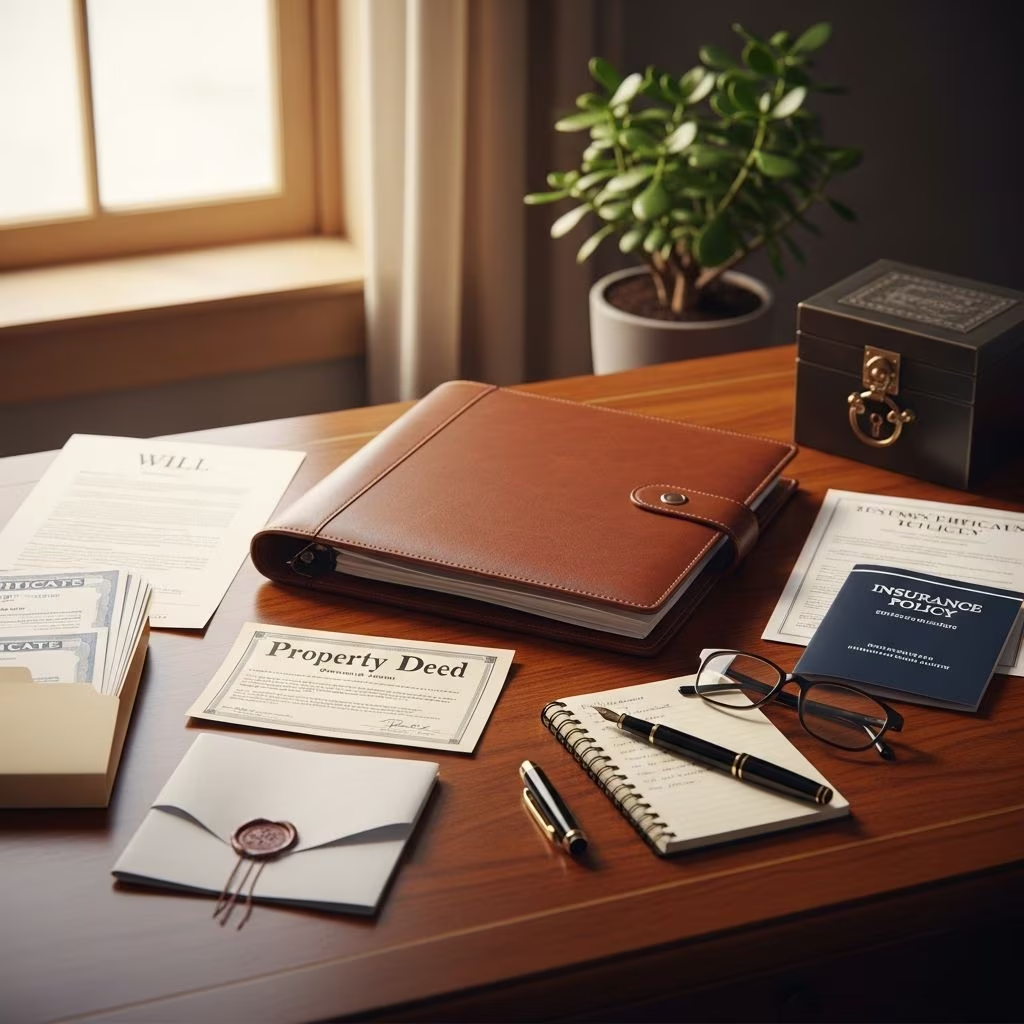
Marriage certificates, divorce decrees, and domestic partnership documentation establish your current relationship status and ensure that outdated relationships don’t complicate your estate distribution. Military service records (Form DD 214) may provide access to special benefits for veterans and their families, including burial benefits and survivor pensions. Property deeds and titles prove ownership of your real estate and vehicles. Bank statements and investment account information help your executor understand the full scope of your financial assets.
If you own a business, partnership agreements or corporate operating documents are essential. They clarify ownership percentages, succession plans, and how the business should be handled after your death. Tax returns from prior years provide your executor with important financial context and may be necessary for settling your estate. Insurance policies, including life insurance, should be clearly identified with beneficiary designations verified and updated if your circumstances change.
Organizing and Protecting Your Documents
Having estate planning documents means little if your family cannot locate them when needed. Create a system for organizing and storing these papers securely. Many people maintain an original copy of crucial documents in a safe deposit box at their bank, keeping a second copy at home in a fireproof safe or filing cabinet. Some prefer storing digital copies with an estate planning service or secure online vault.
Your executor and designated agents should know where to find these documents. Consider leaving written instructions about their location, along with access information for any security systems. Some people prepare a separate information document that lists the locations of all estate planning materials, contact information for their attorney, and important account numbers. This roadmap prevents your family from spending valuable time searching while managing their grief.
Digital assets require special consideration. Compile information about online accounts, email addresses, and any digital property you wish to pass to beneficiaries. Include usernames and password information (stored securely) so your executor can access these accounts. Specify how you want social media accounts handled—whether deleted, memorialized, or maintained.
Why Professional Guidance Matters
While online templates and DIY tools make creating basic documents easier, consulting with an estate planning attorney ensures your documents comply with your state’s laws and address your specific situation comprehensively. An attorney can identify potential complications, suggest strategies to minimize taxes, and ensure your documents work together as a coordinated system rather than isolated papers.
Professional guidance becomes especially important if you have minor children, significant assets, a business, or complex family situations. An attorney can structure your estate plan to achieve specific goals—protecting special needs family members, providing for minor children’s education, or minimizing estate taxes. They ensure your documents contain proper legal language and follow formalities required for validity.
Frequently Asked Questions
Q: How often should I review my estate planning documents?
A: Review your documents every three to five years or whenever major life changes occur, such as marriage, divorce, birth of children, significant increases in assets, or changes in your wishes regarding who manages your affairs or receives your property.
Q: Can I create a will without an attorney?
A: You can create a basic will using online templates, but having an attorney review it ensures it meets your state’s legal requirements and accomplishes your complete intentions. For simple estates with minor children or complex financial situations, professional guidance is strongly recommended.
Q: What’s the difference between a will and a living trust?
A: A will specifies how your property should be distributed after death and must go through probate. A living trust holds property during your lifetime and allows it to pass to beneficiaries without probate, offering more privacy and potentially faster settlement.
Q: Who should I name as my power of attorney agent?
A: Choose someone you trust completely who is organized, responsible, and willing to take on the role. This person should be available to act if needed and understand your financial situation. Many people choose a spouse, adult child, or close friend.
Q: What happens if I don’t have a will?
A: If you die without a will, state law determines how your property is distributed, which may not match your wishes. Your family may face lengthy probate proceedings, and courts may appoint a guardian for minor children according to state law rather than your preference.
Q: Should my healthcare directives name the same person as my financial power of attorney?
A: Not necessarily. Some people prefer different agents for financial and healthcare decisions, particularly if the person best suited for managing finances differs from the person best equipped to make medical decisions aligned with their values.
References
- Plan USA — Essential Estate Planning Documents — Plan USA. https://www.planusa.org/blog/essential-estate-planning-documents/
- Essential Documents & Checklist — Thrivent Financial. https://www.thrivent.com/insights/estate-planning/essential-estate-planning-documents
- 10 Essential Estate Planning Documents Checklist — Peck Ritchey, LLC (Chicago Estate Planning). https://www.peckritchey.com/community/estate-planning-documents/
- Estate Planning Checklist: How to Start Getting Your Affairs in Order — LegalZoom. https://www.legalzoom.com/articles/estate-planning-checklist-how-to-start-getting-your-affairs-in-order
- Estate Planning Checklist for Older Adults — National Council on Aging. https://www.ncoa.org/article/estate-planning-checklist/