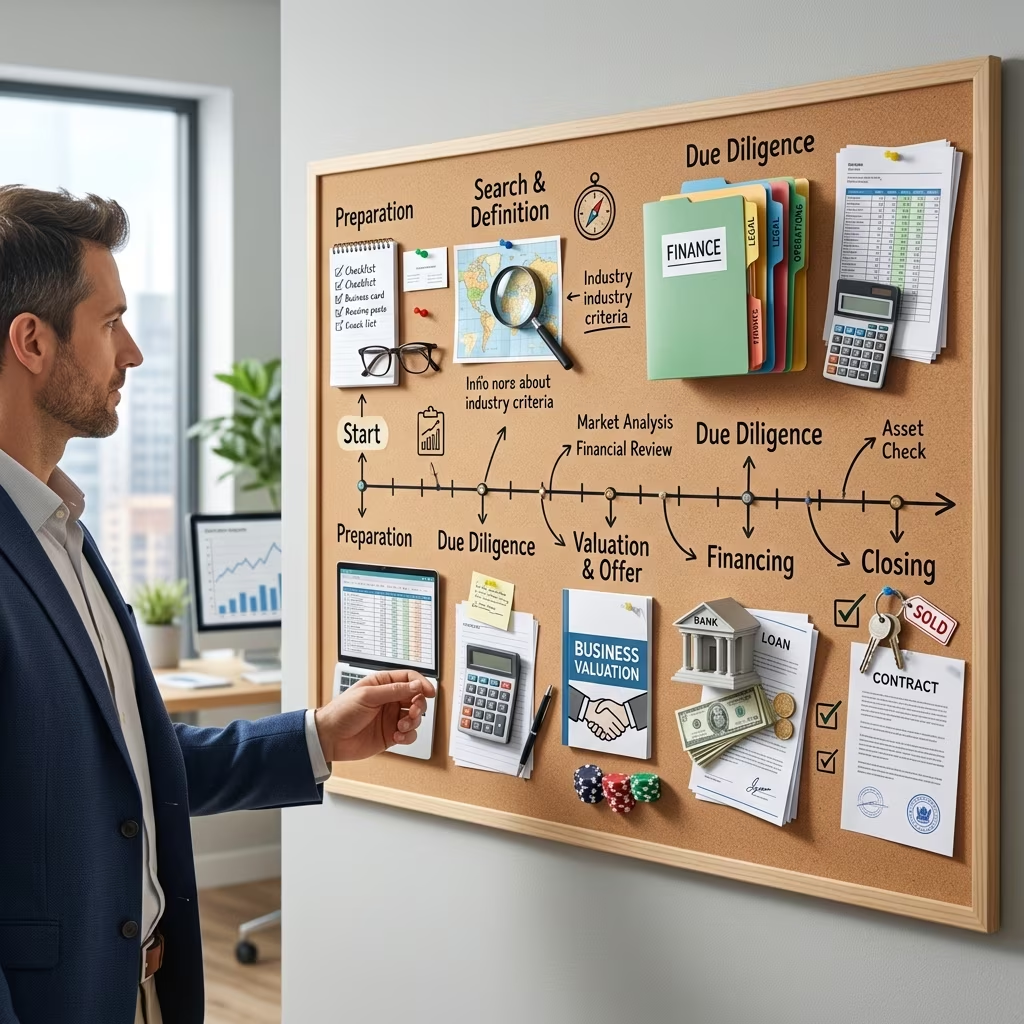
Buying an existing business is rarely a single transaction. It is a sequence of decisions, documents, negotiations, and checks that can take months to complete. Buyers usually move through several stages: defining what they want, finding suitable opportunities, reviewing financial and legal details, negotiating terms, arranging financing, and closing the deal. A careful process reduces risk and helps the buyer enter ownership with clearer expectations.
The broad structure of the process is consistent, but the pace depends on the industry, the size of the business, the quality of the records, the complexity of the deal, and whether outside financing is involved. Some purchases move quickly when seller and buyer are aligned. Others slow down because of valuation gaps, missing documents, or lender requirements. A realistic timeline is one of the best tools a buyer can have.
Start With a Clear Buy Box
The earliest stage is not about looking at listings. It is about defining the kind of business that makes sense for your skills, capital, and goals. Buyers often waste time by browsing too broadly, so it helps to create a specific set of criteria before contacting sellers or brokers.
- Industry and type of operation
- Desired location or geographic range
- Minimum and maximum purchase price
- Revenue and profit targets
- Owner involvement after closing
- Risk tolerance and financing capacity
This planning stage also includes thinking through why you want to buy the business. Some buyers want stable cash flow. Others want a growth platform, a family asset, or a way to enter a new field. The answer affects what opportunities are worth pursuing and which ones should be ignored.
Search Broadly, Then Narrow the Field
Once your criteria are set, the next phase is sourcing opportunities. Buyers commonly use business brokers, online marketplaces, professional networks, accountants, attorneys, and industry contacts. Each channel can produce different kinds of leads, and no single source is enough for every buyer.
At this stage, the goal is not to commit. It is to collect enough information to compare businesses at a high level. A buyer may review many listings before finding a few that deserve a deeper look. That is normal. A strong opportunity is usually the result of disciplined filtering rather than rushing into the first available deal.
Make First Contact and Gather Initial Information
After identifying possible targets, the buyer or broker typically begins with introductory conversations. These early exchanges help both sides determine whether the deal is worth pursuing. Sellers often want to know whether the buyer is serious, financially capable, and respectful of confidentiality.
Initial materials may include a summary description, basic financial metrics, a confidential information package, or a short overview of operations. Buyers use this information to screen for fit before spending time on site visits or detailed review. If the business appears promising, the process usually moves to confidentiality protections and a deeper round of questions.
Use Confidentiality Agreements Early
In most business sales, sensitive information is shared only after a nondisclosure agreement is signed. This protects the seller’s customer relationships, trade information, pricing data, and internal records. It also sets expectations that the buyer will not misuse information if the transaction does not move forward.
Confidentiality agreements are especially important when a business depends on a small number of key clients, specialized processes, or unique intellectual property. They are not just a formality; they are part of the structure that allows the seller to disclose meaningful details without unnecessary exposure.
Review the Business From the Inside
After an initial screen, serious buyers usually tour the business and meet the owner or management team. This step helps the buyer understand how the company operates in practice, not just on paper. A walk-through can reveal customer flow, equipment condition, staffing patterns, and signs of operational strength or weakness.
Face-to-face or virtual meetings also help the buyer judge whether the seller is prepared to cooperate during transition. A business can look attractive financially but still be difficult to acquire if communication is poor or the owner is unwilling to support a handoff.
Build a Deal Model and a Business Plan
Buying an existing company does not eliminate the need for planning. In many cases, it increases the need for planning because the buyer must account for inherited operations, legacy contracts, and current employees. A business plan helps organize the purchase around strategy instead of impulse.
The plan should explain how the company makes money, where improvements may be possible, how working capital will be handled, and what assumptions support the purchase price. Buyers may also use a simple table to compare target businesses.
| Evaluation Area | What to Look For | Why It Matters |
|---|---|---|
| Revenue quality | Recurring sales, customer concentration, seasonality | Shows how predictable the business may be |
| Expenses | Labor, rent, debt, vendor costs | Reveals whether margins are sustainable |
| Owner dependence | Relationships, approvals, daily management | Shows how much the company relies on the seller |
| Transition readiness | Training, documentation, staff stability | Indicates how smooth the handoff may be |
Enter Due Diligence With a Critical Eye
Due diligence is the most information-heavy stage of the purchase. It is the buyer’s chance to confirm that the business is worth the price and that there are no hidden problems large enough to change the deal. This is where legal counsel, accountants, and sometimes industry specialists become especially valuable.
A thorough review typically covers financial statements, tax returns, debt, assets, contracts, intellectual property, customer concentration, employee structure, insurance, litigation history, permits, and any regulatory issues. Buyers also examine whether the business has the licenses and zoning approvals needed to continue operating.
- Three years of financial statements and tax filings
- Accounts receivable and accounts payable aging
- Loan documents and security interests
- Lease terms and renewal options
- Employment agreements and payroll records
- Supplier and customer contracts
- Pending or past disputes
- Intellectual property ownership
If due diligence uncovers inconsistencies, the buyer may request more information, renegotiate the price, add protections to the agreement, or walk away. That flexibility is one of the main reasons due diligence matters so much.
Decide How the Purchase Will Be Financed
Financing can shape the entire timeline. Some buyers use cash, while others combine personal funds with bank loans, seller financing, investor capital, or specialized acquisition loans. Lenders usually want to see the business’s historical performance, the buyer’s background, the amount of equity injected, and the structure of the proposed transaction.
If financing is involved, it should be discussed early. A seller may prefer a buyer who already has a lender relationship or at least a credible financing path. Delays often happen when a buyer assumes the deal can close quickly without first confirming that funds will be available on time.
Negotiate the Letter of Intent
Once the buyer believes the business is viable, the next step is usually a letter of intent. This document is a roadmap for the transaction. It sets out the proposed price, structure, deposit terms, due diligence period, financing contingencies, and closing expectations.
A letter of intent is not always fully binding, but it matters because it frames the negotiation. It helps both parties understand where they agree and where the main issues remain unresolved. A strong letter of intent can prevent wasted time by identifying the deal points that must be settled before final contracts are prepared.
Prepare the Purchase Agreement
After the major terms are agreed upon, the parties move into the purchase agreement. This is the primary contract that governs the sale. It should match the economics of the letter of intent but also include the legal details needed to transfer ownership safely.
The agreement may address purchase price allocation, representations and warranties, indemnification, closing conditions, noncompete terms where allowed, employee matters, and post-closing obligations. Because this document controls the final transfer, it is usually reviewed carefully by legal counsel for both sides.
Complete Closing Steps and Transfer Ownership
Closing is more than signing a stack of papers. It usually includes finalizing loan documents, collecting signatures, transferring funds, confirming required approvals, and delivering the assets or equity interests promised in the agreement. In some deals, escrow is used to hold money until all conditions are met.
The closing timeline can be quick once every condition is satisfied, but slowdowns are common if the lender needs last-minute documents, the landlord must approve a lease assignment, or an agency must issue a license. Buyers should expect active coordination during this phase and should keep all advisers informed.
Plan for the First Weeks After Closing
Ownership transfer is not the end of the process. The period immediately after closing is often when a buyer proves whether the acquisition thesis was sound. A good transition plan focuses on employees, customers, vendors, and systems so the business can continue operating without disruption.
Important post-closing tasks often include:
- Introducing the new owner to staff and key clients
- Confirming bank accounts, payment systems, and vendor accounts
- Reviewing operating procedures and controls
- Monitoring cash flow closely
- Keeping the seller available for training, if agreed
The first month matters because employees and customers may be watching for changes. Even a well-negotiated transaction can lose value if the handoff is chaotic. Buyers who plan the transition early usually have a better chance of preserving continuity.
Common Timing Challenges
Several issues can slow the process. Missing financial records are a frequent problem, especially when a small business has not kept clean books. Another common delay is lender review, since financing approvals can require repeated clarification and documentation. Negotiations may also stall if the seller is emotionally attached to the business or if the buyer is trying to change too many terms at once.
Other delays may come from third parties. Landlords, franchisors, regulators, escrow agents, and insurers can all affect timing. Buyers who understand that a business acquisition involves many moving parts are usually better prepared for the time it takes to finish the deal.
Frequently Asked Questions
How long does it usually take to buy a business?
The timeline varies widely, but many acquisitions take several months from search to closing. Deals that require financing, extensive due diligence, or regulatory approval often take longer.
What is the most important step before making an offer?
The most important early step is defining clear criteria and reviewing enough information to know whether the business fits your goals. Without that preparation, buyers often waste time pursuing poor matches.
Why is due diligence so important?
Due diligence verifies the facts behind the seller’s claims. It helps uncover financial, legal, operational, and tax issues before the buyer becomes locked into a bad deal.
Can a deal still change after the letter of intent?
Yes. The letter of intent sets the framework, but the final purchase agreement can still change after deeper review, lender feedback, or negotiation of closing conditions.
What should buyers focus on after closing?
Buyers should focus on continuity: keeping employees informed, maintaining customer relationships, and making sure cash flow, systems, and vendor accounts are functioning correctly.
References
- How Long Does It Take to Buy a Business — BizBuySell. 2025-01-01. https://www.bizbuysell.com/learning-center/article/how-long-buy-business/
- What To Expect: A Chronology for Buying a Business — FindLaw. 2026-07-09. https://www.findlaw.com/smallbusiness/starting-a-business/what-to-expect-a-chronology-for-buying-a-business.html
- Business Acquisition Timeline Guidance — U.S. Small Business Administration. 2026-07-09. https://www.sba.gov/business-guide/plan-your-business/buy-existing-business
- Buying a Business — Internal Revenue Service. 2026-07-09. https://www.irs.gov/businesses/small-businesses-self-employed/buying-a-business
- Buying or Selling a Business — Federal Trade Commission. 2026-07-09. https://www.ftc.gov/business-guidance/resources/buying-selling-business