
Bond for Deed vs. Owner Financing: A Practical Guide
Understand how bond for deed and owner financing compare, and which real estate financing option better matches your goals and risk tolerance.
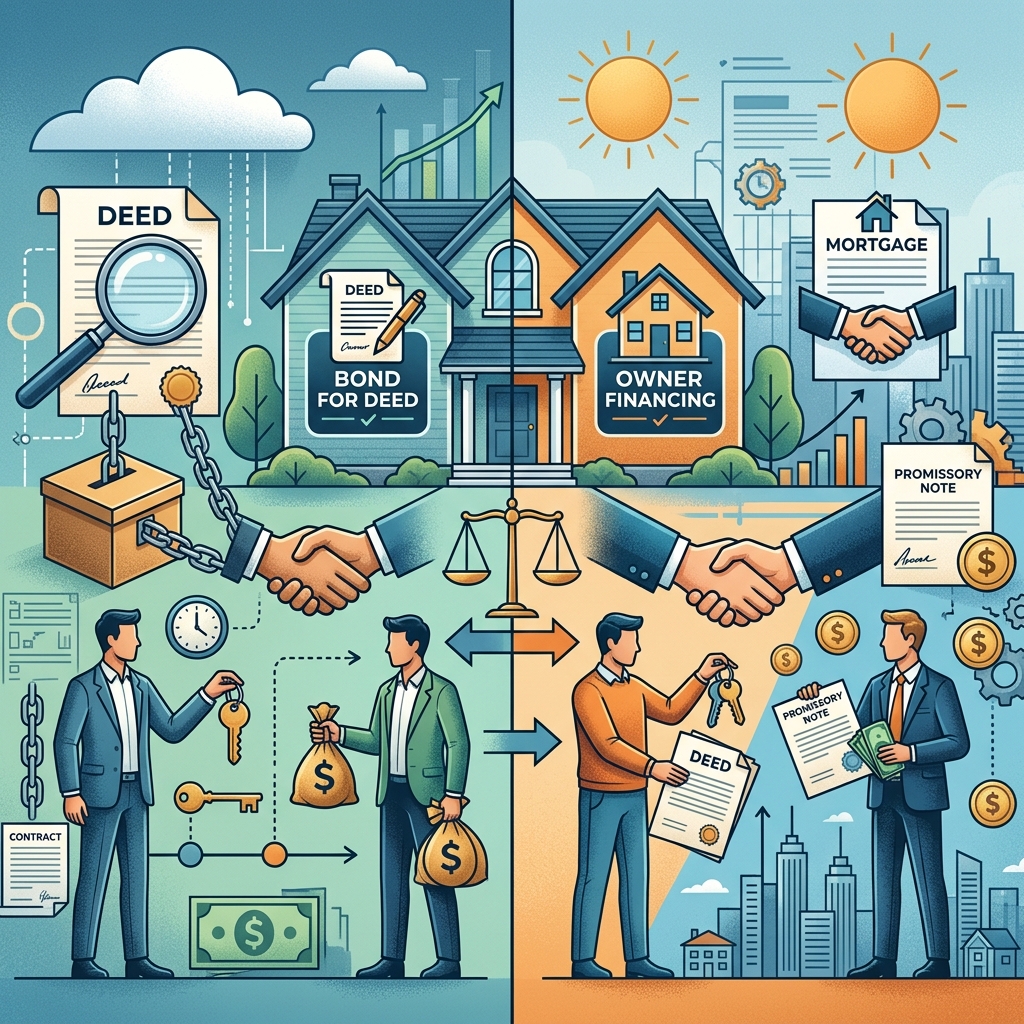
Alternative real estate financing methods have become increasingly important for buyers and sellers who cannot, or prefer not to, rely on traditional bank mortgages. Two of the most common approaches are bond for deed arrangements and owner financing, often called seller financing.Both structures can open doors to homeownership and investment opportunities, but they also introduce unique legal, financial, and practical risks that you should understand before signing any contract.
What Are Bond for Deed and Owner Financing?
At a high level, both bond for deed and owner financing are forms of seller-based financing where the property owner acts as the lender rather than a bank or mortgage company. The buyer pays over time, and the seller is compensated through principal and interest payments.
Bond for Deed: Core Concept
A bond for deed (often called a contract for deed or installment land contract in many states) is an agreement where the buyer makes installment payments to the seller while the seller retains legal title until the agreed amount is fully paid. In some jurisdictions, such as Louisiana, bond for deed is specifically recognized and regulated in state law.
Typical characteristics of a bond for deed include:
- The buyer takes possession and uses the property, gaining equitable title (the economic benefits of ownership).
- The seller keeps legal title and records the contract, or places the deed in escrow, until the final payment.
- Closing costs and bank-related fees such as appraisals, underwriting, and points may be reduced or avoided.
- If the buyer defaults, the seller may be able to cancel the contract and reclaim the property, often through a faster process than foreclosure.
Owner Financing: Core Concept
Owner financing (seller financing) is broader in scope. It refers to any transaction in which the seller extends credit directly to the buyer instead of the buyer obtaining a bank mortgage. Owner financing can be structured in several ways, including:
- A traditional note and mortgage or deed of trust, where the deed transfers to the buyer at closing and the seller holds a lien.
- A second mortgage behind an existing bank loan.
- A land contract or contract for deed, where the seller keeps title until payoff (functionally similar to bond for deed).
- Rent-to-own or lease-option agreements, which combine tenancy with a future purchase right.
Because owner financing is flexible, parties can negotiate interest rates, payment schedules, balloon payments, and default remedies to fit their specific situation.
Key Structural Differences
The most important distinction between many bond for deed arrangements and more traditional owner financing is when the deed transfers to the buyer.
| Feature | Bond for Deed / Contract for Deed | Traditional Owner Financing (Note & Mortgage) |
|---|---|---|
| Deed Transfer | After buyer completes all required payments; seller holds title in the meantime. | At closing; buyer receives deed and seller holds a lien secured by mortgage or deed of trust. |
| Buyer's Legal Ownership | Delayed until payoff; buyer has equitable title and possession. | Immediate; buyer has legal and equitable title subject to seller's lien. |
| Default Consequences | May allow cancellation of contract and repossession without full foreclosure, depending on state law. | Usually requires foreclosure or other formal lien enforcement procedures. |
| Closing Process | Often faster, with fewer bank-related requirements. | Can be more formal and paperwork-heavy, similar to a standard mortgage closing. |
| Buyer Protections | Vary widely; in some states buyer has limited protection until significant equity is built. | Typically higher due to recording, foreclosure rules, and consumer protection laws. |
When Buyers and Sellers Consider These Options
Bond for deed and owner financing are often considered when traditional mortgage financing is difficult or undesirable.
Common Buyer Motivations
- Limited access to bank loans: Buyers with weaker credit histories, self-employment income, or high debt may struggle to qualify for conventional financing.
- Need for faster closing: Time-sensitive situations, such as relocating quickly, purchasing a unique property, or competing in a hot market, can make speedy owner-financed deals appealing.
- Desire for flexible terms: Buyers may negotiate nonstandard down payments, interest-only periods, or balloon payments to match their cash flow and investment plans.
- Property characteristics: Some properties (older homes, nontraditional structures, or properties needing significant repair) might not meet bank underwriting guidelines, making seller financing more realistic.
Common Seller Motivations
- Broader buyer pool: Sellers can attract buyers who cannot qualify for conventional loans, potentially selling faster or at better terms.
- Income stream: Monthly principal and interest payments create a long-term income source, often at a higher yield than traditional fixed-income investments.
- Potential tax planning benefits: In some situations, spreading gain recognition over several years can affect tax treatment (buyers and sellers should consult a tax professional).
- Reduced closing costs: Bond for deed-type contracts may avoid certain transactional costs like points, appraisals, and PMI.
- Control over default remedies: Maintaining title or a lien gives the seller security if the buyer fails to pay.
Pros and Cons for Buyers
From the buyer's perspective, bond for deed and owner financing offer real advantages, but also serious trade-offs that must be weighed carefully.
Buyer Advantages
- Easier qualification: No traditional mortgage underwriting means fewer strict credit and income requirements.
- Access to homeownership: Buyers who are currently unable to obtain a bank loan can still purchase and begin building equity.
- Negotiable terms: Interest rate, payment schedule, and balloon provisions are often flexible, allowing customization.
- Locked-in price: The purchase price is typically set in the contract, which can be advantageous in rising markets.
- Faster timeline: Because appraisals, underwriting, and many lender requirements may be skipped, closings can occur more quickly.
Buyer Disadvantages
- Delayed legal ownership in bond for deed: Until the last payment is made, the seller retains title, and falling behind on payments can jeopardize years of investment.
- Risk of losing equity upon default: Depending on state law and contract terms, a buyer who defaults early may lose all payments and improvements without reimbursement.
- Responsibility for taxes and maintenance: Buyers are typically required to pay property taxes, insurance, and upkeep even before receiving title.
- Potentially fewer consumer protections: In some jurisdictions, buyer protections in contract-for-deed style arrangements are weaker than in conventional mortgages, though many states have strengthened regulations.
- Balloon payment risk: Many owner-financing deals include a balloon payment after several years, requiring the buyer to refinance or pay a large lump sum.
Pros and Cons for Sellers
Sellers must weigh income potential against legal obligations and default risk when considering bond for deed or owner financing.
Seller Advantages
- Expanded market: Sellers can reach buyers who otherwise could not purchase, helping move challenging properties.
- Secured interest: Retaining legal title in a bond for deed, or recording a mortgage in traditional owner financing, gives the seller leverage if payments stop.
- Regular cash flow: Monthly payments provide predictable income, often with an interest rate set by the parties.
- Potentially lower transaction costs: Bond for deed deals may forgo some typical closing expenses associated with bank loans.
- Flexibility in structuring the deal: Sellers can tailor down payments, interest rates, and balloon payments to manage risk and return.
Seller Disadvantages
- Exposure to buyer default: If the buyer fails to pay, the seller may need to cancel the contract, foreclose, or otherwise reclaim the property, which takes time and money.
- Compliance with complex regulations: Some U.S. states impose detailed rules on contract-for-deed arrangements and owner-financing, including disclosure requirements and cure periods.
- Delayed receipt of full sale proceeds: Seller financing spreads payments over several years, which may not suit sellers needing immediate cash.
- Property management risk in default: If the contract is cancelled or the property is taken back, the seller may inherit deferred maintenance or legal disputes.
Legal and Regulatory Considerations
Because bond for deed and owner financing involve significant financial commitments and property rights, state law plays a crucial role in how these contracts operate.
Recording and Escrow
- Recording the agreement: In many jurisdictions, recording a bond for deed or owner financing contract in the public land records helps protect both parties by establishing notice of the arrangement.
- Escrowed deeds: Some bond for deed structures place the deed in escrow with a neutral third party until the buyer completes payment obligations, reducing the risk of seller misconduct.
Default Procedures and Buyer Protections
- Cure periods: Modern laws in some states require a period—often 30 to 90 days—during which the buyer can cure a default before the contract is cancelled.
- Equity protection: Where buyers have built substantial equity, statutes may require sellers to proceed through foreclosure rather than simple cancellation, providing stronger buyer protections.
- Remedies for improvements: In certain scenarios, a defaulting buyer may be able to pursue reimbursement for improvements that substantially increased property value, although this is highly jurisdiction-specific.
Consumer Finance and Lending Laws
Owner-financing arrangements may implicate consumer protection laws similar to those that govern traditional mortgages, including disclosures, interest rate limitations, and servicing obligations. Because these rules vary, it is critical for both parties to seek local legal advice before drafting or signing contracts.
Practical Tips for Structuring Safer Deals
Whether you are a buyer or seller, thoughtful contract design and professional guidance are essential to reducing risk.
For Buyers
- Insist on written, detailed contracts that spell out purchase price, interest rate, payment schedule, balloon payments, tax and insurance responsibilities, and default remedies.
- Verify title status and existing liens through a title search or closing professional, especially when using bond for deed.
- Understand default consequences in your state—including cure periods, equity protection rules, and whether foreclosure is required.
- Plan for balloon payments by confirming your likely ability to refinance or raise funds in the future.
- Consult legal and tax advisors to review the contract and explain tax implications and long-term risks.
For Sellers
- Screen buyers carefully by reviewing income sources, payment history, and their plan to handle balloon payments or refinancing.
- Require a meaningful down payment to give buyers a stake in the property and reduce default risk.
- Comply with state-specific rules about disclosures, recording, and default procedures, especially for contract-for-deed style transactions.
- Use escrow services for collections and deed handling to add an extra layer of accountability.
- Obtain professional drafting of the note, mortgage, or bond for deed contract to avoid unenforceable or ambiguous terms.
Choosing Between Bond for Deed and Owner Financing
There is no single “best” option; the right choice depends on risk tolerance, legal environment, and the parties' financial objectives.
When Bond for Deed May Be Preferable
- You need to avoid or minimize bank-related closing costs such as points, appraisals, and PMI.
- The property or buyer does not qualify for conventional financing but both parties still wish to proceed with a sale.
- The seller wants to retain title as security until payment is complete.
- The jurisdiction has strong statutory protections for buyers in contract-for-deed transactions, balancing risk.
When Traditional Owner Financing May Be Preferable
- The buyer wants immediate legal ownership with the deed transferring at closing, subject to a mortgage lien.
- Both parties prefer a structure that resembles conventional mortgage financing, with well-understood foreclosure procedures and consumer protections.
- The deal involves complex existing financing, such as wraparound mortgages or second liens, which are more easily layered within standard owner-financing frameworks.
- Either party prioritizes predictable legal remedies and clear regulatory guidance.
Frequently Asked Questions
Is bond for deed the same as owner financing?
Bond for deed is a type of owner financing. In many states, it is referred to as a contract for deed or installment land contract, and it represents one way a seller can finance a buyer directly. However, owner financing also includes other structures like note-and-mortgage agreements, rent-to-own, and wraparound loans.
Who holds the deed in a bond for deed transaction?
In a typical bond for deed arrangement, the seller keeps legal title until the buyer has fully satisfied payment obligations. Sometimes the deed is held in escrow by a neutral third party, to be delivered upon completion.
Can I lose all my payments if I default under a bond for deed?
It is possible for a defaulting buyer to lose equity under a bond for deed or contract for deed, particularly in the early years of the agreement. However, many states now require cure periods and may provide additional protection once the buyer has built significant equity. Legal advice specific to your state is essential.
Does owner financing require a credit check?
Because the seller is the lender, credit review is largely a matter of negotiation. Many owner-financing deals rely less on formal credit scoring and more on down payment size, income verification, and the parties' risk appetite. Sellers often still evaluate the buyer's ability to pay to reduce default risk.
Should I involve a lawyer or closing professional?
Yes. Given the significant financial and legal consequences, both buyers and sellers are strongly advised to work with real estate attorneys and experienced closing professionals when entering into bond for deed or owner-financing agreements. Professionals can help with title searches, contract drafting, recording, and compliance with local law.
References
- Bond for Deed vs Owner Financing: Pros and Cons — Rocket Lawyer. 2023-09-01. https://www.rocketlawyer.com/real-estate/home-ownership/real-estate-financing/legal-guide/bond-for-deed-vs-owner-financing-pros-and-cons
- Chapter 5: Contract For Deed & Bond For Deed — Southern Loan Servicing. 2024-02-15. https://www.southernloanservicing.com/chapter-5-contract-for-deed-bond-for-deed/
- Contract for Deed: Complete Owner-Financing Guide — Certinal. 2025-01-10. https://www.certinal.com/blog/contract-for-deed-explained
- What is owner financing, and how does it work? — Bankrate. 2023-08-22. https://www.bankrate.com/mortgages/owner-financing/
- Owner Financing: Definition, Example, Advantages, and Risks — Investopedia. 2024-03-18. https://www.investopedia.com/terms/o/owner-financing.asp
- Bond for Deed Louisiana — Southern Title. 2022-06-01. https://www.southerntitleonline.com/services/bond-for-deed
- When to use a Bond for Deed — Escrow Services Inc. 2021-11-05. https://www.escroserv.com/bond-for-deed-information/when-to-use-a-bond-for-deed/
Similar Articles








Read full bio of medha deb


