Avoiding Worker Misclassification Pitfalls
Understand the legal, tax, and operational risks of worker misclassification before they become costly mistakes.
Why worker classification deserves close attention
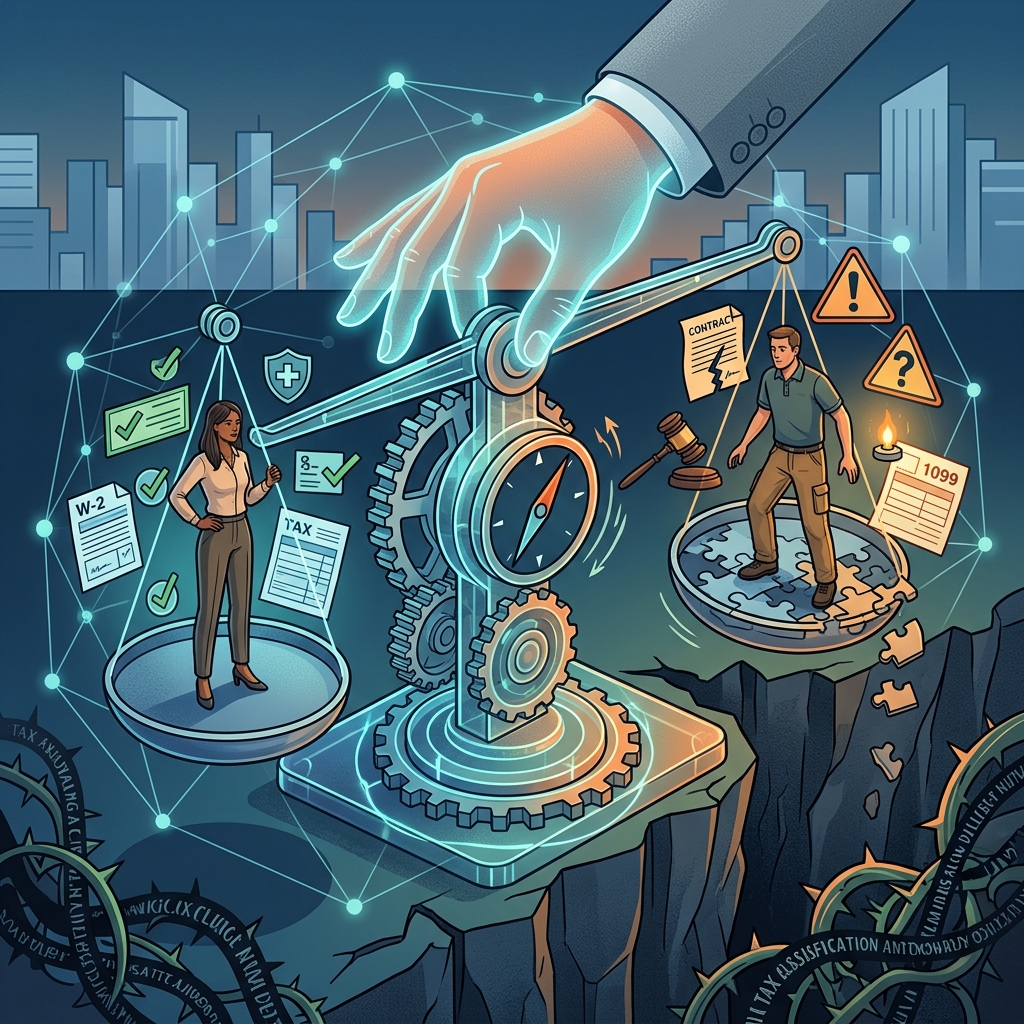
Labeling someone as an independent contractor may feel like a simple hiring decision, but that label can carry major legal and financial consequences. Under federal wage law, employers are responsible for determining whether a worker is truly an employee or an independent contractor, and treating an employee as a contractor can deprive that worker of minimum wage, overtime, and other protections.
The issue matters far beyond payroll. A mistaken classification can affect tax withholding, benefit eligibility, insurance obligations, unemployment coverage, and the company’s exposure to back pay claims. The risk is especially high because worker status is not determined by the title in a contract alone; it depends on the real working relationship.
What usually triggers a misclassification problem
Misclassification often happens when businesses try to treat workers as contractors even though the company still controls important parts of the job. Indicators of control include setting schedules, supervising performance, restricting outside work, or imposing requirements that go beyond basic legal or regulatory standards.
Another common mistake is assuming temporary or project-based work automatically supports contractor status. The length of the assignment does not decide the classification by itself. A worker can stay on for only a short time and still qualify as an employee if the business controls the work in the way employment law describes.
- Control over hours or schedule
- Direction over how tasks are completed
- Limits on working for other clients
- Training or supervision that resembles an employee relationship
- Long-term work that looks integral to the business
The main tests used to evaluate status
Different agencies and laws use different tests, but they often ask similar questions. The U.S. Department of Labor now applies an updated economic reality approach under the Fair Labor Standards Act, finalized in 2024, to assess whether a worker is an employee or an independent contractor.
The IRS uses a framework that looks at behavioral control, financial control, and the relationship between the parties. These concepts overlap with what many employers already recognize in practice: if the company directs the work closely, pays in a way that resembles wages, or offers employee-type benefits, the worker may be an employee rather than a contractor.
| Factor | What it asks | Why it matters |
|---|---|---|
| Behavioral control | Does the company direct how the work is done? | Strong direction can point to employee status. |
| Financial control | Who controls payment, expenses, and business risk? | Contractors usually bear more financial independence. |
| Relationship of the parties | Is there a continuing relationship or employee-style benefits? | Ongoing work and benefits can suggest employment. |
Why misclassification is expensive
The legal cost of misclassification can be substantial. Workers who were treated as contractors may sue for unpaid wages, overtime, and other denied benefits, and employers may also face liability under employment and employee benefit laws.
Tax exposure adds another layer of risk. If a worker should have been treated as an employee, the business may owe employment taxes that were never withheld, including the employer and employee shares of Social Security and Medicare taxes, along with interest and penalties.
There is also a broader business impact. Misclassification can create issues with retirement plans, insurance programs, and other benefits whose tax treatment depends on proper worker status. In other words, the problem is not confined to the payroll department; it can spread into human resources, finance, and compliance operations.
How state law can make the analysis even harder
Federal law is only part of the picture. Employers must also evaluate state classification rules, and those rules may be stricter than federal standards. In some jurisdictions, the test for contractor status is narrow, and a worker may qualify as an employee under state law even if the federal analysis looks closer.
Businesses with workers in multiple states face a particularly complex compliance challenge. A role that appears correctly classified in one state may require a different approach somewhere else, which is why a single nationwide template is often not enough.
Practical warning signs that a contractor may really be an employee
Employers should be cautious when several employee-like features appear at the same time. One or two details may not decide the issue, but a pattern of control and integration often raises red flags.
- The worker receives detailed instructions rather than broad project goals
- The company sets the worker’s hours or requires regular attendance
- The worker uses company tools, systems, or branded materials
- The role is ongoing rather than tied to a discrete independent business
- The worker participates in meetings, reviews, or other internal processes like staff
These signs do not automatically prove misclassification, but they should prompt a closer review. The more the relationship resembles employment in practice, the more carefully the classification should be examined.
How to reduce the risk before a problem starts
A thoughtful classification process is the best defense. Employers should evaluate each role individually instead of assuming that every freelance, part-time, or project-based worker fits the contractor category.
Written agreements can help document the business relationship, but paperwork alone is not enough. The actual day-to-day arrangement must match the written terms. If the company treats the worker like staff, a contract calling the person an independent contractor will not usually solve the problem.
- Review the actual duties and level of supervision for each role
- Check whether the worker truly runs an independent business
- Confirm that payment practices match contractor status
- Avoid giving contractor roles employee-style benefits or treatment
- Reassess classifications when duties, duration, or supervision change
Policies, training, and audits matter
Classification mistakes often arise because hiring managers and supervisors do not share a common rulebook. Internal policies should explain who can approve contractors, what factors must be reviewed, and when legal or HR review is required.
Training is equally important. Managers who understand the difference between directing work and simply setting project expectations are less likely to create an accidental employment relationship. Regular audits can also catch drifting arrangements, especially when a contractor stays for years or gradually takes on employee-like responsibilities.
Audits should look for mismatches between labels and reality. For example, a contractor who has a company business card, attends all-hands meetings, is evaluated like staff, and works under close daily supervision may need to be reclassified.
What to do if a mistake is discovered
If a company discovers that a worker may have been misclassified, fast action usually reduces harm. The business should review the relationship, document the facts, and correct the status if needed. It may also need to fix payroll practices, withholding, benefit treatment, and tax reporting going forward.
Legal counsel can help evaluate exposure under both federal and state rules, especially where multiple agencies may be involved. Because the consequences can include wages, taxes, penalties, and benefits issues, a structured response is often better than waiting for a complaint or audit.
Frequently asked questions
Is a signed contractor agreement enough to prove independent contractor status?
No. Written terms matter, but agencies and courts focus on the real working relationship, including control, financial independence, and the practical day-to-day setup.
Can a short-term worker still be treated as an employee?
Yes. The length of the assignment does not decide status by itself. A temporary worker may still be an employee if the company controls the work in ways that resemble employment.
Why do state rules matter if federal law already applies?
State tests can be stricter or different from federal standards, so a worker may be a contractor under one rule and an employee under another.
What is the biggest mistake employers make?
One of the most common mistakes is treating control-heavy, ongoing work as contractor work simply because the company wants flexibility or lower labor costs.
How can employers stay compliant over time?
They should review worker roles regularly, train managers, use consistent approval processes, and revisit classifications whenever the scope of work changes.
A safer approach to flexible hiring
Independent contractors remain a useful staffing option when the arrangement is truly independent. The key is to preserve that independence in practice, not just on paper. When businesses are careful about control, documentation, payment structure, and ongoing review, they are more likely to avoid the costly fallout that comes with misclassification.
For employers, the most reliable strategy is to treat classification as an ongoing compliance task rather than a one-time hiring formality. That mindset helps protect the company, the worker, and the business relationship itself.
References
- Misclassification of Employees as Independent Contractors Under the Fair Labor Standards Act — U.S. Department of Labor, Wage and Hour Division. 2024-03-11. https://www.dol.gov/agencies/whd/flsa/misclassification
- Understanding the Risks of Improper Classification of Project Workers — BHSG. 2024. https://bhsg.com/resources/understanding-the-risks-of-improper-classification-of-project-workers
- Employers Face Misclassification Risk With Independent Contractor Arrangements — Pillsbury Law. 2024. https://www.pillsburylaw.com/en/news-and-insights/dol-fair-labor-standards-act-contractors.html
- Worker Misclassification Poses Serious Risks for Employers — Holland & Hart. 2023. https://www.hollandhart.com/articles/workermisclassificationposesseriousrisks.pdf
- Worker Classification 101: Employee or Independent Contractor — Internal Revenue Service. 2024. https://www.irs.gov/newsroom/worker-classification-101-employee-or-independent-contractor
Similar Articles








Read full bio of medha deb