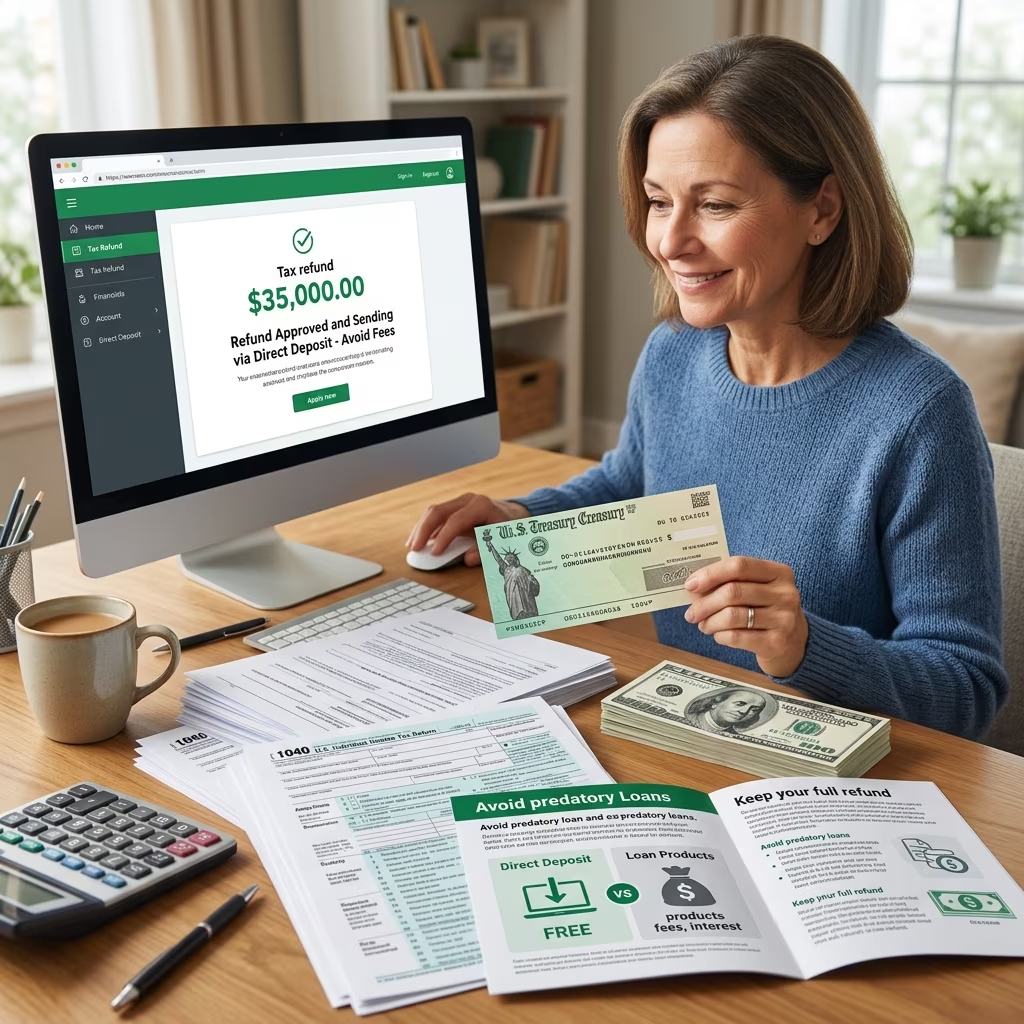
Many taxpayers are tempted by offers to get their tax refund money “right now” through tax refund loans and related products. These loans may sound convenient, but in reality they often mean paying steep fees and interest to borrow money that already belongs to you. Understanding how these products work, what they really cost, and what better options you have can help you keep more of your refund and avoid unnecessary debt.
What Is a Tax Refund Loan?
A tax refund loan is a short-term loan that lets you access cash based on the amount of your expected tax refund before the government actually issues it. These loans are sometimes marketed as refund anticipation loans (RALs), refund advances, or tied to special checks or prepaid cards.
- Loan based on expected refund: The lender reviews your tax return and estimates your refund, then issues a loan for part or all of that amount.
- Very short term: The loan typically lasts only until the IRS processes your return and sends the refund, usually about 7–21 days for electronically filed returns.
- Automatic repayment: When your refund arrives, it is used to pay back the loan. Any remaining balance is passed on to you.
Some tax preparers and financial institutions advertise these products as a way to get an instant refund. In reality, you are getting a loan, not your actual tax refund.
Common Types of Refund-Based Products
The market for refund-related products includes several variations, all built around using your expected tax refund as collateral.
Refund Anticipation Loans (RALs)
Refund anticipation loans are classic tax refund loans. They are bank loans secured by your expected refund, with terms that align with the processing time of the IRS.
- Loan fees often range from about $34 to $130, plus additional charges at some providers.
- Effective annual interest rates can be extremely high, sometimes estimated between 50% and 500% when fees are converted to an annualized rate.
- If your actual refund is smaller than expected, you still owe the full loan amount plus any associated charges.
Refund Advance Loans
Refund advance loans are similar to RALs but may be marketed with different fee structures.
- They are often offered by tax preparation companies in partnership with banks or other lenders.
- Loan amounts are based on a portion of your expected refund, sometimes minus preparation fees and other charges.
- Some providers promote advances with zero interest and no direct loan fees, but costs may still appear elsewhere, such as through tax prep charges or financial product fees.
Refund Anticipation Checks and Prepaid Cards
Another product is the refund anticipation check or temporary account used to receive your refund.
- A bank opens a short-lived account to receive your IRS refund, then issues a check or prepaid card to you.
- You may pay account administration fees and potentially fees to cash the check or use the card.
- Although this is not technically a loan, it is still a paid product that reduces the amount of money you ultimately receive.
How These Loans Really Work Behind the Scenes
Even when marketing sounds simple—“get your refund today”—behind the scenes, tax refund loans involve multiple players and legal obligations.
| Step | What Happens |
|---|---|
| Tax preparation | You have your return prepared and e-filed, usually by the same provider that offers the loan. |
| Loan application | The lender reviews your return and may consider your income and credit to approve a short-term loan based on the expected refund. |
| Loan disbursement | If approved, you receive money on a card or into an account, often within the same day. |
| IRS processing | The IRS processes your return and sends the refund, usually within about three weeks when you e-file. |
| Repayment | Your refund is routed to repay the loan first; any leftover amount is then forwarded to you. |
Because your refund is assigned to the lender or routed through a designated account, you generally will not receive the refund directly from the IRS. Instead, the loan is cleared first, and you only get what remains.
The True Costs and Risks of Tax Refund Loans
When you step back from the marketing, the primary problem with tax refund loans is the combination of high costs and real risk for a very short-term benefit.
High Fees and Effective Interest Rates
Although the loan may last only days or weeks, fees can add up to strikingly high annualized interest rates. For many consumers, these products are much more expensive than simply waiting for their refund.
- Loan and account fees can total $34–$130 or more, with extra application or processing charges at some providers.
- When converted to an annual percentage rate (APR), these fees can resemble payday lending levels, sometimes calculated between 50% and 500%.
- Additional charges may appear in tax preparation costs or financial product fees, which indirectly raise the overall price of getting your advance.
Debt Risk if Your Refund Is Smaller or Seized
Another major risk is what happens if your refund is not what the lender expected. You are borrowing against a future payment that is not guaranteed.
- If your refund is lower than predicted—due to calculation errors, offsetting debts, or IRS adjustments—you still owe the full loan amount.
- Your refund can be seized to pay debts such as defaulted student loans, past-due child support, or older tax liabilities through government offset programs.
- In such cases, you may be left repaying the loan out of pocket, plus any interest and penalties under the loan agreement.
Because many low-income taxpayers use these products, advocacy groups have labeled refund anticipation loans a form of predatory lending that targets financially vulnerable households.
Short-Term Benefit vs. Long-Term Impact
The main benefit of a tax refund loan is speed: you receive money days or weeks before your refund would normally arrive. However, the long-term impact can be negative.
- Fees and charges reduce the net value of your tax refund, leaving you with less money to cover essentials or pay down debt.
- Relying on expensive short-term loans can create a cycle of dependency, especially if you face recurring financial shortfalls each year.
- Because the loans are secured by your refund, you have fewer options if something goes wrong with your tax filing or your eligibility for certain credits.
Who Is Most Affected by These Products?
Research and consumer protection agencies have noted that tax refund loans disproportionately affect people with lower incomes.
- Many borrowers turn to refund loans to cover basic living expenses, overdue bills, or emergencies.
- A large portion of users qualify for refundable tax credits, such as the Earned Income Tax Credit (EITC), which can boost refund amounts and make these loans more attractive.
- Households without bank accounts are often offered refund checks or prepaid cards with associated fees, further shrinking their take-home refund.
Because these products are marketed heavily during tax season and often bundled with tax preparation, it can be easy to agree to a loan without fully understanding the cost.
Smarter Alternatives: How to Get Your Refund Quickly and Safely
The good news is that you can usually receive your tax refund relatively fast without paying for a loan. A few practical strategies help you keep your full refund.
File Electronically and Use Direct Deposit
Filing electronically and choosing direct deposit is the simplest and most effective way to speed up your refund.
- The IRS issues most refunds within about 21 days when a return is filed electronically.
- Direct deposit sends your refund straight to your bank account, avoiding mailing delays and check-cashing fees.
- This approach often makes a refund loan unnecessary because the wait time is relatively short.
Use Free or Low-Cost Tax Filing Services
Paying for tax preparation plus a loan can quickly become expensive. Instead, look for free or low-cost options.
- The IRS and community organizations offer free tax preparation for many taxpayers through programs such as Volunteer Income Tax Assistance (VITA).
- Online tools and IRS resources provide forms and guidance if you choose to prepare your own return.
- Using these services reduces the overall cost of filing and helps you keep more of your refund.
Open a Bank Account if You Don’t Have One
For people without bank accounts, refund anticipation checks and prepaid cards are often promoted as the only way to receive funds. In reality, opening a basic account can be simpler and cheaper.
- A low-fee checking or savings account allows you to use direct deposit and avoid administrative charges on temporary accounts.
- Many financial institutions offer entry-level accounts with no minimum balance or low monthly fees.
- Having a bank account also improves your options for managing money throughout the year, not just during tax season.
Plan Ahead for Tax Season
Refund loans often feel attractive because people are facing immediate financial pressure. Planning ahead can reduce that pressure.
- Review your paycheck withholding to avoid very large refunds, which can indicate that too much is being withheld during the year.
- Set aside small amounts in a savings buffer so that you are less dependent on rapid access to your refund.
- If you have an urgent bill, consider negotiating a short extension until your refund arrives rather than taking a high-cost loan.
When You Should Completely Avoid Tax Refund Loans
While consumer advocates generally advise against most refund loans, there are situations where they are especially risky and should be avoided altogether.
- If you suspect your refund may be seized: Tax refunds can be used to collect defaulted federal student loans, child support arrears, and past-due taxes through the Treasury Offset Program.
- If your finances are unstable: Borrowing against your refund when you already struggle with debt may add another obligation that is difficult to manage.
- If the fees are high relative to the benefit: Paying $100 or more to receive your refund only a couple of weeks earlier is rarely a good trade-off.
If you believe your refund might be subject to seizure—especially for student loan defaults—you can contact federal resources to check your status and explore options to get loans out of default before you file.
Practical Checklist Before Considering a Refund Loan
If you are thinking about a tax refund loan, review this quick checklist first.
- Have you calculated how long it will take to receive your refund through e-file and direct deposit?
- Do you fully understand all fees and charges associated with the loan or financial product?
- Are you confident your refund will not be reduced or seized for existing debts?
- Have you explored free tax preparation and low-cost banking options?
- Is borrowing against your refund truly necessary, or can you adjust bills, budgets, or payment timing instead?
Answering these questions honestly can help you decide whether a refund loan is worth the price—or whether you are better off simply waiting for your own money.
Frequently Asked Questions
Are tax refund loans ever a good idea?
Tax refund loans may provide quick access to cash for people facing urgent expenses, but they typically come with high effective costs and real risks if the refund is delayed, reduced, or seized. For most taxpayers, waiting for an e-filed refund and using direct deposit is safer and cheaper.
How fast will I get my refund without a loan?
When you file electronically and choose direct deposit, the IRS issues most refunds within about 21 days. This timeline makes many short-term refund loans unnecessary, given the extra fees involved.
What happens if my refund is smaller than the loan?
If your actual refund is less than the loan amount you received, you are still responsible for repaying the full loan, including any interest and penalties. This can leave you repaying debt out of pocket instead of relying on your refund.
Can my tax refund be taken to pay other debts?
Yes. Tax refunds may be seized through federal offset programs to pay certain debts, including defaulted federal student loans, child support, and back taxes. If that happens, your refund may not be available to cover a refund loan, leaving you with a debt to the lender.
What is the safest way to receive my refund?
The safest and usually fastest method is to file your taxes electronically, choose direct deposit into your own bank account, and avoid refund-related loans and high-fee products. Combining free or low-cost tax preparation with direct deposit lets you keep nearly all of your refund.
References
- Tax refund tips: Understanding refund advance loans and checks — Consumer Financial Protection Bureau. 2013-01-18. https://www.consumerfinance.gov/archive/blog/tax-refund-tips-understanding-refund-advance-loans-and-checks/
- Be Wary of Tax Refund Anticipation Loans — Westchester County Department of Consumer Protection. 2009-02-19. https://www.westchestercountyny.gov/previous-releases/be-wary-of-refund-anticipation-loans-and-checks
- The Risks and Costs of Tax Refund Anticipation Loans — National Resource Center on Domestic Violence (VAWnet). 2011-01-01. https://www.vawnet.org/material/dont-pay-borrow-your-own-money-risks-and-costs-tax-refund-anticipation-loans
- What You Need to Know About Tax Refund Advances — West Virginia University Extension. 2025-03-01. https://extension.wvu.edu/youth-family/finances/blog/2025/03/01/what-you-need-to-know-about-tax-refund-advances
- The Truth About Rapid Refunds: Refund Anticipation Loans May Not Be Worth the Risk — Leiden & Leiden, P.C. 2016-02-01. https://leidenandleiden.com/the-truth-about-rapid-refunds-refund-anticipation-loans-may-not-be-worth-the-risk/
- Dial Before You File: Protect Your Tax Refund If You Have Student Loan Debt — Student Loan Borrower Assistance (National Consumer Law Center). 2022-01-27. https://www.studentloanborrowerassistance.org/tax-refund/