
AAA Daily Advantage Visa Signature Credit Card Review
An in-depth, plain-language review of the AAA Daily Advantage Visa Signature card, its rewards, fees, and when it may or may not be a good choice.
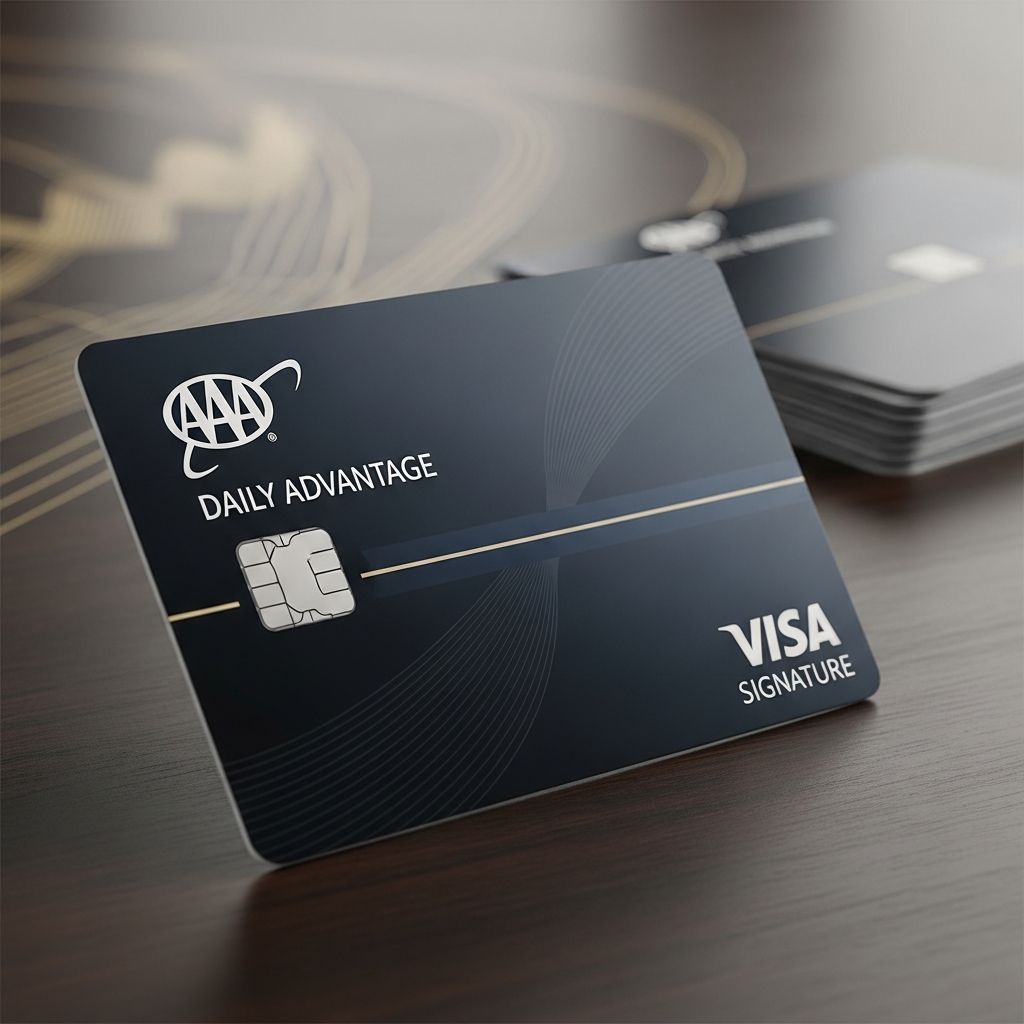
AAA Daily Advantage Visa Signature: An Unbiased Deep Dive
The AAA Daily Advantage Visa Signature credit card, issued by Comenity Capital Bank, is designed for people who value everyday cash-back rewards and AAA-related benefits. This guide breaks down its core features, strengths, and weaknesses in clear, practical terms so you can decide whether it fits your wallet.
Who This Card Is Designed For
This card targets consumers who:
- Already have or are interested in an AAA membership
- Use a credit card frequently for everyday purchases like groceries, gas, and dining
- Prefer straightforward cash-back rewards instead of complex points systems
- Can reliably pay at least the statement balance on time each month to avoid costly interest
Because this is a Visa Signature product, it may also appeal to people who want added travel and purchase protections that often come with this network tier, such as certain travel assistance and extended warranty benefits.
Key Features at a Glance
| Feature | What It Means |
|---|---|
| Issuer | Comenity Capital Bank (a U.S. bank that issues private-label and co-branded cards) |
| Network | Visa Signature – widely accepted domestically and internationally |
| Rewards Type | Cash back-style rewards on everyday spending (exact categories and rates vary by current terms) |
| AAA Tie-In | Rewards, benefits, or discounts oriented around AAA membership and automotive needs |
| APR & Fees | Purchase APR, possible balance transfer APR, late fees, and other charges as specified in the legal agreement |
Understanding the Card Agreement Basics
Every credit card, including the AAA Daily Advantage Visa Signature, is governed by a written cardmember agreement that outlines the terms of your legal obligation. This agreement typically covers:
- Interest rates (APRs) for purchases, balance transfers, and cash advances
- Fees, such as annual fees, late payment fees, and returned payment fees
- How minimum payments are calculated
- How and when terms can change (for example, after a late payment)
- Your rights, including billing error dispute procedures under federal law
Regulation Z (Truth in Lending Act) requires issuers to present key terms in a standardized format, often called the Schumer Box, so consumers can compare cards more easily. Always review this box carefully before applying.
Rewards and Benefits Breakdown
While specific percentages and promotional offers can change over time, the AAA Daily Advantage Visa Signature generally emphasizes cash-back rewards on everyday categories together with AAA-related perks.
Everyday Spending Rewards
Based on typical structures used by co-branded cash-back cards, you can usually expect:
- Elevated rewards on select categories likely important to AAA members, such as gas stations, travel, or automotive expenses
- Base rewards (often 1% cash back or similar value) on other eligible purchases
- Occasional introductory offers or bonus rewards for new cardholders during a promotional period
Before applying, check the most current rewards chart from AAA or the issuer, because card programs can be updated, devalued, or enhanced over time.
Possible AAA-Focused Benefits
Typical AAA co-branded cards tend to weave in perks aligned with membership, which may include:
- Extra rewards on AAA membership dues or renewals
- Higher rewards on qualifying travel booked through AAA
- Enhanced value for automotive or roadside-related purchases
However, these benefits are not guaranteed and can change, so always refer to the latest benefit guide from AAA or the bank.
Visa Signature Protections
Visa Signature cards often come with a package of value-added protections and services administered by the network, such as:
- Travel and emergency assistance services
- Auto rental collision damage waiver (when using the card for eligible rentals)
- Extended warranty on eligible purchases
- Purchase security for certain types of damage or theft
The exact protections and eligibility requirements depend on the specific Visa Signature benefit guide in effect when you receive the card, and these protections are provided by Visa, not AAA or the issuing bank.
Interest Rates, Fees, and Cost Considerations
Even a strong rewards card can be a poor choice if its costs outweigh the benefits for your situation. Key cost-related components include the APR and fees.
Purchase APR and Balance Transfers
Most consumer credit cards use a variable APR that moves with a reference index such as the U.S. prime rate. The APR you receive usually depends on:
- Your credit history and credit score
- Overall debt and income profile
- The issuer’s underwriting policies at the time of approval
Some versions of this card may offer an introductory APR on purchases or balance transfers for a limited period. Federal law requires issuers to disclose when that intro rate ends and what the regular APR will be afterward.
Common Fees You Should Look For
Before you apply, locate the card’s fee schedule and look specifically for:
- Annual fee – not all co-branded cards charge one, but if they do, compare it with your expected rewards value
- Late payment fee – federal rules cap some penalty fees, but they can still be significant
- Balance transfer fee – typically a percentage of the amount transferred
- Cash advance fee – often higher and paired with a higher APR; cash advances also usually start accruing interest immediately
- Foreign transaction fee – important if you travel abroad or shop from international merchants
Comparing these costs with other cards can help you evaluate whether the AAA Daily Advantage Visa Signature is competitive in your own use case.
How the Card Fits Different Spending Profiles
The value of this card changes depending on how you spend and whether you carry a balance.
Best For: AAA Members With Regular Driving and Travel
This card is most appealing if you:
- Already pay for an AAA membership and are likely to keep it
- Spend consistently on gas, travel, and automotive costs
- Pay your statement balance in full or carry only small, short-term balances
Under this scenario, you’re more likely to capture solid net value from the rewards and AAA-related perks while minimizing interest costs.
Less Ideal For: Revolvers or Non-AAA Users
The card may be less suitable if you:
- Frequently carry a high balance, which can make interest charges exceed your rewards value
- Do not use AAA benefits or mostly spend in categories that earn only base-level rewards
- Want ultra-high, uncapped rewards in a very specific category like travel or groceries that a specialized card may offer at a higher rate
In such cases, a low-interest card or a simple, flat-rate cash-back card might be more cost-effective.
Managing the Card Responsibly
Regardless of card type, responsible use is crucial for protecting your credit score and financial well-being. Personal finance experts consistently highlight several best practices when using revolving credit.
Payment and Balance Strategies
- Pay on time every month. Even one 30-day late payment can significantly harm your credit score and may trigger penalty APRs.
- Aim to pay the statement balance in full. Doing so typically avoids interest on purchases, preserving the full value of your rewards.
- Keep utilization low. Credit scoring models often reward consumers who use only a small portion of their available credit across cards.
Security and Data Protection
Because any credit card can expose you to fraud risk, it is important to protect your information. Industry standards such as the Payment Card Industry Data Security Standard (PCI DSS) set minimum requirements for secure storage and handling of card data. For consumers, good practices include:
- Avoiding writing your full card number on paper or in unsecured documents, which can increase theft risk.[10]
- Monitoring statements regularly and setting up alerts for suspicious or large transactions.
- Reporting lost or stolen cards promptly so the issuer can block unauthorized use.
If you run a small business or professional practice and store card information from your clients, you must comply with PCI DSS and other applicable rules; failure can lead to penalties and reputational harm.
Comparing the AAA Daily Advantage Visa Signature to Other Cards
To judge whether this card is right for you, compare it with at least two alternatives:
- A no-annual-fee flat cash-back card that pays a consistent rate on all purchases
- A category-optimized card that offers very high rewards on the spending category you use most, such as travel, groceries, or gas
Major independent financial publishers emphasize comparing cards side-by-side on both rewards and total cost instead of focusing solely on headline bonuses.
| Aspect | AAA Daily Advantage Visa Signature | Flat 2% Cash-Back Card (Example) |
|---|---|---|
| Best Use Case | AAA members with frequent gas/travel & automotive spending | All-around everyday use across many categories |
| Reward Structure | Category-based, with AAA-leaning emphasis | Simple, equal rate on all purchases |
| Complexity | Moderate – must track bonus categories and AAA tie-ins | Low – same rate everywhere |
| Potential Value | High for AAA-focused spenders who pay in full | Predictable, solid value for broad spending |
Application, Approval, and Credit Impact
Applying for the AAA Daily Advantage Visa Signature typically involves a hard inquiry on your credit report, which may cause a small, temporary dip in your credit score. Credit reporting systems in the U.S. collect information from banks and other lenders to build your file, which is then used in credit scoring models to predict risk.
Before You Apply
Steps to consider before submitting an application include:
- Reviewing your credit reports from the major bureaus for errors
- Ensuring you understand the card’s APRs, fees, and rewards structure
- Comparing it to at least one or two competing products
- Confirming that the card aligns with your budget and financial goals
After Approval
Once approved, you should receive:
- Your physical card and account-opening disclosures
- The full cardmember agreement, which you should store securely
- A benefits guide detailing Visa Signature and AAA-related perks
Keep digital copies of these documents in a secure location for later reference, especially when you want to verify how a benefit or fee works.
Frequently Asked Questions (FAQs)
Q: Do I need an AAA membership to apply for the AAA Daily Advantage Visa Signature card?
A: The card is marketed to AAA members and often integrates member-related benefits. In many co-branded programs, you can technically apply without being a current member, but you may not receive the full value of the card without using AAA services. Always check the latest eligibility and membership details from AAA or the issuer.
Q: Will this card help me build my credit history?
A: Yes, if the account is reported to the major credit bureaus and you use it responsibly. Making on-time payments and keeping your balances low relative to your credit limit can contribute positively to your credit profile over time.
Q: Is carrying a balance on this card a good idea to maximize rewards?
A: Generally no. Interest on carried balances often costs more than the cash-back or points you earn. Most experts recommend using rewards cards primarily when you can pay your statement balance in full each month.
Q: How do I dispute a charge on my AAA Daily Advantage Visa Signature card?
A: Federal protections under the Truth in Lending Act and Regulation Z give cardholders specific rights to dispute billing errors, including unauthorized transactions and incorrect amounts. You must notify the issuer promptly, usually in writing, at the address designated for billing inquiries. Follow the instructions in your cardmember agreement for the most accurate and current process.
Q: Is it safe to store my card number for recurring payments?
A: Many large merchants and service providers follow PCI DSS and other industry standards to help protect card data. However, you should still monitor your statements, limit where you store your card number, and promptly report suspicious activity. Avoid writing your card details on paper or storing them in unsecured files, since that increases theft risk.[10]
References
- 1026.58 Internet posting of credit card agreements. — Consumer Financial Protection Bureau. 2024-03-01. https://www.consumerfinance.gov/rules-policy/regulations/1026/58
- Editorial Guidelines — CreditCards.com. 2024-05-01. https://www.creditcards.com/editorial-guidelines/
- Editorial Guidelines — CardRates.com. 2024-04-15. https://www.cardrates.com/editorial-guidelines/
- Guide to Securely Storing Credit Card Information — LawPay. 2023-08-10. https://www.lawpay.com/about/blog/storing-credit-card-information/
- Why You Should Never Write Down Credit Card Information — IntelliPay. 2022-11-30. https://intellipay.com/why-you-should-never-write-down-credit-card-information/
Similar Articles








Read full bio of medha deb




